India’s premium residential real estate market continues to benefit from rising urbanisation, higher household incomes, premiumisation and a growing preference for branded developers. Within Mumbai, limited land availability, redevelopment opportunities and improving connectivity are creating a structural runway for established developers with strong execution capabilities.
Oberoi Realty Limited is positioned around this opportunity through its focus on premium residential developments, commercial assets, hospitality and mixed-use projects. With a strong Mumbai franchise, an expanding project pipeline and its maiden NCR entry through Three Sixty North, the company is gradually evolving from a Mumbai-focused developer into a broader premium real estate platform.
But does Oberoi Realty Ltd. offer a compelling case for long-term investors? Let’s delve deeper.
Stock overview
| Ticker | OBEROIRLTY |
| Industry/Sector | Real Estate |
| CMP | 1861.60 |
| Market Cap (₹ Cr.) | 67,575 |
| P/E | 25.39 (Vs Industry P/E of 33.72) |
| 52 W High/Low | 1986.10 / 1391.20 |
| EPS (TTM) | 72.32 |
| Dividend Yield | 0.44% |
About Oberoi Realty Ltd.
Oberoi Realty is a Mumbai-based real estate developer focused on premium residential, commercial and hospitality developments. The company has built its franchise around large-scale, high-quality projects in established Mumbai locations, with developments spanning residential towers, commercial spaces, malls and hotels. Its strategy is increasingly centred on premiumisation, redevelopment and unlocking value from strategically located land parcels.
FY26 consolidated revenue from operations stood at approximately ₹6,009 crore, while total comprehensive income was around ₹2,508 crore. The company has also been building a sizable future launch pipeline across Mumbai while expanding outside its traditional MMR market.
Key business segments
Oberoi Realty Ltd. operates primarily in the following key business segments:
- Residential: Premium and luxury residential projects across Mumbai and emerging markets.
- Commercial: Grade-A office and commercial developments providing recurring and development-linked income.
- Retail: Shopping and lifestyle assets integrated with large mixed-use developments.
- Hospitality: Hotels and hospitality assets supporting recurring annuity income.
- Mixed-Use Developments: Integrated projects combining residential, commercial, retail and hospitality components.
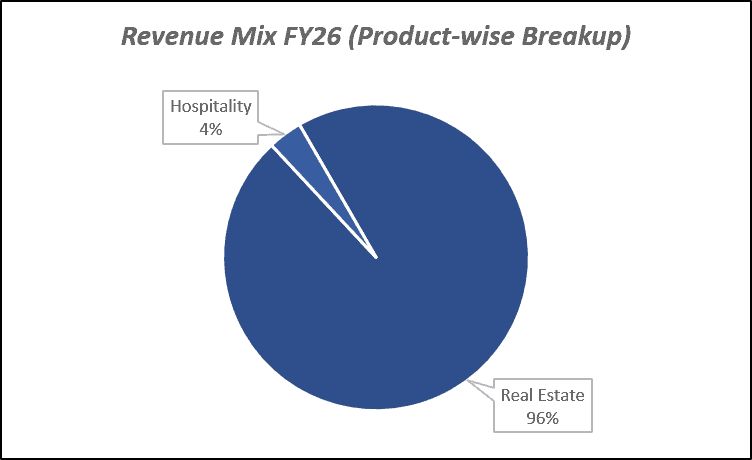
Primary growth factors for Oberoi Realty Ltd.
Oberoi Realty Ltd. key growth drivers:
- Large Mumbai Launch Pipeline: Multiple premium projects across Carter Road, Malabar Hill, Pedder Road, Bandra and other strategic locations can support sustained presales growth.
- NCR Expansion: Three Sixty North in Gurugram marks Oberoi Realty’s first project outside the MMR, opening a new premium residential growth market.
- Mumbai Redevelopment Opportunity: Redevelopment of ageing housing societies and strategically located land parcels provides access to scarce urban land without relying solely on outright land purchases.
- Premiumisation: Rising preference for branded, high-quality homes among affluent buyers can support pricing power and demand for luxury residential projects.
- Diversified Annuity Income: Commercial, retail and hospitality assets can complement residential cash flows and improve earnings visibility over the longer term.
Detailed competition analysis for Oberoi Realty Ltd.
Key financial metrics – TTM;
| Company | Sales (₹ Cr.) | EBITDA (₹ Cr.) | EBITDA Margin (%) | PAT (₹ Cr.) | PAT Margin (%) | P/E |
| Oberoi Realty Ltd. | 6322.40 | 3571.95 | 56.50% | 2615.56 | 41.37% | 25.39 |
| The Phoenix Mills Ltd. | 4544.76 | 2714.35 | 59.72% | 1630.24 | 35.87% | 42.95 |
| Prestige Estates Projects Ltd. | 13053.20 | 3674.90 | 28.15% | 1276.20 | 9.78% | 50.30 |
| Godrej Properties Ltd. | 5203.04 | -458.21 | -8.81% | 1609.78 | 30.94% | 31.63 |
| Anant Raj Ltd. | 2550.59 | 688.41 | 26.99% | 575.14 | 22.55% | 38.67 |
Key insights on Oberoi Realty Ltd.
- Premium Mumbai Franchise: Presence in established micro-markets provides access to high-value customers and scarce development opportunities.
- 12-Project Pipeline: Management outlined a sizable FY27 launch pipeline covering premium residential, redevelopment and other strategic projects.
- NCR Diversification: Three Sixty North provides the company with an entry into the high-end Gurugram residential market.
- Land Bank Optionality: Projects across Mumbai, Thane, Alibaug and NCR provide multiple avenues for future monetisation.
- Mixed-Use Model: Residential development is complemented by commercial, retail and hospitality assets, creating a more diversified business model.
- Redevelopment Potential: Mumbai’s redevelopment cycle offers a long-term opportunity given land scarcity and ageing housing stock.
- Capital Flexibility: The company has authorised significant fundraising capacity to support its expanding project pipeline.
Recent financial performance of Oberoi Realty Ltd. for Q1 FY27
| Metric | Q1 FY26 | Q4 FY26 | Q1 FY27 | QoQ Growth (%) | YoY Growth (%) |
| Sales (₹ Cr.) | 987.55 | 1749.83 | 1300.89 | -25.66% | 31.73% |
| EBITDA (₹ Cr.) | 520.34 | 960.26 | 734.14 | -23.55% | 41.09% |
| EBITDA Margin (%) | 52.69% | 54.88% | 56.43% | 155 bps | 374 bps |
| PAT (₹ Cr.) | 414.49 | 714.29 | 539.39 | -24.49% | 30.13% |
| PAT Margin (%) | 41.97% | 40.82% | 41.46% | 64 bps | -51 bps |
| Adjusted EPS (₹) | 11.59 | 19.34 | 14.95 | -22.70% | 28.99% |
Oberoi Realty Ltd. financial update (Q1 FY27)
Financial performance
- Revenue grew 31.7% YoY to ₹1,301 crore in Q1FY27, supported by strong project execution and higher contribution from the residential portfolio.
- EBITDA grew 41.1% YoY to ₹734 crore, with EBITDA margin expanding 374 bps YoY to 56.4%, reflecting Oberoi Realty’s premium project mix and strong operating profitability.
- PAT increased 30.1% YoY to ₹539 crore, while adjusted EPS grew 29.0% YoY to ₹14.95, reflecting healthy earnings growth.
- The company’s strong execution and diversified project pipeline are expected to support sustained growth, with the sell-side report projecting 23% revenue CAGR over FY26-28E.
- Pre-sales are entering a strong growth phase, supported by new launches and the NCR foray, with estimates indicating a 43% CAGR to ₹111 billion by FY28E.
Business highlights
- Strong project pipeline: Six projects with estimated GDV of ₹305 billion were added over the last year, strengthening the medium-term growth runway.
- NCR expansion: The successful launch of Three Sixty North marks Oberoi Realty’s entry into NCR, with further land acquisitions being explored in the region.
- Diversified growth: New launches across MMR, NCR and other micro-markets are reducing dependence on its traditional markets and broadening the sales base.
- Premium positioning: Oberoi Realty continues to command premium pricing across key micro-markets, supported by strong brand equity and integrated developments.
- Annuity & hospitality growth: High occupancy across commercial assets and upcoming hotel launches provide additional recurring income and diversification beyond residential real estate.
Outlook
- Strong pre-sales growth: New launches across MMR and NCR are expected to drive pre-sales growth, with a projected 43% CAGR over FY26-28E.
- Continued business development: Management’s increased focus on project acquisitions across MMR and NCR is expected to provide multi-year growth visibility.
- Rising rental income: The annuity portfolio is expected to deliver 10% rental income CAGR over FY26-28E, supported by higher occupancy and rental escalations.
- Hospitality expansion: New Ritz-Carlton and Marriott assets are expected to drive strong hospitality growth, with further hotel projects planned beyond FY28.
- Strong balance sheet: Healthy collections and cash generation are expected to support further project acquisitions while maintaining low leverage and financial flexibility.
Recent Updates on Oberoi Realty Ltd.
- NCR Expansion: Launched Three Sixty North in Gurugram, its first-ever project outside the Mumbai Metropolitan Region.
- FY27 Pipeline: Identified 12 projects for FY27, including Oceanic at Carter Road, Fairview at Malabar Hill, Alibaug, Pedder Road and Bandra RLDA.
- Bandra Land Parcel: Capitalised its subsidiary for the ₹5,400-crore winning bid for an 11-acre railway land parcel in Bandra East.
- Hotel Horizon Acquisition: Completed the acquisition of Hotel Horizon after paying the ₹919.25-crore resolution amount.
- Malabar Hill Expansion: Executed a development agreement for land at Malabar Hill, strengthening its premium Mumbai pipeline.
Company valuation insights – Oberoi Realty Ltd.
Oberoi Realty is currently trading at an EV/EBITDA of 15x. The stock has delivered a 16.3% return over the last one year, outperforming the NIFTY 50’s -6.1% return, supported by strong project additions, improving pre-sales momentum and increasing diversification across MMR and NCR.
The investment thesis is supported by Oberoi Realty’s strong brand, premium positioning and proven execution capabilities across Mumbai’s residential market. The company has significantly accelerated business development, adding six projects with estimated GDV of ₹305 billion over the last year, while its successful entry into NCR and upcoming launches across new MMR micro-markets provide strong medium-term growth visibility. The annuity portfolio offers additional recurring cash flows, while upcoming hospitality assets provide further diversification. A strong balance sheet and low leverage provide flexibility to pursue further project acquisitions and support the next phase of scale-up.
Using a 13x FY28E EV/EBITDA multiple, we arrive at a 12-month target price of ₹2,310, implying an upside potential of 24% from current levels. The valuation reflects the company’s strong pre-sales growth potential, increasing project diversification, NCR expansion and growing contribution from annuity and hospitality assets. For the near term, we maintain a 3-month technical target of ₹1,975, implying a 6% upside potential from current levels.
Major risk factors for Oberoi Realty Ltd.
- Execution Risk: Delays in approvals, construction or project completion can defer sales and cash flows.
- Regulatory Risk: Changes in development regulations, approvals or redevelopment policies can affect project timelines and economics.
- Real Estate Cycle Risk: A slowdown in premium housing demand could impact launches, pricing and presales.
- Capital Allocation Risk: Large investments in new land parcels and expansion projects require disciplined deployment of capital.
- Geographic Expansion Risk: NCR entry introduces a new market where the company has limited operating history compared with Mumbai.
Technical analysis of Oberoi Realty Ltd. share
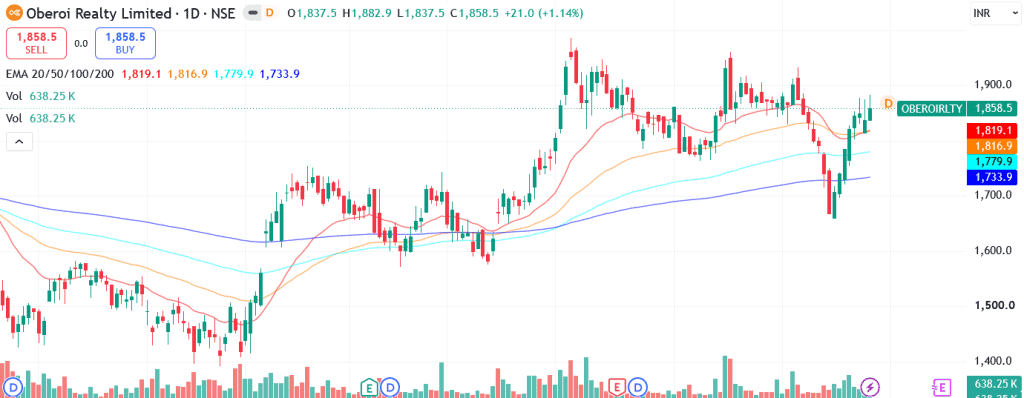
Oberoi Realty remains in a long-term uptrend, with the stock trading above all its key EMAs, indicating a positive underlying price structure. A sustained move above ₹1,975 could trigger further buying momentum and potentially pave the way towards ₹2,310, our 12-month fundamental target.
Momentum indicators are turning constructive. The MACD at -3.73 remains in negative territory but is trading above its signal line following a recent bullish crossover, indicating improving momentum. The RSI at 55.48 reflects good buying interest while remaining below overbought levels. The 21-day and 55-day Relative RSI readings of 0.04 and 0.03, respectively, indicate continued outperformance against the benchmarks.
Trend strength remains relatively subdued, with the ADX at 16.08, indicating a range-bound phase. However, the recent MACD crossover could strengthen the trend if supported by sustained price action above the key EMAs. If the stock moves above ₹1,975, it could potentially advance towards ₹2,310. On the downside, ₹1,660 remains the key support and stop-loss level.
- RSI: 55.48 (Good buying interest)
- ADX: 16.08 (Range-bound; MACD crossover could strengthen the trend)
- MACD: -3.73 (Negative; above signal line)
- Resistance: ₹1,975
- Support: ₹1,660
Oberoi Realty Ltd. stock recommendation
Current Stance: Buy, with a 3-month target price of ₹1,975 (6% upside) and a 12-month target price of ₹2,310 (24% upside), based on a valuation of 13x FY28E EV/EBITDA.

Why buy now?

Strong project pipeline: Six projects with estimated GDV of ₹305 billion added over the last year provide significant medium-term growth visibility.

NCR expansion: The successful launch of Three Sixty North marks Oberoi Realty’s entry into NCR, with further project acquisitions being explored in the region.

Strong pre-sales outlook: New launches across MMR and NCR are expected to drive strong pre-sales growth, with a projected 43% CAGR over FY26-28E.

Premium positioning: Strong brand equity and execution capabilities enable Oberoi Realty to command premium pricing across key micro-markets.

Diversified growth: Expanding annuity and hospitality portfolios provide recurring cash flows and additional growth avenues, while the balance sheet remains strong with low leverage.

Portfolio fit

Oberoi Realty offers exposure to premium residential real estate, complemented by growing annuity and hospitality businesses. Its project acquisition pipeline, NCR expansion, strong pre-sales visibility and robust balance sheet provide multiple avenues for long-term growth.
If you found this helpful and want regular stock trade calls, check out my community on StockGro here:Oberoi Realty Ltd.: Budget 2026-27 opportunities
- Urban Housing: Government focus on housing and urban development can support long-term residential demand across major cities.
- Infrastructure Development: Improved metro, road and airport connectivity can unlock value in emerging Mumbai and NCR micro-markets.
- Redevelopment Push: Policies supporting urban redevelopment can create additional opportunities for organised developers in Mumbai.
- Premium Housing: Rising disposable incomes and financialisation of household wealth can support continued premiumisation in residential real estate.
- Urban Infrastructure & Commercialisation: Expansion of business districts and infrastructure corridors can create opportunities across commercial, mixed-use and hospitality developments.
Final thoughts
Oberoi Realty stands at an inflection point, evolving from a Mumbai-focused premium developer into a broader real estate platform supported by a strong project pipeline, redevelopment opportunities and entry into the NCR market. Its premium positioning, strategic land parcels and diversified residential, commercial and hospitality portfolio provide multiple avenues for long-term growth.
For investors seeking exposure to premium housing, Mumbai redevelopment and urban real estate expansion, Oberoi Realty offers a combination of strong brand positioning, project visibility and land-bank optionality. The pace of project launches, presales, execution, cash-flow generation and capital allocation will remain key factors to monitor as the company scales its next phase of growth.