India’s digital payments ecosystem is evolving beyond basic transaction processing towards a broader financial infrastructure layer encompassing merchant payments, credit, affordability, prepaid solutions, digital commerce and embedded financial services. Increasing smartphone penetration, formalisation of businesses, UPI adoption and the rapid digitisation of SMEs are creating a structural opportunity for fintech platforms with deep merchant and financial-institution relationships.
Pine Labs is positioning itself at the centre of this opportunity by moving beyond traditional point-of-sale payments towards a diversified, full-stack commerce platform. With solutions spanning in-store and online payments, affordability, prepaid, fintech infrastructure and credit processing, the company is increasingly looking to monetise a larger share of the merchant and consumer transaction ecosystem.
But does Pine Labs Ltd. offer a compelling case for long-term investors? Let’s delve deeper.
Stock overview
| Ticker | PINELABS |
| Industry/Sector | Fintech |
| CMP | 167.56 |
| Market Cap (₹ Cr.) | 19,352 |
| P/E | 152.32 (Vs Industry P/E of 119.64) |
| 52 W High/Low | 284.00 / 134.73 |
| EPS (TTM) | 1.10 |
| Dividend Yield | 0.00% |
About Pine Labs Ltd.
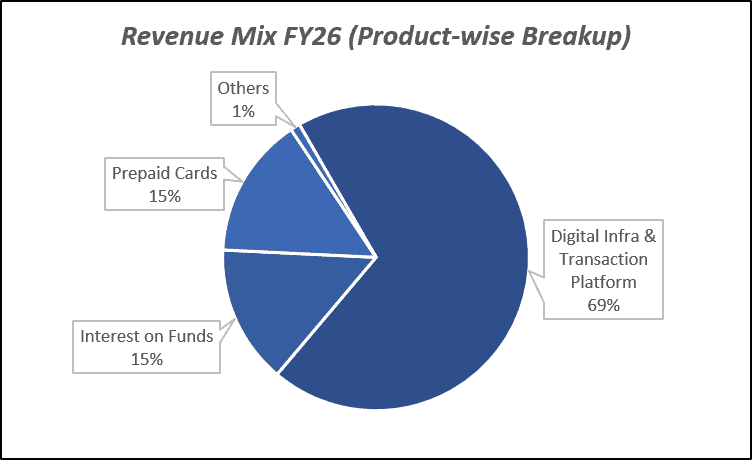
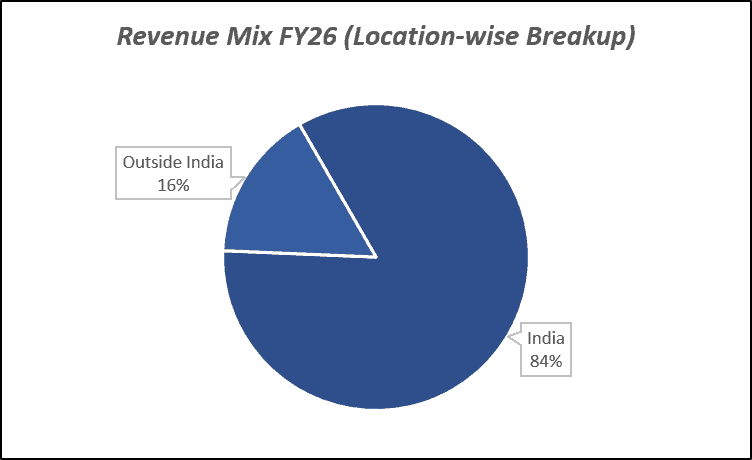
Pine Labs is a technology-led fintech company focused on digitising commerce through payment and financial technology solutions for merchants, consumer brands, enterprises and financial institutions. Founded in India in 1998, the company has evolved from a point-of-sale payments provider into a broader commerce technology platform with operations across multiple international markets.
Its platform covers online and in-store payments, affordability solutions, prepaid and gift-card infrastructure, fintech infrastructure and credit-processing capabilities. The company listed on Indian stock exchanges in November 2025, providing access to fresh capital to support growth and strengthen its balance sheet.
Key business segments
Pine Labs Ltd. operates primarily in the following key business segments:
- In-Store Payments: POS-based card, UPI, EMI and other digital payment acceptance solutions for merchants.
- Online Payments: Payment gateway, payment links, subscriptions, payouts and cross-border payment solutions.
- Affordability Solutions: Credit-card EMI, debit-card EMI, cardless EMI, BNPL and other financing options.
- Prepaid & Gift Solutions: Issuing and processing infrastructure for prepaid cards, gift cards and brand-led programmes.
- Fintech Infrastructure: Digital onboarding, bill payments, lending and other financial infrastructure solutions.
- Credit Processing: Card issuance, UPI processing and acquiring infrastructure for banks, fintechs and other institutions.
Primary growth factors for Pine Labs Ltd.
Pine Labs Ltd. key growth drivers:
- Digital Payments Penetration: Continued migration from cash to digital payments can expand transaction volumes across both online and offline commerce.
- Full-Stack Monetisation: Expansion beyond POS payments into online payments, affordability, prepaid and fintech infrastructure can increase revenue opportunities per merchant.
- International Expansion: Increasing contribution from international markets provides an additional growth engine and reduces dependence on the Indian payments market.
- Affordability & Embedded Finance: EMI, BNPL and other financing solutions can increase merchant conversion, average transaction values and consumer access to credit.
- AI & Agentic Commerce: The collaboration with Google Cloud around agentic commerce could help merchants become more discoverable and transaction-ready as AI-driven purchasing develops.
Detailed competition analysis for Pine Labs Ltd.
Key financial metrics – TTM;
| Company | Sales (₹ Cr.) | EBITDA (₹ Cr.) | EBITDA Margin (%) | PAT (₹ Cr.) | PAT Margin (%) | P/E |
| Pine Labs Ltd. | 2831.60 | 408.66 | 14.43% | 127.44 | 4.50% | 152.32 |
| One 97 Communications Ltd. | 8967.00 | 632.00 | 7.05% | 651.00 | 7.26% | 164.51 |
| PB Fintech Ltd. | 7334.31 | 614.13 | 8.37% | 753.56 | 10.27% | 60.79 |
| Avenues AI Ltd. | 9516.04 | 384.21 | 4.04% | 325.30 | 3.42% | 16.63 |
| Seshaasai Technologies Ltd. | 1506.73 | 395.41 | 26.24% | 263.60 | 17.49% | 22.46 |
Key insights on Pine Labs Ltd.
- Diversified Platform: Pine Labs has expanded from traditional POS infrastructure into online payments, prepaid, affordability and fintech infrastructure.
- Large Merchant Ecosystem: Its installed payment infrastructure provides a strong distribution base for cross-selling additional financial products.
- International Opportunity: International revenue has become an increasingly meaningful component of the business, supporting geographic diversification.
- Transaction Scale: The platform processes a large volume of digital transactions across its merchant ecosystem, creating significant operating leverage potential.
- Product Expansion: Payment gateways, payouts, subscriptions, cross-border payments and affordability solutions broaden the company’s monetisation opportunities.
- Financial Institution Relationships: Partnerships with banks and financial institutions strengthen Pine Labs’ ability to distribute payment and credit-related solutions.
- Public-Market Access: The IPO provided ₹2,080 crore of fresh capital, with proceeds partly used towards debt repayment and the remaining proceeds earmarked for stated corporate purposes.
Recent financial performance of Pine Labs Ltd. for Q1 FY27
| Metric | Q1 FY26 | Q4 FY26 | Q1 FY27 | QoQ Growth (%) | YoY Growth (%) |
| Sales (₹ Cr.) | 615.91 | 700.51 | 736.92 | 5.20% | 19.65% |
| EBITDA (₹ Cr.) | 44.71 | 106.43 | 94.89 | -10.84% | 112.23% |
| EBITDA Margin (%) | 7.26% | 15.19% | 12.88% | -231 bps | 562 bps |
| PAT (₹ Cr.) | 4.85 | 59.40 | 19.57 | -67.05% | 303.51% |
| PAT Margin (%) | 0.79% | 8.48% | 2.66% | -582 bps | 187 bps |
| Adjusted EPS (₹) | 0.11 | 0.52 | 0.17 | -67.31% | 54.55% |
Pine Labs Ltd. financial update (Q1 FY27)
Financial performance
- Revenue from operations grew 19.65% YoY to ₹736.92 crore, supported by broad-based growth across affordability, transaction processing, issuing & acquiring, and international operations. The sell-side report also highlights 5.2% QoQ growth in revenue. Pine Labs
- EBITDA increased 112.23% YoY to ₹94.89 crore, while EBITDA margin improved to 12.88%, up 562 bps YoY, reflecting strong operating leverage.
- PAT rose 303.51% YoY to ₹19.57 crore, with PAT margin improving to 2.66%, compared with 0.79% in Q1 FY26.
- Adjusted EPS increased 54.55% YoY to ₹0.17, despite sequential moderation in profitability.
- Platform activity remained healthy, with transactions increasing 14.9% YoY, fintech infrastructure transactions rising 35.9%, DCPs growing 17.9%, and merchant count increasing 16.4% YoY.
Business highlights
- DCPs grew 18% YoY to 2.17 million, while merchant count increased 16.4% YoY, reflecting continued platform expansion. Pine Labs
- Affordability & VAS GTV grew 53.5% YoY, supported by 30% growth in non-electronics affordability volumes. Pine Labs
- IAP revenue grew 31.1% YoY, led by strong 47% YoY growth in international IAP revenue. Pine Labs
- Fintech infrastructure transactions increased 37% YoY to 340 million, with 48 new clients onboarded during the quarter. Pine Labs
- Credit-on-UPI, Signal IQ, Growth Hub and AI-led payment solutions are expanding Pine Labs’ monetisation opportunities.
Outlook
- Revenue is estimated to grow at a 19.3% CAGR over FY26–30E, supported by continued expansion across Pine Labs’ diversified platform. Pine Labs
- EBITDA is projected to grow at a 36.7% CAGR over FY26–30E, supported by operating leverage and improving business mix. Pine Labs
- Margin expansion is expected as higher-margin processing services scale and recently added sales capacity becomes productive. Pine Labs
- International expansion, value-added GTV and affordability remain key drivers of Pine Labs’ medium-term growth. Pine Labs
- New initiatives such as Credit-on-UPI, Signal IQ and AI-powered payments are expected to create additional monetisation opportunities.
Recent Updates on Pine Labs Ltd.
- Google Cloud Partnership: Collaborated with Google Cloud to develop capabilities for merchants participating in emerging agentic commerce.
- International Expansion: International revenue has increased as a share of the overall business, supporting Pine Labs’ strategy of taking its fintech platform to other emerging markets.
- Agya Acquisition: Acquired the remaining 74.6% stake in Agya Technologies, making the Account Aggregator business a wholly owned subsidiary.
- IPO Capital Deployment: The company raised ₹2,080 crore through the fresh issue, with a significant portion utilised towards repayment of borrowings.
- Product Diversification: Continued expansion across online payments, affordability, prepaid, payouts and fintech infrastructure to increase platform monetisation.
- Strategic Investor Activity: Mastercard Asia Pacific was reported to be considering a block sale of part of its Pine Labs holding, representing around 4.3% of equity.
Company valuation insights – Pine Labs Ltd.
Pine Labs is currently trading at a TTM P/E of 152.3x, above the industry average of 119.6x. The stock has delivered a 9.7% return over the last six months, outperforming the NIFTY 50’s -1.3%, reflecting improving investor confidence in its growth and profitability trajectory.
The investment thesis is supported by broad-based growth across its diversified payments platform, increasing transaction volumes, international expansion and strong operating leverage. Q1FY27 revenue grew 19.6% YoY, while platform activity remained healthy, with fintech infrastructure transactions up 35.9%, DCPs up 17.9% and merchant count increasing 16.4% YoY. Affordability & VAS GTV grew 53.5% YoY, while IAP revenue increased 31.1%, led by 47% growth in international IAP revenue. The company is also expanding its addressable opportunity through Credit-on-UPI, Signal IQ, Growth Hub and AI-powered payment infrastructure. ICICI Securities expects revenue and EBITDA to grow at 19.3% and 36.7% CAGR, respectively, over FY26–30E, supported by higher-margin processing services, international expansion and operating leverage. Pine Labs Pine Labs Pine Labs
We value Pine Labs using a DCF-based approach and arrive at a 12-month target price of ₹208, implying an upside potential of 24% from current levels. While the stock trades at a premium to industry valuations, the premium needs to be viewed alongside its strong revenue growth, accelerating profitability, diversified business model, international expansion and potential for margin expansion as higher-margin processing businesses scale. For the near term, we maintain a 3-month target of ₹178, implying a 6% upside potential from current levels.
Major risk factors for Pine Labs Ltd.
- Competition Risk: Intense competition from banks, payment companies and fintech platforms can pressure pricing and market share.
- Regulatory Risk: Changes in payment, lending, data-security and fintech regulations can affect business models and economics.
- Margin Risk: Competitive pricing and transaction-related costs can limit operating-margin expansion.
- Execution Risk: Scaling multiple businesses and international operations requires sustained investment and disciplined execution.
- Technology & Cybersecurity Risk: Payment infrastructure remains exposed to system outages, cyber threats and data-security requirements.
Technical analysis of Pine Labs Ltd. share
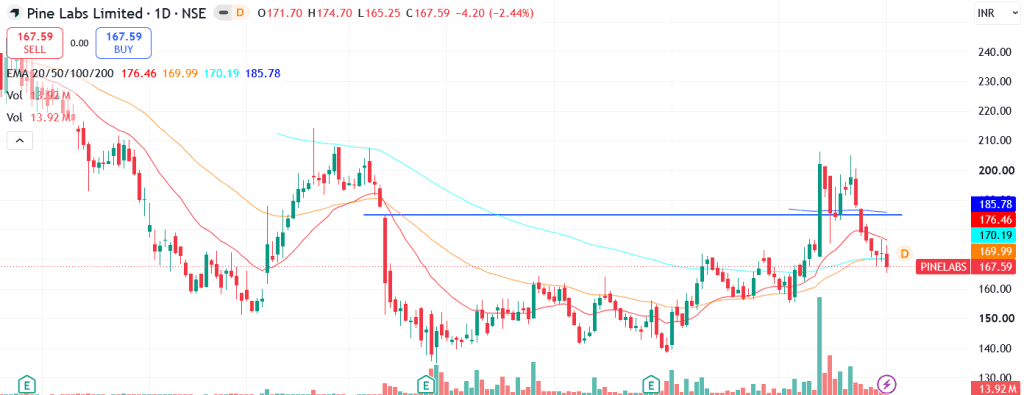
Pine Labs is forming a cup-and-handle pattern, with the cup already formed and the handle currently under development. The stock is trading above its shorter-term EMAs, indicating an improving near-term price structure. A sustained move above ₹178, the neckline/resistance level, could confirm the breakout and potentially pave the way towards ₹208, our 12-month fundamental target.
Momentum indicators remain mixed. The MACD at -2.98 remains in negative territory and is below its signal line, with a bullish crossover awaited to confirm improving momentum. The RSI at 44.27 reflects moderate buying interest while remaining below overbought levels. The 21-day and 55-day Relative RSI readings of 0.12 and 0.14, respectively, indicate outperformance against the benchmarks.
Trend strength remains moderate, with the ADX at 19.73 indicating a relatively range-bound phase. However, a completion of the handle formation followed by a breakout above the neckline could improve the overall technical setup and strengthen momentum. A sustained move above ₹178 could support a move towards ₹208. On the downside, ₹150 remains the key support and stop-loss level.
- RSI: 44.27 (Moderate buying interest)
- ADX: 19.73 (Moderate trend; breakout could strengthen momentum)
- MACD: -2.98 (Negative; below signal line, crossover awaited)
- Resistance: ₹178
- Support: ₹150
Pine Labs Ltd. stock recommendation
Current Stance: Buy, with a 3-month target price of ₹178 (6% upside) and a 12-month target price of ₹208 (24% upside), based on a DCF valuation.

Why buy now?

Broad-based growth: Q1FY27 revenue grew 19.6% YoY, with transactions up 14.9%, fintech infrastructure transactions up 35.9% and merchant count up 16.4%. Pine Labs

Strong affordability momentum: Affordability & VAS GTV grew 53.5% YoY, supported by 30% growth in non-electronics affordability volumes. Pine Labs

International expansion: IAP revenue grew 31.1% YoY, led by 47% growth in international IAP revenue, highlighting strong traction across overseas markets. Pine Labs

New growth opportunities: Credit-on-UPI, Signal IQ, Growth Hub and AI-powered payment infrastructure are creating additional monetisation opportunities across merchant and payment flows. Pine Labs

Strong earnings trajectory: Revenue and EBITDA are projected to grow at 19.3% and 36.7% CAGR, respectively, over FY26–30E, supported by operating leverage and a rising mix of higher-margin processing services.

Portfolio fit

Pine Labs provides exposure to India’s expanding digital payments ecosystem, with diversified growth across affordability, transaction processing, fintech infrastructure and international markets. Its improving profitability and emerging AI-led payment opportunities provide additional avenues for long-term growth.
If you found this helpful and want regular stock trade calls, check out my community on StockGro here:Pine Labs Ltd.: Budget 2026-27 opportunities
- Digital Payments: Continued government support for digital payments and financial inclusion can expand the addressable merchant ecosystem.
- MSME Digitisation: Formalisation and digitisation of small businesses can increase demand for payment acceptance and financial technology solutions.
- Embedded Finance: Greater adoption of digital lending, affordability and embedded financial services can expand fintech monetisation opportunities.
- Digital Infrastructure: Continued investment in India’s digital public infrastructure can support innovation across payments and financial services.
- Cross-Border Commerce: Growth in digital exports, international commerce and cross-border transactions can create opportunities for payment platforms with global capabilities.
Final thoughts
Pine Labs stands at an inflection point, evolving from a traditional payment acceptance platform into a broader digital commerce and fintech infrastructure business. With multiple revenue engines across payments, affordability, prepaid, credit processing and international markets, the company has significant scope to deepen monetisation of its existing ecosystem.
For investors seeking exposure to India’s digital payments, merchant digitisation and embedded-finance opportunity, Pine Labs offers a combination of scale, technology and product diversification. The key factors to monitor will be transaction growth, international expansion, revenue mix, operating leverage, profitability, cash generation and the company’s ability to maintain differentiation in an increasingly competitive fintech landscape.