Packaging is often overlooked in the consumer value chain, but for FMCG and pharmaceutical companies, it is a critical part of the product itself. As consumers demand convenience, hygiene, premiumisation and sustainable packaging, specialised packaging manufacturers are gaining importance.
EPL Ltd. is positioned directly within this trend. Formerly known as Essel Propack, the company is the world’s largest laminated tube manufacturer, with a global manufacturing footprint serving categories such as oral care, beauty & cosmetics, pharma & healthcare, food and home care. Its scale, customer relationships and specialised technology create meaningful entry barriers.
But does EPL Ltd. offer a compelling case for long-term investors? Let’s delve deeper.
Stock overview
| Ticker | EPL |
| Industry/Sector | Packaging |
| CMP | 248.70 |
| Market Cap (₹ Cr.) | 7,968 |
| P/E | 20.29 (Vs Industry P/E of 24.11) |
| 52 W High/Low | 274.03 / 176.40 |
| EPS (TTM) | 12.27 |
| Dividend Yield | 1.01% |
About EPL Ltd.
EPL Limited, formerly Essel Propack Limited, is a global specialty packaging company focused primarily on laminated plastic tubes. The company operates across 12 countries through 20 manufacturing facilities, with more than 5,700 employees, serving customers across oral care, beauty & cosmetics, pharma & health, food and home-care categories. Its global footprint spans the Americas, Europe, Africa, Asia and other key markets.
EPL’s core competitive advantage lies in its specialised tube-packaging technology, global scale and long-standing relationships with multinational and regional consumer brands. The company has also been investing in sustainable packaging solutions and higher-value formats, positioning itself for the evolving needs of global FMCG and healthcare customers.
Key business segments
EPL Ltd. operates primarily in the following key business segments:
- Oral Care: Laminated tubes for toothpaste and oral-care products.
- Beauty & Cosmetics: Premium packaging solutions for personal-care and cosmetic products.
- Pharma & Health: Specialised tubes for pharmaceutical and healthcare applications.
- Food: Packaging solutions for food products such as sauces and pastes.
- Home Care: Tubes and packaging solutions for household and consumer products.
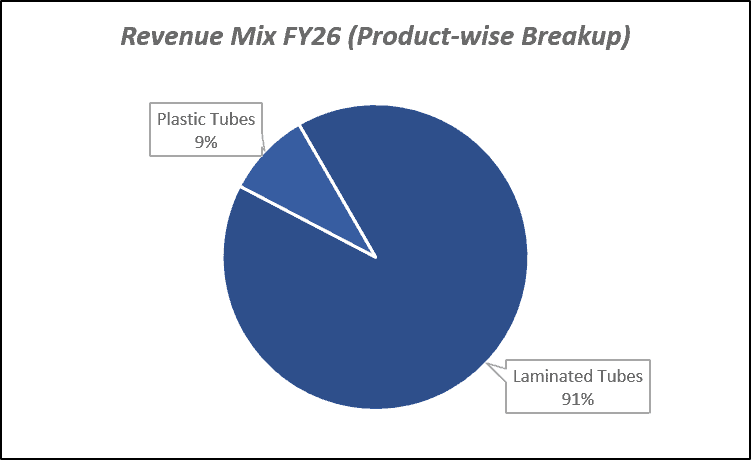
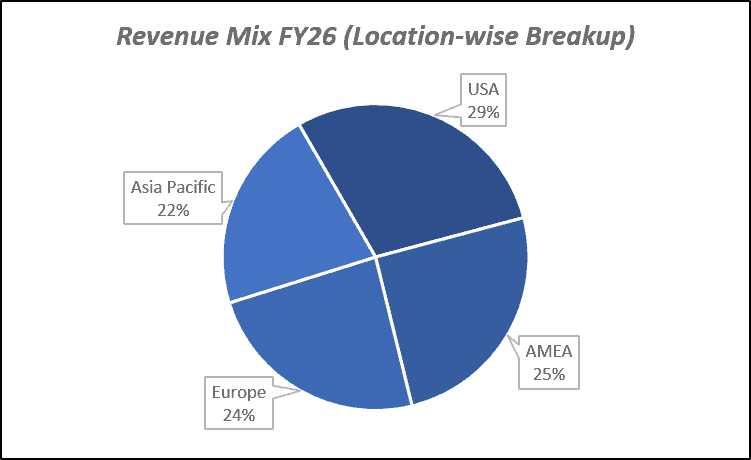
Primary growth factors for EPL Ltd.
EPL Ltd. key growth drivers:
- Premiumisation: Higher-value packaging formats can improve realisations and margins.
- Global FMCG Growth: Rising consumption supports long-term demand for specialised packaging.
- Pharma Packaging: Growing healthcare consumption creates recurring demand for tubes.
- Sustainable Packaging: Shift toward recyclable and lower-material packaging creates new opportunities.
- Capacity & Utilisation: Better utilisation of existing facilities can drive operating leverage.
Detailed competition analysis for EPL Ltd.
Key financial metrics – TTM;
| Company | Sales (₹ Cr.) | EBITDA (₹ Cr.) | EBITDA Margin (%) | PAT (₹ Cr.) | PAT Margin (%) | P/E |
| EPL Ltd. | 5043.10 | 1000.00 | 19.83% | 391.20 | 7.76% | 20.29 |
| AGI Greenpac Ltd. | 2762.93 | 627.57 | 22.71% | 362.16 | 13.11% | 13.06 |
| TCPL Packaging Ltd. | 1878.51 | 305.69 | 16.27% | 115.49 | 6.15% | 30.47 |
| Huhtamaki India Ltd. | 2610.37 | 224.60 | 8.60% | 136.40 | 5.23% | 13.85 |
| Mold-Tek Packaging Ltd. | 946.50 | 181.26 | 19.15% | 76.05 | 8.03% | 30.49 |
Key insights on EPL Ltd.
- Global scale: EPL is the world’s largest laminated tube manufacturer with approximately 8 billion tubes of annual capacity.
- Diversified footprint: Manufacturing presence across 12 countries reduces dependence on a single geography.
- Sticky customer relationships: Packaging is closely integrated into customers’ product and supply chains, creating meaningful switching costs.
- Defensive end markets: Oral care, personal care and pharmaceuticals provide relatively resilient demand.
- Premiumisation opportunity: Greater adoption of sophisticated and high-value packaging can improve product mix.
- Sustainability opportunity: Growing customer focus on environmentally responsible packaging supports innovation-led growth.
- Margin potential: Better utilisation and operational efficiencies can support gradual margin expansion.
- Global diversification: Exposure to developed and emerging markets provides multiple avenues for growth.
Recent financial performance of EPL Ltd. for Q1 FY27
| Metric | Q1 FY26 | Q4 FY26 | Q1 FY27 | QoQ Growth (%) | YoY Growth (%) |
| Sales (₹ Cr.) | 1107.90 | 1300.50 | 1387.90 | 6.72% | 25.27% |
| EBITDA (₹ Cr.) | 226.80 | 256.40 | 261.20 | 1.87% | 15.17% |
| EBITDA Margin (%) | 20.47% | 19.72% | 18.82% | -90 bps | -165 bps |
| PAT (₹ Cr.) | 101.20 | 103.40 | 98.00 | -5.22% | -3.16% |
| PAT Margin (%) | 9.13% | 7.95% | 7.06% | -89 bps | -207 bps |
| Adjusted EPS (₹) | 3.13 | 3.21 | 3.08 | -4.05% | -1.60% |
EPL Ltd. financial update (Q1 FY27)
Financial performance
- Revenue grew 25.3% YoY to ₹1,388 crore in Q1FY27, driven by broad-based growth across all geographies, with EAP leading at 34%, followed by Americas at 29%, Europe at 20% and AMESA at 17%.
- EBITDA grew 15.2% YoY to ₹261 crore, while EBITDA margin contracted 165 bps YoY to 18.8%, primarily due to margin pressure in Europe.
- Adjusted PAT declined 3.4% YoY to ₹97 crore, impacted by lower other income and a higher tax rate of 22% vs. 13.6% in Q1FY26.
- Beauty & Cosmetics (B&C) and Oral Care both delivered 20%+ growth, supported by product innovation, customer engagement and market-share gains.
- Sustainable tubes increased to 44% of total volumes from 38% in FY26, reflecting continued premiumisation and improvement in the product mix.
Business highlights
- B&C remained a key growth engine with 20%+ growth, while management aims to double its global market share from 8% to 16%.
- Thailand operations are ramping up well and are expected to become an important contributor to B&C growth.
- Europe delivered 20% revenue growth, though margins remained under pressure due to transitional costs and operational inefficiencies.
- The INDOVIDA merger is progressing as scheduled following CCI approval and is expected to expand EPL’s addressable market beyond tubes and into new geographies.
- EPL successfully passed through higher raw-material, currency and freight costs, protecting underlying profitability despite the inflationary environment.
Outlook
- Management upgraded FY27 revenue growth guidance to high-teens, supported by B&C, Oral Care and the ramp-up of Thailand operations.
- EBITDA margin guidance remains at around 20%, with management targeting double-digit PAT growth in FY27.
- Europe margins are expected to recover from the coming quarters as operating leverage and cost efficiencies take effect.
- EPL plans to expand beyond tubes into adjacent consumer packaging formats while selectively pursuing acquisitions to broaden its TAM.
- EPL continues to strengthen its sustainable packaging portfolio, with sustainable tubes gaining share and supporting premiumisation and improved product mix.
Recent Updates on EPL Ltd.
- Thailand Expansion: EPL invested in its Thailand subsidiary, supporting its Southeast Asian operations.
- Global Footprint: The company continues to operate 20 manufacturing facilities across 12 countries.
- Innovation Focus: Continued development of first-in-class materials, technologies and sustainable packaging solutions.
- Sustainability Push: Increasing focus on recyclable and environmentally conscious packaging solutions.
- Global Customer Expansion: Continued efforts to deepen relationships with FMCG, beauty and pharmaceutical customers.
Company valuation insights – EPL Ltd.
EPL is currently trading at a TTM P/E of 20.29x, below the industry average of 24.11x. The stock has delivered a 7.8% return over the last one year, significantly outperforming the Nifty 50’s -4.4% return, while strong growth across key segments and improving business momentum provide scope for further upside.
The investment thesis is supported by EPL’s strong positioning in the global consumer packaging market, with Beauty & Cosmetics (B&C) and Oral Care emerging as key growth drivers. The company is benefiting from broad-based growth across geographies, increasing market share, product innovation and a growing sustainable tube mix. The ramp-up of Thailand operations, continued expansion in high-growth markets and the planned INDOVIDA merger provide additional avenues for growth, while pricing discipline, operating leverage and cost efficiencies offer potential for margin improvement.
We value EPL at 18x FY28E EPS of ₹17.2, arriving at a 12-month target price of ₹310, implying an upside potential of 24% from current levels. While the stock has already delivered healthy returns over the past year, we believe the combination of strong segment growth, increasing contribution from B&C and Oral Care, geographical expansion and potential margin recovery provides scope for further earnings-led re-rating. For the near term, we maintain a 3-month technical target of ₹264, implying a 6% upside potential from current levels.
Major risk factors for EPL Ltd.
- Raw Material Risk: Volatility in polymers, aluminium and other packaging inputs can pressure margins.
- Global Demand Risk: Slowdown in FMCG or pharma consumption can affect volumes.
- Currency Risk: Significant international operations expose earnings to foreign-exchange movements.
- Competition: Global and regional packaging players can create pricing pressure.
- Execution Risk: Capacity expansion and new-product investments must generate adequate returns.
Technical analysis of EPL Ltd. share
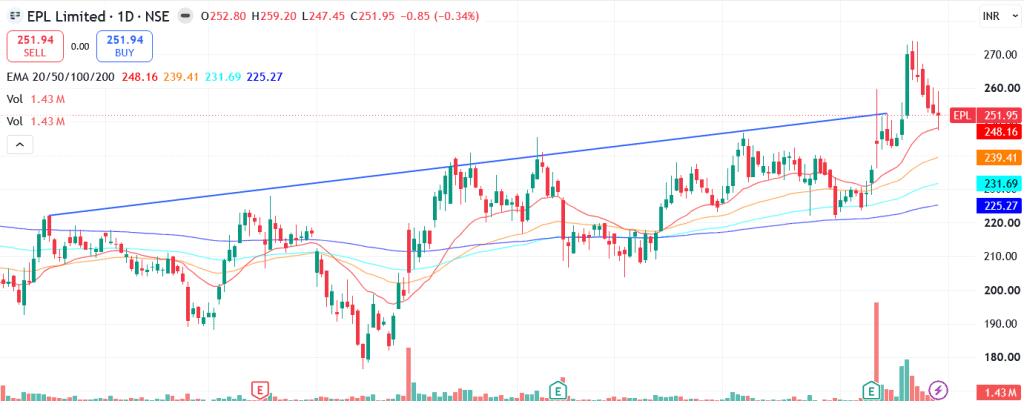
EPL is maintaining a positive uptrend, with the stock forming higher highs and trading above all its key EMAs, indicating a healthy underlying trend. A sustained move above ₹264 could trigger further buying momentum and potentially pave the way towards ₹310, our 12-month fundamental target.
Momentum indicators remain constructive. The MACD at 2.51 is in positive territory but remains below its signal line, with a bullish crossover awaited in the near term, which could provide further confirmation of the positive momentum. The RSI at 52.21 indicates good buying interest without entering overbought territory. The 21-day and 55-day Relative RSI readings of 0.14 and 0.10, respectively, also indicate strong outperformance against the benchmarks.
Trend strength remains healthy, with the ADX at 25.61, indicating a strong prevailing trend. Continued price strength above the key EMAs, supported by positive MACD momentum, could reinforce the uptrend. If the stock moves above ₹264, it could potentially advance towards ₹310. On the downside, ₹230 remains the key support and stop-loss level.
- RSI: 52.21 (Good buying interest)
- ADX: 25.61 (Strong trend)
- MACD: 2.51 (Negative; awaiting crossover)
- Resistance: ₹264
- Support: ₹230
EPL Ltd. stock recommendation
Current Stance: Buy, with a 3-month target price of ₹264 (6% upside) and a 12-month target price of ₹310 (24% upside), based on a valuation of 18x FY28E EPS of ₹17.2.

Why buy now?

Strong positioning in global consumer packaging, with Beauty & Cosmetics and Oral Care emerging as key growth engines.

FY27 revenue growth guidance has been upgraded to high-teens, supported by B&C, Oral Care and the ramp-up of Thailand operations.

B&C and Oral Care delivered 20%+ growth, supported by product innovation, customer relationships and market-share gains.

The INDOVIDA merger can expand EPL’s addressable market beyond tubes, add new packaging formats and provide access to new geographies.

Pricing discipline, operating leverage and cost efficiencies provide scope for margin recovery, particularly as European operations improve.

Portfolio fit

EPL offers exposure to the structural growth of the global consumer packaging industry, supported by its strong customer relationships, diversified geographic presence and growing exposure to high-growth segments such as Beauty & Cosmetics and Oral Care. The company’s expansion into adjacent packaging formats, increasing sustainable tube mix, Thailand ramp-up and INDOVIDA merger provide multiple avenues for long-term growth. With management focused on high-teens revenue growth, 20% EBITDA margins and improving capital efficiency, EPL offers an attractive combination of growth, diversification and potential margin expansion.
If you found this helpful and want regular stock trade calls, check out my community on StockGro here:EPL Ltd.: Budget 2026-27 opportunities
- Manufacturing Push: India’s manufacturing expansion can support domestic packaging demand.
- Pharma Growth: Healthcare and pharmaceutical expansion can increase demand for specialised packaging.
- FMCG Consumption: Rising household consumption supports long-term packaging volumes.
- Sustainability Focus: Policies promoting recyclable packaging can favour technology-led players.
- Export Manufacturing: India’s growing role in global supply chains can create additional packaging opportunities.
Final thoughts
EPL stands at an interesting point in its evolution, combining global scale, specialised packaging capabilities and exposure to resilient FMCG and healthcare end markets. Its opportunity lies in premiumisation, sustainable packaging, higher capacity utilisation and global volume growth.
For investors, EPL offers a blend of defensive consumption exposure, global diversification and operating leverage, with margins, volume growth and cash-flow generation remaining the key factors to watch.