India’s banking sector is entering a phase where quality of growth, asset quality and profitability are becoming as important as balance-sheet expansion. Within the private banking space, smaller regional banks with established customer relationships can benefit from the formalisation of MSMEs, rising retail credit penetration and increasing banking adoption across semi-urban and rural markets.
Karur Vysya Bank (KVB) stands out as a regional banking franchise that has successfully combined its long-standing presence in South India with a more technology-driven and diversified business model. The bank has strengthened its balance sheet, improved asset quality and expanded its retail, MSME and commercial banking franchise.
But does Karur Vysya Bank Ltd. offer a compelling case for long-term investors? Let’s delve deeper.
Stock overview
| Ticker | KARURVYSYA |
| Industry/Sector | Financial Services |
| CMP | 335.40 |
| Market Cap (₹ Cr.) | 32,418 |
| P/B | 2.33 |
| 52 W High/Low | 358.65 / 203.91 |
| EPS (TTM) | 28.40 |
| Dividend Yield | 0.76% |
About Karur Vysya Bank Ltd.
Karur Vysya Bank Ltd. is one of India’s longstanding private-sector banks, established in 1916 and headquartered in Karur, Tamil Nadu. Historically known for its strong relationships with traders, MSMEs and businesses in South India, the bank has progressively diversified into retail, agriculture, corporate and institutional banking while investing significantly in digital capabilities.
The bank’s transformation over recent years has focused on the three priorities of growth, profitability and asset quality. As of March 2026, total business stood at ₹2.14 lakh crore, comprising deposits of ₹1.16 lakh crore and advances of ₹98,754 crore, while net profit reached ₹2,510 crore. Net NPA stood at just 0.19%, highlighting the improvement in asset quality achieved during the transformation.
Key business segments
Karur Vysya Bank Ltd. operates primarily in the following key business segments:
- Commercial Banking: Working-capital, term loans and other financing solutions for MSMEs and businesses.
- Consumer Banking: Retail loans, deposits, personal banking and other consumer financial products.
- Agricultural Banking: Agri loans, including gold-backed agricultural lending and other farm-credit products.
- Corporate & Institutional Banking: Financing and banking solutions for larger corporations and institutions.
- Digital Banking: Digital lending, payments, deposits and technology-enabled banking services.
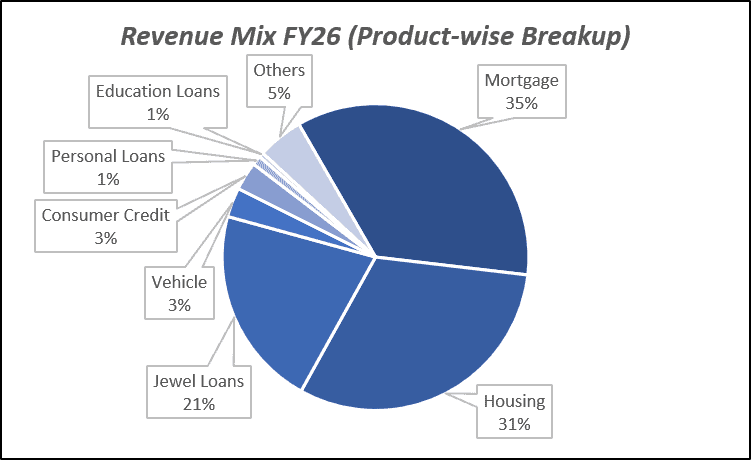
Primary growth factors for Karur Vysya Bank Ltd.
Karur Vysya Bank Ltd. key growth drivers:
- MSME Credit Growth: Strong relationships with small businesses provide a scalable lending opportunity.
- Retail Expansion: Increasing focus on consumer banking can diversify the loan book.
- Corporate Banking Rebuild: Raising the corporate loan contribution creates an additional growth avenue.
- Digital Transformation: Technology-led underwriting and customer acquisition can improve efficiency and scalability.
- Branch Expansion: Deeper penetration into semi-urban and rural markets can expand the customer base.
Detailed competition analysis for Karur Vysya Bank Ltd.
Key financial metrics – TTM;
| Company | NII (₹ Cr.) | PAT (₹ Cr.) | PAT Margin (%) | GNPA (%) | NNPA (%) | P/B |
| Karur Vysya Bank Ltd. | 5281.95 | 2744.58 | 20.13% | 0.74% | 0.19% | 2.33 |
| Ujjivan Small Finance Bank Ltd. | 4202.39 | 905.95 | 10.72% | 2.16% | 0.34% | 1.86 |
| Bandhan Bank Ltd. | 10993.03 | 1353.27 | 5.53% | 3.15% | 0.93% | 1.09 |
| City Union Bank Ltd. | 3024.68 | 1402.88 | 16.93% | 1.73% | 0.61% | 2.18 |
| RBL Bank Ltd. | 6536.59 | 899.06 | 4.80% | 1.30% | 0.37% | 1.51 |
Key insights on Karur Vysya Bank Ltd.
- Strong asset quality: Net NPA stood at 0.19% as of March 2026, reflecting disciplined underwriting and recoveries.
- Healthy balance-sheet growth: Total business grew 15% YoY to ₹2.14 lakh crore by March 2026.
- Diversified franchise: The bank operates across commercial, consumer, agricultural and corporate banking.
- Strong capital position: CRAR stood at 18.76% at March 2026, providing room for continued balance-sheet expansion.
- Digital opportunity: KVB is expanding digital underwriting, mobile banking, payments, AI and automation capabilities.
- Growth with discipline: Management continues to emphasise cautious growth while maintaining asset quality and profitability.
Recent financial performance of Karur Vysya Bank Ltd. for Q1 FY27
| Metric | Q1 FY26 | Q4 FY26 | Q1 FY27 | QoQ Growth (%) | YoY Growth (%) |
| NII (₹ Cr.) | 1079.35 | 1358.77 | 1422.75 | 4.71% | 31.82% |
| PAT (₹ Cr.) | 521.45 | 724.96 | 755.70 | 4.24% | 44.92% |
| PAT Margin (%) | 17.29% | 20.60% | 21.65% | 105 bps | 436 bps |
| GNPA (%) | 0.66% | 0.75% | 0.74% | -1 bps | 8 bps |
| NNPA (%) | 0.19% | 0.19% | 0.19% | 0 bps | 0 bps |
| Adjusted EPS (₹) | 5.40 | 7.50 | 7.82 | 4.27% | 44.81% |
Karur Vysya Bank Ltd. financial update (Q1 FY27)
Financial performance
- NII grew 31.8% YoY to ₹1,423 crore, supported by strong loan growth and sustained NIM of 4.26%.
- PAT rose 44.9% YoY to ₹756 crore, aided by strong NII growth and lower provisions.
- RoA improved to 2.11%, while RoE remained strong at over 20%, despite lower recoveries from written-off accounts.
- Asset quality remained healthy, with GNPA at 0.74% and NNPA at 0.19%; credit cost fell to a multi-quarter low of 0.4%.
- Operating efficiency improved, with cost-to-income ratio declining to 41.2% and PPOP growing 36% YoY.
Business highlights
- Gross advances grew 17% YoY and 6% QoQ, with broad-based growth across corporate, SME, retail and agriculture.
- SME and retail remained key growth engines, growing 12.8% and 23.2% YoY, respectively, while agriculture grew 20.2%.
- Gold loans continued to gain traction, growing 27% YoY and 6% QoQ, with higher yields making the segment NIM-accretive.
- Deposits grew 14.9% YoY, while CASA deposits grew 15.3% YoY, taking the CASA ratio to 27.6%.
- Capital position remained strong, with CET-1 at 17.98% and CRAR at 18.61%, providing headroom for further loan growth.
Outlook
- Management targets loan growth 100–200 bps above industry growth, while remaining selective on low-yielding corporate loans.
- NIM is expected to remain above 4% in Q2FY27, with scope for an upward revision to FY27 guidance after Q2.
- Credit costs could remain below the 1% guidance, supported by improving asset quality and healthy provisioning.
- CASA growth and premium customer acquisition should support the deposit franchise and funding profile.
- Strong loan growth, stable margins and improving asset quality provide greater visibility of sustaining 2% RoA and 18–19% RoE over FY27–28.
Recent Updates on Karur Vysya Bank Ltd.
- Branch Expansion: KVB opened 16 new branches in a single day, strengthening its physical presence.
- Corporate Banking Push: Management plans to increase the corporate loan share to around 20% from 14% over the next two years.
- Credit Card Expansion: The bank is expanding its consumer franchise through its credit-card business.
- Digital Lending: Continued rollout of end-to-end digital underwriting for retail and MSME loans.
- Senior Management Strengthening: New leadership responsibility was assigned for Corporate & Commercial Banking in July 2026.
Company valuation insights – Karur Vysya Bank Ltd.
Karur Vysya Bank is currently trading at a P/B of 2.33x, while the stock has delivered a 60% return over the last one year, significantly outperforming the NIFTY 50’s decline of 6.1%, reflecting strong investor confidence in its improving growth, profitability and asset-quality trajectory.
The investment thesis is supported by strong and broad-based loan growth, sustained NIMs, improving asset quality and robust return ratios. Gross advances grew 17% YoY, with healthy momentum across corporate, SME, retail and agriculture, while NII grew 31.8% YoY and PAT surged 44.9% YoY. The bank sustained RoA above 2% for the third consecutive quarter, even with lower recoveries from written-off accounts, highlighting the strength of its core earnings profile. Asset quality remains robust, with slippages and credit costs falling to multi-quarter lows. With loan growth targeted at 100–200 bps above industry growth, NIM expected to remain above 4% in Q2FY27, and credit costs potentially below guidance, KVB offers improving visibility of sustained ~2% RoA and strong RoE.
We value Karur Vysya Bank at 2.0x FY28E BVPS, arriving at a 12-month target price of ₹416, implying an upside potential of 24% from current levels. The valuation remains attractive considering the bank’s strong earnings trajectory, broad-based loan growth, sustained NIM, improving asset quality and robust return ratios. For the near term, we maintain a 3-month target of ₹356, implying an upside potential of 6% from current levels.
Major risk factors for Karur Vysya Bank Ltd.
- Credit Risk: Faster loan growth could eventually put pressure on asset quality.
- NIM Pressure: Competition for deposits and lower lending rates can compress margins.
- Concentration Risk: Significant exposure to MSMEs and South Indian markets remains relevant.
- Competition: Larger private banks and NBFCs can intensify competition for quality borrowers.
- Growth Execution: Rapid expansion into corporate and retail banking must maintain underwriting discipline.
Technical analysis of Karur Vysya Bank Ltd. share
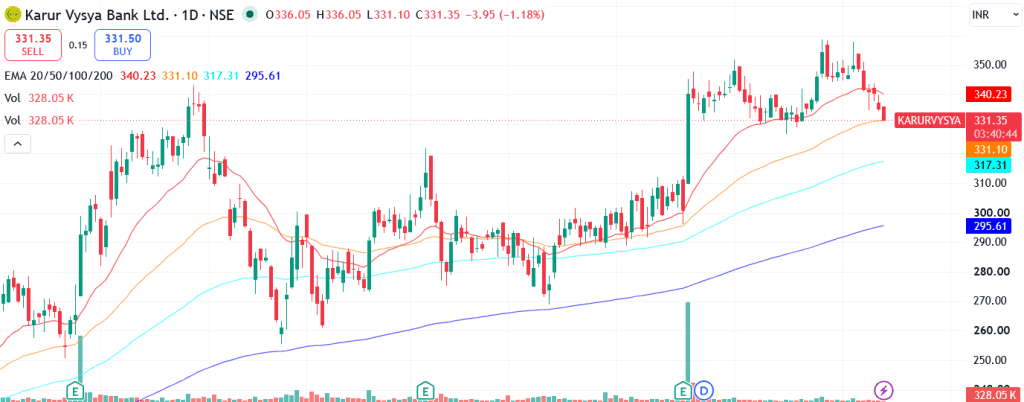
Karur Vysya Bank remains in a long-term uptrend, despite recent price weakness. The stock continues to trade above its 20-day, 50-day and 100-day EMAs, indicating that the broader trend remains intact. The recent decline appears to be a short-term consolidation within the larger uptrend. A decisive move above ₹356 could signal renewed buying momentum and pave the way towards ₹416, our 12-month fundamental target. On the downside, ₹310 remains a key support and stop-loss level.
Momentum indicators suggest that the stock is currently in a consolidation phase, with scope for momentum to improve. The MACD at 1.89 remains in positive territory but is below its signal line; a bullish crossover could strengthen the trend and trigger fresh buying interest. The RSI at 45.52 indicates decent buying interest while remaining well below overbought levels. The 21-day and 55-day Relative RSI at 0.03 and 0.16, respectively, indicate continued outperformance against the benchmark.
Trend strength remains healthy, with the ADX at 26.69 indicating that the long-term trend remains strong. A sustained move above ₹356 would reinforce the bullish setup and support a move towards ₹416. On the downside, ₹310 remains the key support for the bullish view.
- RSI: 45.52 (Decent buying interest)
- ADX: 26.69 (Strong trend)
- MACD: 1.89 (Positive; crossover awaited)
- Resistance: ₹356
- Support: ₹310
Karur Vysya Bank Ltd. stock recommendation
Current Stance: Buy, with a 3-month target price of ₹356 (6% upside) and a 12-month target price of ₹416 (24% upside), based on a valuation of 2.0x FY28E BVPS.

Why buy now?

Strong and broad-based loan growth, with advances growing 17% YoY and 6% QoQ, across SME, retail, agriculture and corporate segments.

Sustained profitability, with NII growing 31.8% YoY and PAT 44.9% YoY, while RoA remained above 2%.

Asset quality remains robust, with GNPA at 0.74%, NNPA at 0.19%, and credit costs falling to multi-quarter lows.

Strong NIM profile, with NIM at 4.26%, supported by higher-yielding segments such as gold loans, while management expects NIM to remain above 4% in Q2FY27.

Healthy deposit franchise, with deposits growing 14.9% YoY and CASA deposits 15.3% YoY, supporting funding stability and future loan growth.

Portfolio fit

Karur Vysya Bank offers exposure to India's structural credit growth through its diversified SME, retail, agriculture and corporate lending franchise, supported by strong capitalisation, improving asset quality and sustained high return ratios. With healthy loan growth, resilient NIMs, rising CASA, lower credit costs and strong operating leverage, KVB is well positioned to sustain ~2% RoA and strong RoE, supporting long-term earnings growth and shareholder value creation.
If you found this helpful and want regular stock trade calls, check out my community on StockGro here:Karur Vysya Bank Ltd.: Budget 2026-27 opportunities
- MSME Support: Policy support for small businesses can strengthen credit demand.
- Infrastructure Capex: Higher infrastructure spending can increase commercial and corporate lending opportunities.
- Rural Development: Greater rural and agricultural spending can support financial inclusion and agri-credit.
- Digital Finance: Continued digitalisation can accelerate banking penetration and reduce operating costs.
- Housing & Consumption: Rising household incomes and formalisation can support retail-credit growth.
Final thoughts
Karur Vysya Bank stands at an important inflection point, evolving from a traditional regional bank into a more diversified and technology-driven private banking franchise. With strong asset quality, rising profitability, a growing deposit base and opportunities across MSME, retail and corporate banking, the bank is positioning itself for sustainable growth.
For investors seeking exposure to India’s mid-sized private banking opportunity, KVB offers a combination of balance-sheet growth, improving profitability and strong asset quality, with loan growth, margins and credit costs remaining the key factors to watch.