India’s beauty and personal care market is moving from traditional, mass-market products toward premium, specialised and science-backed personal care, supported by rising disposable incomes, greater consumer awareness and rapid digital adoption. The shift is creating room for new-age brands that can combine strong consumer propositions with technology-led distribution and faster product innovation.
Honasa Consumer Ltd. is positioned around this structural opportunity through its house-of-brands model, with brands such as Mamaearth, The Derma Co., Aqualogica, BBlunt, Dr. Sheth’s, Staze and Luminéve. The company describes itself as a digital-first beauty and personal-care platform with an omnichannel presence across 750+ districts.
After a period of investment and business recalibration, Honasa is increasingly focused on profitable growth, stronger offline execution, hero-product scaling, product innovation and tighter category playbooks. FY26 revenue stood at ₹2,392 crore, while consolidated PAT increased to about ₹200 crore.
But does Honasa Consumer Ltd. offer a compelling case for long-term investors? Let’s delve deeper.
Stock overview
| Ticker | HONASA |
| Industry/Sector | Trading |
| CMP | 476.00 |
| Market Cap (₹ Cr.) | 15,634 |
| P/E | 60.20 (Vs Industry P/E of 56.00) |
| 52 W High/Low | 509.80 / 248.40 |
| EPS (TTM) | 7.65 |
| Dividend Yield | 0.65% |
About Honasa Consumer Ltd.
Honasa Consumer is an Indian beauty and personal-care company founded around the idea of building consumer brands around evolving Indian consumer needs. Its portfolio spans natural personal care, science-backed skincare, hair care, colour cosmetics, men’s grooming and other specialised beauty categories.
The company’s portfolio includes Mamaearth, The Derma Co., Aqualogica, BBlunt, Dr. Sheth’s, Staze Beauty and Luminéve, along with the recently acquired Reginald Men brand. Honasa combines in-house brand creation with acquisitions to build a broader portfolio rather than relying on a single flagship brand.
The company is also moving toward a more omnichannel model. Its FY26 strategy focused on rebuilding offline distribution, improving product superiority, scaling hero products, strengthening content and developing new innovation engines.
Key business segments
Honasa Consumer Ltd. operates primarily in the following key business segments:
- Skincare: Mamaearth, The Derma Co., Aqualogica, Dr. Sheth’s and Luminéve.
- Hair Care: Shampoos, conditioners, hair oils and specialised hair-care solutions.
- Baby & Personal Care: Mamaearth’s baby-care and family personal-care portfolio.
- Colour Cosmetics: Makeup and beauty products under the Mamaearth and Staze portfolio.
- Hair Styling & Salon: BBlunt products and salon services.
- Men’s Grooming: Reginald Men and related grooming products.
- Omnichannel Distribution: D2C, marketplaces, modern trade, general trade, exclusive stores and other offline channels.
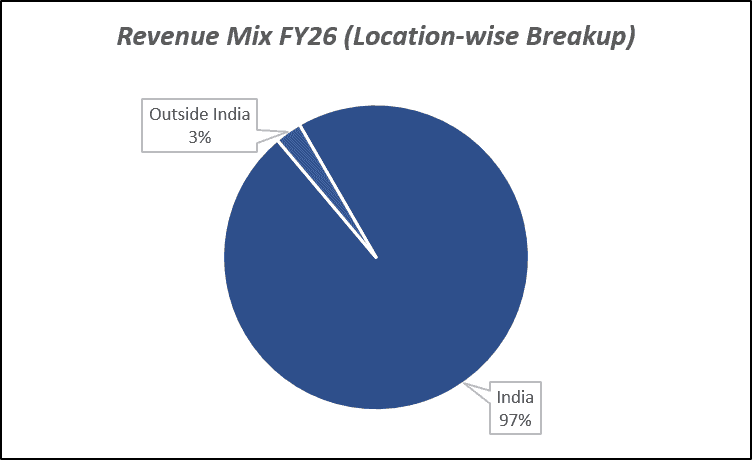
Primary growth factors for Honasa Consumer Ltd.
Honasa Consumer Ltd. key growth drivers:
- Beauty Premiumisation: Rising awareness is driving demand for premium and specialised beauty products.
- Offline Expansion: Deeper general-trade and modern-retail penetration can unlock incremental growth.
- Hero Product Scaling: Successful products can create repeat purchases and improve brand economics.
- New Brand Creation: A repeatable playbook for launching and scaling brands can create multiple growth engines.
- Innovation & Personalisation: R&D, AI-led consumer insights and personalised products can strengthen differentiation.
Detailed competition analysis for Honasa Consumer Ltd.
Key financial metrics – TTM;
| Company | Sales (₹ Cr.) | EBITDA (₹ Cr.) | EBITDA Margin (%) | PAT (₹ Cr.) | PAT Margin (%) | P/E |
| Honasa Consumer Ltd. | 2552.63 | 300.54 | 11.77% | 249.40 | 9.77% | 60.20 |
| Aegis Logistics Ltd. | 8970.66 | 1925.50 | 21.46% | 1476.11 | 16.45% | 32.16 |
| Aditya Infotech Ltd. | 4883.19 | 708.89 | 14.52% | 477.28 | 9.77% | 83.64 |
| Redington Ltd. | 128132.84 | 2536.93 | 1.98% | 1504.66 | 1.17% | 20.78 |
| Lloyds Enterprises Ltd. | 1988.42 | 181.85 | 9.15% | 235.77 | 11.86% | 36.84 |
Key insights on Honasa Consumer Ltd.
- House-of-Brands: Diverse brands enable Honasa to address multiple beauty and personal-care categories.
- Growth & Profitability: FY26 revenue grew 15.7% to ₹2,392 crore, with PAT at ₹200 crore.
- Offline Expansion: Distribution reached 120,000 outlets, with a target of 300,000+ by FY31.
- New Brand Scaling: Younger brands are gaining traction, with Reginald Men crossing ₹100 crore ARR.
- Asset-Light Model: Scalable manufacturing, innovation and diversified brands support operating leverage.
Recent financial performance of Honasa Consumer Ltd. for Q1 FY27
| Metric | Q1 FY26 | Q4 FY26 | Q1 FY27 | QoQ Growth (%) | YoY Growth (%) |
| Sales (₹ Cr.) | 595.25 | 657.08 | 755.95 | 15.05% | 27.00% |
| EBITDA (₹ Cr.) | 45.80 | 77.21 | 110.19 | 42.71% | 140.59% |
| EBITDA Margin (%) | 7.70% | 11.75% | 14.58% | 283 bps | 688 bps |
| PAT (₹ Cr.) | 41.33 | 69.56 | 90.39 | 29.95% | 118.70% |
| PAT Margin (%) | 6.94% | 10.59% | 11.96% | 137 bps | 502 bps |
| Adjusted EPS (₹) | 1.27 | 2.13 | 2.77 | 30.05% | 118.11% |
Honasa Consumer Ltd. financial update (Q1 FY27)
Financial performance
- Revenue grew 27.0% YoY to ₹756 crore, supported by strong volume-led growth and a 15.0% QoQ increase.
- EBITDA rose 140.6% YoY to ₹110 crore, with EBITDA margin improving to 14.6%, up 688 bps YoY.
- PAT increased 118.7% YoY to ₹90 crore, with PAT margin improving to 12.0%.
- Underlying volume growth stood at 30.5% YoY, indicating healthy demand momentum across key categories.
- Gross margin moderated to 69.7%, down 150 bps YoY, primarily due to a higher mix of offline and B2B channels.
Business highlights
- Mamaearth grew in the high teens, supported by strong performance in face cleansers and shampoos.
- The Derma Co. crossed ₹1,000 crore ARR, with face cleansers crossing ₹200 crore ARR and three categories above ₹200 crore ARR.
- Younger brands grew 40%+ YoY, while BTM Ventures’ Reginald Men crossed ₹150 crore ARR.
- General Trade and Modern Trade grew 40%+ YoY, taking retail reach to 3 lakh outlets, while e-commerce grew 20%+ aided by quick-commerce gains.
- Focus categories now contribute >85% of sales, while MT coverage has exceeded 90% of the relevant store universe.
Outlook
- Honasa is expected to deliver 22.9% revenue CAGR over FY26–28E, supported by continued category expansion and brand scaling.
- EBITDA is projected to grow at 39.8% CAGR, with margins expected to improve from 9.9% in FY26 to 12.8% by FY28E.
- PAT is projected to grow at 35.0% CAGR over FY26-28E, supported by operating leverage and improving profitability.
- FY27E revenue is estimated at ₹3,032 crore, with EBITDA of ₹363 crore and PAT of ₹301 crore.
- Continued expansion in offline distribution, quick commerce, focus categories and newer brands remains key to sustaining the “House of Brands” growth strategy.
Recent Updates on Honasa Consumer Ltd.
- Fluence Pharma Acquisition: Honasa announced the proposed acquisition of Fluence Pharma, expanding its presence into the pharma and dermatology-led beauty ecosystem.
- Reginald Men Integration: Reginald Men crossed ₹100 crore ARR after consolidation, strengthening Honasa’s presence in men’s grooming.
- Luminéve Launch: The company launched Luminéve, a night-focused skincare brand, adding another specialised brand to its portfolio.
- Leadership Strengthening: Honasa appointed senior leaders across product, supply chain and business functions to support its next phase of growth.
- The Derma Co. Offline Expansion: The brand expanded its offline footprint through new exclusive brand outlets, supporting its transition toward a broader omnichannel model.
Company valuation insights – Honasa Consumer Ltd.
Honasa Consumer is currently trading at a TTM P/E of 60.2x, slightly above the industry average of 56.0x. The stock has delivered a 58.4% 1-year return, outperforming the NIFTY 50’s -7.4%, reflecting strong investor expectations around its improving growth and profitability trajectory.
The investment thesis is supported by strong volume-led growth, improving profitability and the scaling of its “House of Brands” strategy. Q1FY27 revenue grew 27% YoY, while underlying volume growth stood at 30.5%. Mamaearth returned to high-teens growth, while The Derma Co. crossed ₹1,000 crore ARR, providing evidence of Honasa successfully scaling a second large brand beyond Mamaearth. Younger brands also grew 40%+, while General Trade and Modern Trade expanded 40%+, taking retail reach to 3 lakh outlets. EBITDA grew 2.5x YoY, with margins expanding to 14.6%, supported by favourable channel and brand mix, operating leverage and lower overhead intensity. ICICI Securities expects revenue, EBITDA and PAT to grow at 22.9%, 39.8% and 35.0% CAGR, respectively, over FY26–28E.
We value Honasa Consumer at 54x FY28E EPS of ₹11, arriving at a 12-month target price of ₹594, implying an upside potential of 24% from current levels. While the stock trades at a modest premium to industry valuations, the premium is supported by its improving growth profile, expanding margins, successful scaling of newer brands, increasing offline distribution and continued momentum in focus categories. For the near term, we maintain a 3-month target of ₹505, implying a 6% upside potential from current levels.
Major risk factors for Honasa Consumer Ltd.
- Brand Risk: Weak consumer traction can impact growth and market share.
- Competition: Intense FMCG and D2C competition can pressure pricing and marketing spends.
- Marketing Risk: High customer-acquisition costs can constrain margin expansion.
- Execution Risk: Rapid offline expansion and multiple brand launches increase complexity.
- Consumer Risk: Changing beauty trends can shorten product life cycles and impact demand.
Technical analysis of Honasa Consumer Ltd. share
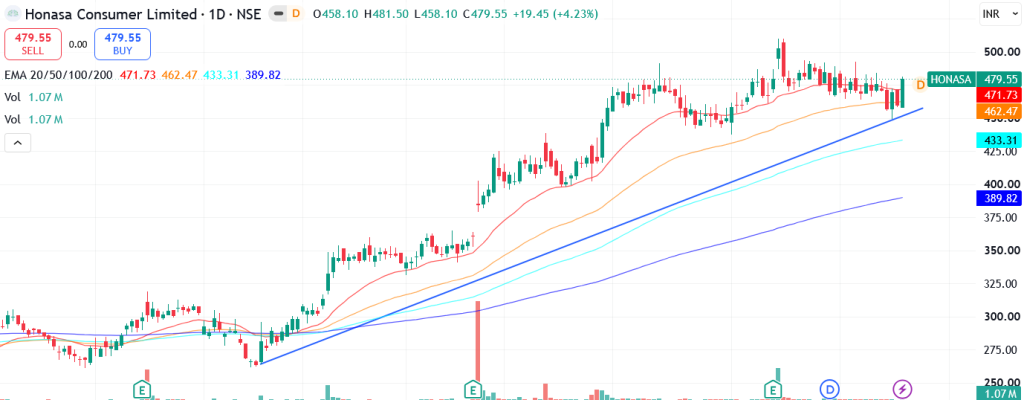
Honasa Consumer is in a long-term uptrend, with the stock trading above all its key EMAs, indicating a positive underlying price structure. A sustained move above ₹505 could trigger further buying momentum and potentially pave the way towards ₹594, our 12-month fundamental target.
Momentum indicators remain constructive. The MACD at -0.19 remains in negative territory and is currently below its signal line, with a bullish crossover awaited to confirm improving momentum. The RSI at 53.89 reflects good buying interest while remaining below overbought levels. The 21-day and 55-day Relative RSI readings of 0.04 and 0.06, respectively, indicate outperformance against the benchmark.
Trend strength remains moderate, with the ADX at 14.40 indicating a range-bound phase. However, a positive MACD crossover could strengthen the trend going forward. A sustained move above ₹505 could support a move towards ₹594. On the downside, ₹435 remains the key support and stop-loss level.
- RSI: 53.89 (Good buying interest)
- ADX: 14.40 (Range-bound; MACD crossover could strengthen the trend)
- MACD: -0.19 (Negative; below signal line, crossover awaited)
- Resistance: ₹505
- Support: ₹435
Honasa Consumer Ltd. stock recommendation
Current Stance: Buy, with a 3-month target price of ₹505 (6% upside) and a 12-month target price of ₹594 (24% upside), based on a valuation of 54x FY28E EPS of ₹11.

Why buy now?

Strong volume-led growth, with Q1FY27 revenue growing 27% YoY and underlying volume growth of 30.5%, supported by healthy demand across key categories.

House of Brands gained scale, with Mamaearth growing in the high teens and The Derma Co. crossing ₹1,000 crore ARR, demonstrating progress in scaling brands beyond Mamaearth.

Strong distribution expansion, with General Trade and Modern Trade growing 40%+ YoY and retail reach expanding to 3 lakh outlets, while e-commerce grew 20%+.

Younger brands gaining traction, growing 40%+ YoY, with Reginald Men crossing ₹150 crore ARR and expanding through new markets and quick-commerce channels.

Strong profitability improvement, with EBITDA growing 2.5x YoY and margins expanding to 14.6%; revenue, EBITDA and PAT are projected to grow at 22.9%, 39.8% and 35.0% CAGR, respectively, over FY26-28E.

Portfolio fit

Honasa Consumer offers exposure to the structural growth of India’s beauty and personal care market, supported by its House of Brands strategy, expanding distribution and strong volume growth. The scaling of Mamaearth, The Derma Co. and younger brands provides multiple growth avenues, while increasing offline reach and quick-commerce penetration can further support brand discovery and sales. With improving EBITDA margins, strong earnings growth and disciplined capital deployment, the company offers a combination of growth, operating leverage and expanding profitability.
If you found this helpful and want regular stock trade calls, check out my community on StockGro here:Honasa Consumer Ltd.: Budget 2026-27 opportunities
- Rising Consumption: Higher disposable incomes can support discretionary beauty and personal-care spending.
- Premiumisation: Growth in premium skincare, haircare and specialised products can improve category value.
- Digital Commerce: Continued e-commerce and quick-commerce penetration can accelerate product discovery and trial.
- MSME & Manufacturing Support: A favourable domestic manufacturing ecosystem can support India’s consumer-brand expansion.
- Tier-II & Tier-III Growth: Rising digital adoption and organised retail penetration can expand Honasa’s addressable market beyond major cities.
Final thoughts
Honasa Consumer stands at an important inflection point, evolving from a digital-first beauty company into a broader omnichannel house of brands. Its expanding portfolio, growing offline presence, newer brand engines and improving profitability provide multiple avenues for long-term growth.
For investors seeking exposure to India’s premiumisation and organised beauty & personal-care opportunity, Honasa offers a combination of category growth, brand creation, distribution expansion and operating leverage. Sustaining brand momentum, improving offline productivity, controlling customer-acquisition costs and converting higher profitability into cash flow will remain the key factors to monitor.