India’s investment landscape is undergoing a structural shift from traditional savings toward financial assets, supported by rising incomes, greater financial awareness, SIP penetration and increasing participation from retail investors. This transition is creating a long-term opportunity for asset managers with strong brands, distribution networks and established investment capabilities.
ICICI Prudential Asset Management Company is positioned at the centre of this trend. The company is one of India’s largest asset managers, with ₹11.05 trillion in mutual fund QAAUM and a 13.5% market share as of March 2026. Its franchise is supported by 17 million unique customers, more than 1.14 lakh distributor partners and 280 offices.
But does ICICI Prudential AMC Ltd. offer a compelling case for long-term investors? Let’s delve deeper.
Stock overview
| Ticker | ICICIAMC |
| Industry/Sector | Asset Management |
| CMP | 3274.70 |
| Market Cap (₹ Cr.) | 1,58,494 |
| P/E | 43.92 (Vs Industry P/E of 22.75) |
| 52 W High/Low | 3611.00 / 2530.00 |
| EPS (TTM) | 70.52 |
| Dividend Yield | 3.30% |
About ICICI Prudential AMC Ltd.
ICICI Prudential AMC is an asset management company promoted by ICICI Bank and Prudential Corporation Holdings. With more than three decades of operating history, the company manages mutual fund schemes across equity, debt, hybrid and other asset classes while also operating businesses across PMS, AIFs and advisory.
As of March 2026, the company had ₹11.05 trillion of MF QAAUM, including ₹6.20 trillion in equity schemes and ₹9.21 trillion in active MF QAAUM. It held a 13.7% market share in active MF QAAUM, 14.2% in equity schemes and 26.7% in equity-oriented hybrid schemes.
The business also has a strong individual-investor franchise, with individual MAAUM of ₹6.86 trillion, while its alternatives business had QAAUM of approximately ₹730 billion.
Key business segments
ICICI Prudential AMC Ltd. operates primarily in the following key business segments:
- Mutual Funds: Equity, debt, hybrid and solution-oriented investment products.
- Alternatives: PMS, AIFs and alternative investment strategies for sophisticated investors.
- Advisory: Investment advisory and customised portfolio solutions.
- Distribution: Direct, digital, banks, distributors and national distribution channels.
- Institutional Business: Investment solutions for institutions and large investors.
- GIFT City & Global: International investment and distribution opportunities through GIFT City and DIFC.
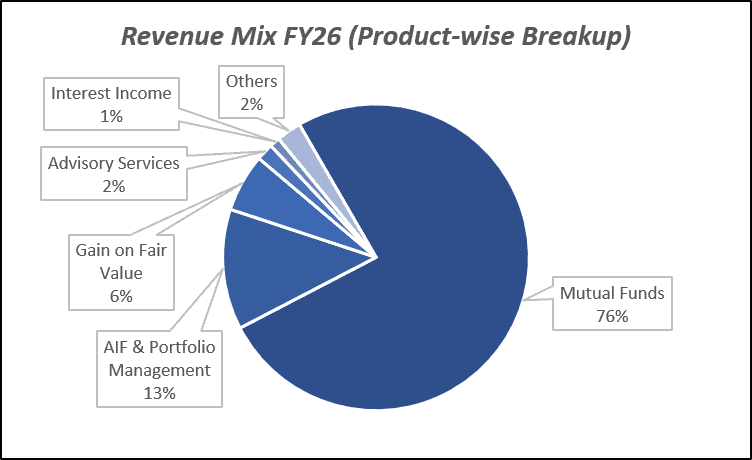
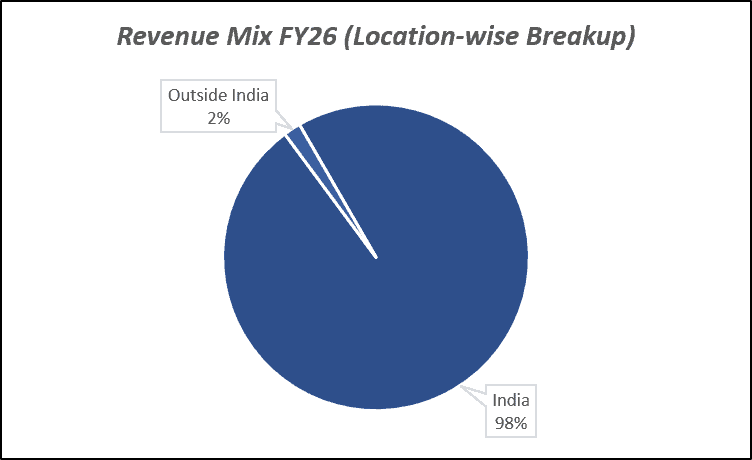
Primary growth factors for ICICI Prudential AMC Ltd.
ICICI Prudential AMC Ltd. key growth drivers:
- Financialisation of Savings: Rising household participation in mutual funds and market-linked products supports structural AUM growth.
- Retail & SIP Penetration: Growing retail investors and systematic investments can create more stable, recurring AUM.
- Equity Market Participation: Increasing equity ownership provides scope for faster growth in higher-yielding equity assets.
- Alternatives Expansion: PMS, AIFs and specialised strategies can diversify revenue and increase wallet share among HNIs.
- Distribution & Technology: A pan-India network and digital capabilities can accelerate customer acquisition beyond major cities.
Detailed competition analysis for ICICI Prudential AMC Ltd.
Key financial metrics – TTM;
| Company | Sales (₹ Cr.) | EBITDA (₹ Cr.) | EBITDA Margin (%) | PAT (₹ Cr.) | PAT Margin (%) | P/E |
| ICICI Prudential AMC Ltd. | 5764.63 | 4293.83 | 74.49% | 3298.26 | 57.22% | 43.92 |
| UTI Asset Management Ltd. | 1909.47 | 850.02 | 44.52% | 512.43 | 26.84% | 22.51 |
| HDFC Asset Management Ltd. | 4253.73 | 3372.74 | 79.29% | 2947.64 | 69.30% | 34.69 |
| Nippon Life India AMC Ltd. | 2869.00 | 1914.59 | 66.73% | 1635.54 | 57.01% | 43.71 |
| Aditya Birla Sun Life AMC Ltd. | 1860.59 | 1096.32 | 58.92% | 1007.44 | 54.15% | 31.32 |
Key insights on ICICI Prudential AMC Ltd.
- Strong Market Position: ₹11.05 trillion MF QAAUM with a 13.5% market share as of March 2026.
- Equity Leadership: Equity QAAUM reached ₹6.20 trillion with a 14.2% market share.
- Retail-Led Franchise: Individual MAAUM stood at ₹6.86 trillion, accounting for a significant portion of the franchise.
- Strong Profitability: FY26 revenue grew 23.1% and PAT increased 24.4% to ₹3,298 crore.
- Operating Leverage: Operating margin improved to 37.6% in FY26 as expenses grew slower than revenue.
Recent financial performance of ICICI Prudential AMC Ltd. for Q1 FY27
| Metric | Q1 FY26 | Q4 FY26 | Q1 FY27 | QoQ Growth (%) | YoY Growth (%) |
| Sales (₹ Cr.) | 1330.67 | 1517.01 | 1564.22 | 3.11% | 17.55% |
| EBITDA (₹ Cr.) | 945.59 | 1160.07 | 1132.65 | -2.36% | 19.78% |
| EBITDA Margin (%) | 71.06% | 76.47% | 72.41% | -406 bps | 135 bps |
| PAT (₹ Cr.) | 783.64 | 763.42 | 964.63 | 26.36% | 23.10% |
| PAT Margin (%) | 58.89% | 50.32% | 61.67% | 1135 bps | 278 bps |
| Adjusted EPS (₹) | 39.47 | 15.44 | 19.52 | 26.42% | -50.54% |
ICICI Prudential AMC Ltd. financial update (Q1 FY27)
Financial performance
- Revenue grew 17.55% YoY to ₹1,564 crore, supported by strong AUM growth.
- EBITDA rose 19.78% YoY to ₹1,133 crore, with margin at 72.4% despite higher employee costs.
- PAT increased 23.10% YoY to ₹965 crore, with PAT margin improving to 61.67%.
- MF QAAUM grew 18% YoY to ₹11.1 lakh crore, while market share remained at 13.4%.
- Revenue yield remained stable at 56.3 bps, despite gradual industry-wide yield moderation.
Business highlights
- Equity mix remained stable at 53%, supporting the overall revenue profile.
- SIP flows remained broadly in line with industry trends despite softer June monthly flows.
- Added 7 of every 10 new industry customers, taking total unique customers to 17.3 million.
- Multiple products are in the pipeline, including Life Cycle, Contra, SIF and Commercial Real Estate Funds.
- Management expects no material impact from TER regulation changes, while strong distribution and investment performance remain key strengths.
Outlook
- Revenue is expected to grow around 16% in FY27, supported by continued AUM growth.
- EBITDA margins are expected to gradually improve, reaching 74% by FY29.
- PAT is projected to grow 15-17% over FY27-29, supported by AUM growth and operating leverage.
- AAAUM is projected to rise from ₹10.35 lakh crore in FY26 to ₹17.14 lakh crore by FY29.
- New product launches, strong distribution and rising financialisation of savings remain key long-term growth drivers.
Recent Updates on ICICI Prudential AMC Ltd.
- PMS Expansion: Approved acquisition of ICICI Securities’ PMS business with ₹2,910 crore of AUM as of March 2026, subject to regulatory approvals.
- Bank Investment Approval: RBI approved the AMC and ICICI Group entities to acquire up to 9.95% stakes in four banks, including Kotak Mahindra Bank.
- Promoter Stake Sale: Prudential proposed selling up to 2% stake to comply with minimum public-shareholding requirements, reducing promoter holding to 85.6%.
- Alternatives Expansion: PMS and AIF assets have grown substantially over the past five years, strengthening the company’s non-MF franchise.
- Technology & AI: Continued investments in digital capabilities and AI are being used to improve customer acquisition, servicing and operating efficiency.
Company valuation insights – ICICI Prudential AMC Ltd.
ICICI Prudential AMC is currently trading at a TTM P/E of 43.9x, significantly above the industry average of 22.8x. The stock has delivered a 24.4% YTD return, outperforming the NIFTY 50’s -10.7%, reflecting strong investor confidence in the company’s growth prospects and market position.
The investment thesis is supported by strong AUM growth, a leading market position, robust distribution and high profitability. MF QAAUM grew 18% YoY to ₹11.1 lakh crore, while the company maintained a healthy 13.4% market share. Its strong brand and distribution helped it add 7 of every 10 new customers in the industry, taking its unique customer base to 17.3 million. The expanding product pipeline across Life Cycle Funds, Contra Funds, SIF and Commercial Real Estate Funds provides additional growth avenues, while sustained financialisation of savings and healthy investment performance should support long-term AUM growth. Emkay expects revenue and PAT to grow at 16% and 15-17%, respectively, over the coming years, with EBITDA margins gradually improving towards 74%.
We value ICICI Prudential AMC at 42x FY28E EPS of ₹97, arriving at a 12-month target price of ₹4,074, implying an upside potential of 24% from current levels. While the stock trades at a premium to industry valuations, we believe the premium is supported by its strong market position, high profitability, expanding AUM, robust distribution franchise and long-term structural growth opportunities. For the near term, we maintain a 3-month technical target of ₹3,480, implying a 6% upside potential from current levels.
Major risk factors for ICICI Prudential AMC Ltd.
- Market Risk: Equity corrections can reduce AUM and fee income.
- Fee Compression: Lower TERs and pricing pressure can impact revenue yields.
- Competition: Passive funds and competing AMCs can pressure market share.
- Performance Risk: Scheme underperformance can affect investor flows and AUM growth.
- Regulatory Risk: Changes in AMC regulations and fee structures can impact profitability.
Technical analysis of ICICI Prudential AMC Ltd. share
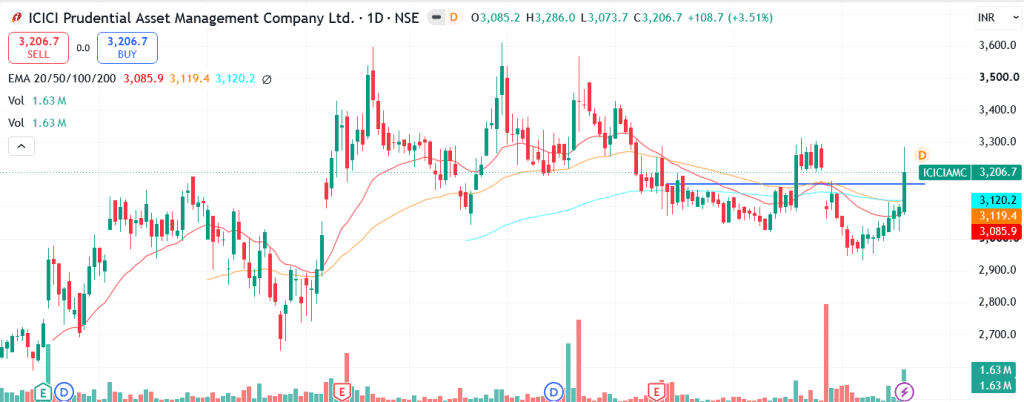
ICICI Prudential AMC is showing a rounding bottom pattern, with the stock breaking above the neckline and trading above all its key EMAs, indicating improving price structure. A sustained move above ₹3,480 could trigger further buying momentum and potentially pave the way towards ₹4,074, our 12-month fundamental target.
Momentum indicators are turning constructive. The MACD at -8.89 remains in negative territory but is trading above its signal line following a recent bullish crossover, indicating improving momentum. The RSI at 61.22 reflects good buying interest while remaining below overbought levels. The 21-day and 55-day Relative RSI readings of 0.01 each indicate outperformance against the respective benchmarks.
Trend strength remains moderate, with the ADX at 17.53 indicating a range-bound phase. However, the rounding bottom breakout, improving MACD setup and strong price position above key EMAs could strengthen the trend going forward. A sustained move above ₹3,480 could support a move towards ₹4,074. On the downside, ₹3,010 remains the key support and stop-loss level.
- RSI: 61.22 (Good buying interest)
- ADX: 17.53 (Range-bound; technicals improving)
- MACD: -8.89 (Negative; above signal line after recent crossover)
- Resistance: ₹3,480
- Support: ₹3,010
ICICI Prudential AMC Ltd. stock recommendation
Current Stance: Buy, with a 3-month target price of ₹3,480 (6% upside) and a 12-month target price of ₹4,074 (24% upside), based on a valuation of 42x FY28E EPS of ₹97.

Why buy now?

Strong market position with ₹11.1 lakh crore MF QAAUM and a stable 13.4% market share, supported by a strong brand and distribution network.

AUM growth remains healthy, with MF QAAUM rising 18% YoY, while increasing financialisation of savings provides a structural growth opportunity.

Strong customer acquisition, with ICICI AMC adding 7 of every 10 new industry customers and reaching 17.3 million unique customers.

Multiple products in the pipeline, including Life Cycle Funds, Contra Funds, SIF and Commercial Real Estate Funds, creating additional growth avenues.

Strong profitability and operating leverage, with PAT expected to grow 15-17% over FY27-29 and EBITDA margins projected to improve towards 74%.

Portfolio fit

ICICI Prudential AMC offers exposure to the structural growth of India’s asset management industry, supported by its strong brand, leading market position, extensive distribution network and growing customer base. Rising financialisation of savings, continued SIP adoption and an expanding product portfolio provide multiple avenues for long-term AUM growth. With high profitability, strong cash generation and improving operating leverage, the company offers a combination of structural growth, earnings visibility and sustained shareholder returns.
If you found this helpful and want regular stock trade calls, check out my community on StockGro here:ICICI Prudential AMC Ltd.: Budget 2026-27 opportunities
- Financialisation of Savings: Policy support for financial inclusion can accelerate migration from physical to financial assets.
- Retail Participation: Rising household incomes and investor awareness can support mutual fund penetration.
- Capital Market Deepening: Greater participation in equities and capital markets can expand the addressable AUM pool.
- Digital Financial Inclusion: Digital investing can improve penetration across Tier-II, Tier-III and emerging markets.
- Alternative Investments: Rising HNI and affluent wealth can support growth in PMS, AIFs and specialised investment solutions.
Final thoughts
ICICI Prudential AMC stands at an important point in India’s financialisation cycle, with a strong mutual fund franchise, leading equity and hybrid market positions, a large individual-investor base and expanding alternatives platform. Its asset-light model, high profitability and operating leverage provide a strong foundation for long-term earnings compounding.
For investors seeking exposure to India’s structural shift toward financial assets, the company offers a combination of AUM growth, equity-market participation, retail penetration and scalable profitability. Market volatility, fee compression, regulatory changes and investment performance remain key factors to monitor as the company expands beyond its core mutual fund franchise.