India’s banking landscape is undergoing a structural shift, with smaller financial institutions increasingly moving beyond their traditional customer segments and building diversified retail banking franchises. Ujjivan Small Finance Bank is one such player, transitioning from a predominantly microfinance-led institution toward a broader bank with increasing exposure to secured retail lending, MSME, housing, vehicle finance and gold loans.
The bank has entered FY27 with strong operating momentum. Its gross loan book grew 28.9% YoY to ₹42,903 crore in Q1 FY27, while deposits increased 24.6% to ₹48,129 crore. Importantly, the secured portfolio crossed 50% of the loan book, reflecting the ongoing diversification of the franchise. At the same time, asset quality improved, with GNPA and NNPA declining to 2.17% and 0.34%, respectively.
But does Ujjivan Small Finance Bank Ltd. offer a compelling case for long-term investors? Let’s delve deeper.
Stock overview
| Ticker | UJJIVANSFB |
| Industry/Sector | Financial Services |
| CMP | 63.99 |
| Market Cap (₹ Cr.) | 12,481 |
| P/B | 1.88 |
| 52 W High/Low | 73.94 / 43.85 |
| EPS (TTM) | 4.65 |
| Dividend Yield | 0.00% |
About Ujjivan Small Finance Bank Ltd.
Ujjivan Small Finance Bank is a Bengaluru-based small finance bank that evolved from the Ujjivan financial-services franchise, with a strong heritage in serving underserved and underbanked customers. Its traditional strength has been micro-banking, but the bank has progressively diversified into housing finance, MSME lending, vehicle finance, gold loans and other retail banking products.
The bank is increasingly focused on building a balanced asset and liability franchise. In FY26, its secured book grew 43.5% and reached 49.4% of the gross loan book, while deposits grew 21.4%. By Q1 FY27, the secured share had crossed 50%.
A major strategic opportunity is its application to transition from a Small Finance Bank to a Universal Bank, which could eventually broaden its product flexibility and addressable market if approved.
Key business segments
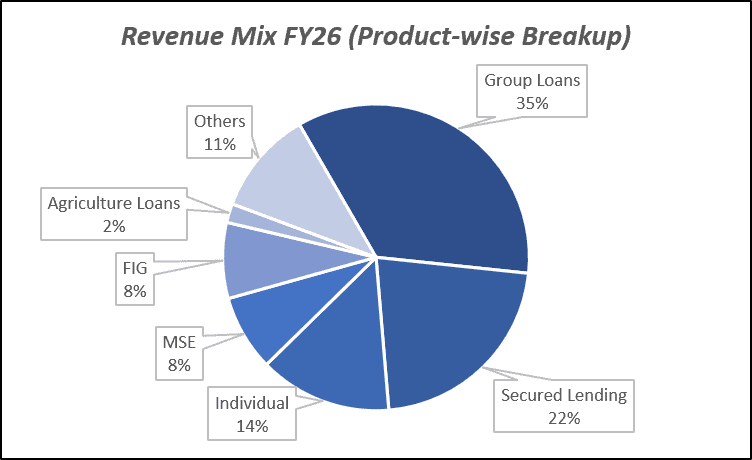
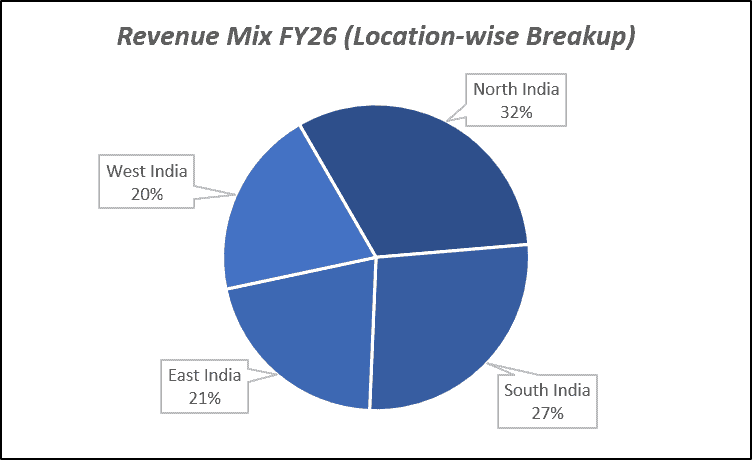
Ujjivan Small Finance Bank Ltd. operates primarily in the following key business segments:
- Micro Banking: Group and individual lending to financially underserved customers.
- Housing Finance: Affordable housing and micro-mortgage loans.
- MSME Banking: Lending to small businesses and entrepreneurs.
- Vehicle Finance: Financing for commercial and personal vehicles.
- Gold Loans: Newer secured lending segment with rapid portfolio build-up.
- Deposits & Retail Banking: CASA, retail term deposits and transaction banking.
- Fee-Based Services: Insurance, mutual fund distribution, cards and other cross-selling opportunities.
Primary growth factors for Ujjivan Small Finance Bank Ltd.
Ujjivan Small Finance Bank Ltd. key growth drivers:
- Secured Portfolio Expansion: Faster growth in housing, MSME, vehicle and gold loans can reduce dependence on microfinance.
- Deposit Franchise: Rising CASA and retail deposits can lower funding costs and support sustainable balance-sheet growth.
- Branch Expansion: Increasing branch density can deepen customer acquisition and cross-selling opportunities.
- New Product Engines: Gold loans, vehicle finance, MSME and credit cards provide additional avenues for growth.
- Operating Leverage: Higher loan volumes combined with improving cost efficiency can support stronger profitability.
Detailed competition analysis for Ujjivan Small Finance Bank Ltd.
Key financial metrics – TTM;
| Company | NII (₹ Cr.) | PAT (₹ Cr.) | PAT Margin (%) | GNPA (%) | NNPA (%) | P/B |
| Ujjivan Small Finance Bank Ltd. | 4202.39 | 905.95 | 10.72% | 2.16% | 0.34% | 1.88 |
| Equitas Small Finance Bank Ltd. | 3635.01 | 510.45 | 6.27% | 2.42% | 0.71% | 1.38 |
| Bandhan Bank Ltd. | 10993.03 | 1353.27 | 5.53% | 3.15% | 0.93% | 1.10 |
| Karur Vysya Bank Ltd. | 5281.95 | 2744.58 | 20.13% | 0.74% | 0.19% | 2.29 |
| RBL Bank Ltd. | 6536.59 | 899.06 | 4.80% | 1.30% | 0.37% | 1.46 |
Key insights on Ujjivan Small Finance Bank Ltd.
- Business Diversification: Secured loans crossed 50% of the gross loan book, reducing reliance on microfinance.
- Strong Growth: Loan book and deposits grew 28.9% and 24.6% YoY, respectively, in Q1 FY27.
- Improving Asset Quality: GNPA & NNPA improved to 2.16% & 0.34%, supported by better collections.
- Strong Profitability: RoA of 2.2% and RoE of 18.2% reflect improving return ratios.
- New Growth Engines: Gold and vehicle finance crossed ₹1,000 crore, supporting portfolio diversification.
Recent financial performance of Ujjivan Small Finance Bank Ltd. for Q1 FY27
| Metric | Q1 FY26 | Q4 FY26 | Q1 FY27 | QoQ Growth (%) | YoY Growth (%) |
| NII (₹ Cr.) | 855.95 | 1092.89 | 1187.35 | 8.64% | 38.72% |
| PAT (₹ Cr.) | 103.22 | 281.97 | 316.54 | 12.26% | 206.67% |
| PAT Margin (%) | 5.53% | 12.90% | 13.88% | 98 bps | 835 bps |
| GNPA (%) | 2.52% | 2.26% | 2.16% | -10 bps | -36 bps |
| NNPA (%) | 0.70% | 0.43% | 0.34% | -9 bps | -36 bps |
| Adjusted EPS (₹) | 0.53 | 1.45 | 1.63 | 12.41% | 207.55% |
Ujjivan Small Finance Bank Ltd. financial update (Q1 FY27)
Financial performance
- Net Interest Income (NII) grew 38.72% YoY and 8.64% QoQ to ₹1,187 crore, marking the bank’s highest-ever NII, supported by strong loan growth and stable margins.
- Profit After Tax (PAT) surged 206.67% YoY and 12.26% QoQ to ₹317 crore, aided by strong operating performance and a sharp moderation in provisions and credit costs.
- Profitability strengthened significantly, with RoA improving to 2.2% and RoE to 18.2%, supported by operating leverage and lower credit costs.
- Asset quality continued to improve, with GNPA declining to 2.16% from 2.26% QoQ and NNPA to 0.34% from 0.43%, while PCR improved to 85%.
- NIM remained stable at 8.5%, as lower cost of funds offset the 10 bps QoQ decline in asset yields, while the cost-to-income ratio improved to 62% from 63.2% QoQ.
Business highlights
- Advances grew 29% YoY to ₹41,980 crore, with Q1 disbursements rising over 40% YoY to a record ₹9,250 crore.
- Secured loans crossed 50% of the portfolio, led by strong growth in housing, MSME, vehicle finance and gold loans.
- Gold loans grew 248% YoY to ₹1,020 crore, while vehicle finance grew 85% YoY, with both crossing the ₹1,000 crore milestone.
- Microfinance trends improved, with slippages moderating to 1.6% and collection efficiency remaining around 99.7%.
- Deposits grew 25% YoY to ₹48,129 crore, strengthening the bank’s funding franchise.
Outlook
- Management maintained 25% advances growth guidance for FY27, with secured lending expected to drive growth.
- The secured mix is targeted at 56% by March 2027, supported by housing, MSME, gold and vehicle finance.
- FY27 RoA guidance was upgraded to 1.8-2.0%, while credit cost guidance was lowered to 0.9-1.0%.
- NIM is expected to remain around 8.5%, supported by higher-yielding emerging products.
- New growth engines such as gold loans, digital loans, pre-owned vehicles and mid-corporate lending are expected to further diversify the portfolio.
Recent Updates on Ujjivan Small Finance Bank Ltd.
- Universal Banking: Applied for transition from SFB to Universal Bank to expand its long-term banking opportunities.
- Leadership Transition: Carol Furtado appointed Acting MD & CEO following Sanjeev Nautiyal’s early retirement.
- Digital & Cross-Sell: Expanded into mutual fund distribution and co-branded credit cards to strengthen fee income.
- Branch & Product Expansion: Branch network reached 814, while gold and vehicle finance crossed ₹1,000 crore each.
- Strong Credit Profile: CRISIL reaffirmed the bank’s short-term A1+ rating, reflecting adequate capitalisation.
Company valuation insights – Ujjivan Small Finance Bank Ltd.
Ujjivan Small Finance Bank is currently trading at a P/B of 1.88x, while the stock has delivered a 39.9% return over the last one year, compared with an 8.1% decline in the NIFTY 50, reflecting improving investor confidence as the bank continues its transition toward a more diversified and secured loan portfolio.
The investment thesis is supported by strong earnings momentum, improving asset quality, stable margins, and accelerating portfolio diversification. Advances grew 29% YoY, while NII increased 39% YoY, supported by robust disbursement momentum and a growing secured lending franchise. The secured book has crossed 50% of advances, with management targeting 56% by FY27-end, led by housing, MSME, gold loans and vehicle finance. Meanwhile, GNPA/NNPA improved to 2.16%/0.34%, collection efficiency remained around 99.7%, and lower credit costs supported a sharp improvement in profitability. Management has also raised FY27 RoA guidance to 1.8-2.0% and lowered credit cost guidance to 0.9-1.0%. New growth engines such as gold loans, digital loans, pre-owned vehicle finance and mid-corporate lending provide further diversification, while strong deposit growth and operating leverage support the earnings outlook.
We value Ujjivan Small Finance Bank at 2.0x FY28E BVPS, arriving at a 12-month target price of ₹80, implying an upside potential of 24% from current levels. We believe the valuation is supported by the improving earnings trajectory, resilient asset quality, rising secured loan mix, strong deposit growth and improving return ratios. For the near term, we maintain a 3-month technical target of ₹68, implying an upside potential of 6% from current levels.
Major risk factors for Ujjivan Small Finance Bank Ltd.
- Microfinance Risk: A significant portion of the portfolio remains exposed to financially vulnerable borrowers.
- Asset Quality: Economic stress or borrower over-indebtedness could increase delinquencies and credit costs.
- Diversification Risk: Rapid expansion into newer products requires disciplined underwriting and portfolio seasoning.
- Funding Risk: Sustaining deposit growth and CASA improvement remains important for maintaining competitive funding costs.
- Management Transition: The ongoing CEO transition needs to remain smooth without disrupting the bank’s strategic execution.
Technical analysis of Ujjivan Small Finance Bank Ltd. share
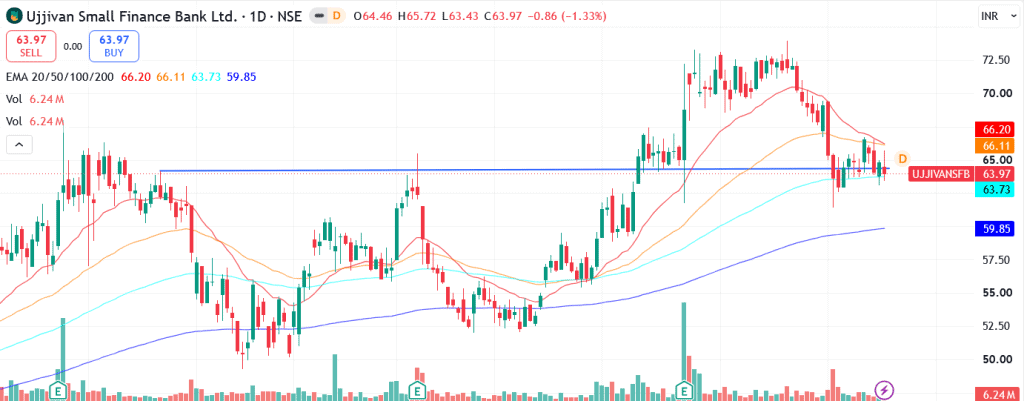
Ujjivan Small Finance Bank is currently in correction mode and trading near key support levels, with the broader long-term trend remaining intact as the stock continues to trade above its 100-day and 200-day EMAs. The recent decline appears to be a corrective phase within the broader trend, with the stock positioned near support and technical indicators approaching levels where a trend reversal could emerge.
Momentum indicators suggest that selling pressure is nearing exhaustion. The MACD at -1.17 remains negative and below its signal line, but is approaching a bullish crossover, indicating that downside momentum could be fading. The RSI at 40.86 is approaching oversold territory, leaving scope for a potential trend reversal if buying interest returns. Additionally, the 55-day Relative RSI of 0.08 indicates that the stock continues to outperform the broader benchmark over the longer term, despite the recent correction.
Trend reversal potential is improving, with the stock holding above its key long-term EMAs and trading near support. A bullish MACD crossover, combined with an RSI recovery, could strengthen the setup. A sustained move above ₹68 would reinforce the positive view and potentially support a move towards our ₹80 12-month fundamental target. On the downside, ₹60 remains the key support and stop-loss level.
- RSI: 40.86 (Near oversold; trend reversal possible)
- Relative RSI (Over 55 Days): 0.08 (Outperformance against the benchmark)
- MACD: -1.17 (Negative; bullish crossover awaited)
- Resistance: ₹68
- Support: ₹60
Ujjivan Small Finance Bank Ltd. stock recommendation
Current Stance: Buy, with a 3-month target price of ₹68 (6% upside) and a 12-month target price of ₹80 (24% upside), based on a valuation of 2.0x FY28E BVPS.

Why buy now?

Strong loan growth momentum, with 29% YoY growth in advances and Q1 disbursements rising over 40% YoY, supporting management’s 25% FY27 growth guidance.

Asset quality continues to improve, with GNPA/NNPA declining to 2.16%/0.34% and collection efficiency remaining around 99.7%, supporting lower credit costs.

Rapid portfolio diversification, with the secured loan mix crossing 50% and strong growth across housing, MSME, gold loans and vehicle finance.

Gold loans and other emerging businesses provide additional growth engines, while deposit growth of 25% YoY strengthens the funding franchise.

Management has raised FY27 RoA guidance to 1.8-2.0% and lowered credit cost guidance to 0.9-1.0%, reflecting improving asset quality and operating leverage.

Portfolio fit

Ujjivan Small Finance Bank offers exposure to India’s structural retail credit growth through a diversified lending franchise, improving asset quality and expanding secured portfolio. With the secured mix targeted at 56% by FY27-end, strong deposit growth, stable NIMs and emerging growth engines such as gold loans, micro-mortgages, vehicle finance and digital lending, the bank has multiple avenues to sustain earnings growth and improve shareholder returns over the medium to long term.
If you found this helpful and want regular stock trade calls, check out my community on StockGro here:Ujjivan Small Finance Bank Ltd.: Budget 2026-27 opportunities
- Financial Inclusion: Continued policy focus on formal credit can expand the addressable market for small finance banks.
- MSME Support: Government measures supporting MSMEs can stimulate demand for working capital and business loans.
- Affordable Housing: Housing and infrastructure initiatives can support affordable housing and micro-mortgage demand.
- Rural Development: Rural infrastructure and income-support measures can strengthen demand across underserved markets.
- Digital Financialisation: Greater adoption of digital payments, savings and investment products can improve customer acquisition and fee-based income.
Final thoughts
Ujjivan Small Finance Bank stands at an important inflection point, evolving from a predominantly microfinance-led institution into a more diversified retail banking franchise. Strong loan and deposit growth, rising secured exposure, improving asset quality and higher profitability provide a favourable foundation for the next phase of growth.
For investors seeking exposure to India’s financial inclusion and mid-sized banking opportunity, Ujjivan offers a combination of high growth, business diversification and improving return ratios. The sustainability of this transformation, management transition, credit costs and the ability to scale newer secured businesses profitably will remain the key factors to watch.