India’s logistics sector is undergoing a structural transformation, driven by the expansion of manufacturing, e-commerce, organised retail, infrastructure development and supply-chain formalisation. As businesses seek faster deliveries, better inventory management and more cost-efficient transportation, integrated logistics providers are gaining importance over fragmented, single-mode operators.
Transport Corporation of India Ltd. (TCI) is positioned to benefit from this shift through its integrated offerings across freight transportation, supply-chain solutions, coastal shipping and multimodal logistics. Its combination of road, rail, sea and warehousing capabilities provides exposure to India’s evolving supply-chain ecosystem, with opportunities to improve efficiency, expand value-added services and benefit from the gradual shift towards organised logistics.
But does Transport Corporation of India Ltd. offer a compelling case for long-term investors? Let’s delve deeper.
Stock overview
| Ticker | TCI |
| Industry/Sector | Logistics |
| CMP | 849.85 |
| Market Cap (₹ Cr.) | 6,542 |
| P/E | 14.64 (Vs Industry P/E of 46.45) |
| 52 W High/Low | 1242.00 / 797.00 |
| EPS (TTM) | 59.92 |
| Dividend Yield | 1.14% |
About Transport Corporation of India Ltd.
Transport Corporation of India is an integrated logistics and supply-chain solutions provider offering transportation, freight management, warehousing, coastal shipping and multimodal logistics services. The company serves customers across sectors such as automotive, consumer goods, industrial manufacturing, chemicals and other supply-chain-intensive industries.
Its business model combines asset-backed transportation capabilities with technology-enabled logistics and value-added supply-chain services. TCI’s strategy focuses on expanding multimodal capacity, improving operational efficiency and increasing the contribution of integrated logistics solutions to its business.
Key business segments
Transport Corporation of India Ltd. operates primarily in the following key business segments:
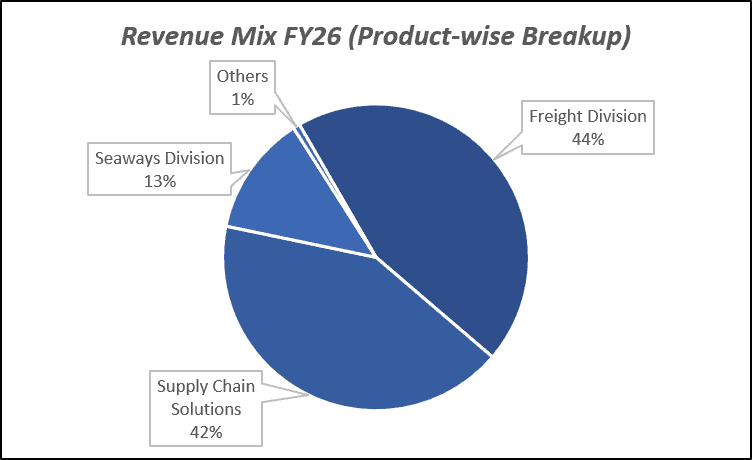
- TCI Freight: Surface transportation and freight services for full-truckload and less-than-truckload cargo.
- TCI Supply Chain Solutions: Integrated logistics, warehousing, distribution and customised supply-chain management.
- TCI Seaways: Coastal shipping and multimodal transportation for bulk and containerised cargo.
- TCI Global: International freight forwarding and cross-border logistics solutions.
- TCI Express: Express distribution and time-sensitive delivery services through a separately listed group company.
Primary growth factors for Transport Corporation of India Ltd.
Transport Corporation of India Ltd. key growth drivers:
- Manufacturing-Led Demand: Growth in industrial production and domestic consumption can increase freight and supply-chain volumes.
- Supply-Chain Solutions: Rising demand for integrated warehousing, distribution and inventory management can support higher-value services.
- Multimodal Expansion: Additional coastal vessels and rail rakes can improve capacity, asset productivity and transportation efficiency.
- Infrastructure Development: Investment in highways, ports, dedicated freight corridors and logistics parks can support network efficiency.
- Global Supply-Chain Diversification: China+1 strategies and international trade realignment can create opportunities for integrated logistics providers.
Detailed competition analysis for Transport Corporation of India Ltd.
Key financial metrics – TTM;
| Company | Sales (₹ Cr.) | EBITDA (₹ Cr.) | EBITDA Margin (%) | PAT (₹ Cr.) | PAT Margin (%) | P/E |
| Transport Corporation of India Ltd. | 5026.00 | 531.30 | 10.57% | 377.00 | 7.50% | 14.64 |
| Delhivery Ltd. | 11145.04 | 633.33 | 5.68% | 81.65 | 0.73% | 318.40 |
| BlackBuck Ltd. | 712.52 | 176.07 | 24.71% | 168.81 | 23.69% | 63.47 |
| VRL Logistics Ltd. | 3355.61 | 685.18 | 20.42% | 267.31 | 7.97% | 18.59 |
| TVS Supply Chain Solutions Ltd. | 11745.88 | 818.44 | 6.97% | 63.12 | 0.54% | 81.26 |
Key insights on Transport Corporation of India Ltd.
- Consistent Growth: FY26 consolidated revenue increased 9.4% to ₹4,965 crore, while profit after tax rose 10.5% to ₹460 crore.
- Supply-Chain Momentum: Supply Chain Solutions revenue crossed ₹1,862 crore in FY26, growing 14% and becoming the company’s largest business.
- Coastal Shipping Advantage: The Seaways business reported an EBIT margin of approximately 41% in FY26, highlighting its profitability potential.
- Capacity Expansion: Two coastal vessels and two double-deck rail rakes are planned to strengthen multimodal capacity.
- Strong Credit Profile: The company’s credit rating was upgraded to AA+/Stable, reflecting its financial position and creditworthiness.
Recent financial performance of Transport Corporation of India Ltd. for Q1 FY27
| Metric | Q1 FY26 | Q4 FY26 | Q1 FY27 | QoQ Growth (%) | YoY Growth (%) |
| Sales (₹ Cr.) | 1139.30 | 1323.80 | 1248.50 | -5.69% | 9.58% |
| EBITDA (₹ Cr.) | 121.00 | 142.40 | 135.20 | -5.06% | 11.74% |
| EBITDA Margin (%) | 10.62% | 10.76% | 10.83% | 7 bps | 21 bps |
| PAT (₹ Cr.) | 87.50 | 105.20 | 88.20 | -16.16% | 0.80% |
| PAT Margin (%) | 7.68% | 7.95% | 7.06% | -89 bps | -62 bps |
| Adjusted EPS (₹) | 13.92 | 16.16 | 13.73 | -15.04% | -1.36% |
Transport Corporation of India Ltd. financial update (Q1 FY27)
Financial performance
- Revenue grew 9.58% YoY to ₹1,248.50 crore, supported by steady growth across freight, supply chain solutions and seaways.
- EBITDA increased 11.74% YoY to ₹135.20 crore, with EBITDA margin improving by 21 bps YoY to 10.83%, reflecting resilient operating performance.
- PAT grew 0.80% YoY to ₹88.20 crore, remaining broadly stable amid higher operating costs and pressure on seaways margins.
- Adjusted EPS stood at ₹13.73, compared with ₹13.92 in Q1 FY26, reflecting marginally lower earnings per share.
- Supply Chain Solutions revenue grew 10% YoY, while Freight and Seaways revenue increased 8.9% and 6.2%, respectively, demonstrating growth across all three core segments.
Business highlights
- TCI opened 10 new freight branches during the quarter and plans to add another 30, expanding its less-than-truckload (LTL) network.
- Supply Chain Solutions continued to benefit from demand across automotive, retail, consumer goods and quick commerce, with management expecting 10–15% revenue growth in the segment.
- The company ordered two additional rail rakes, expected to be commissioned over the next 12–15 months, strengthening multimodal and automobile logistics capabilities.
- The Cold Chain JV recorded approximately 49% YoY growth, supported by customer additions in quick commerce and retail.
- TCI’s Seaways business is investing in capacity expansion, with approximately ₹240 crore earmarked for ships as part of its FY27 capex plan, strengthening its multimodal logistics capabilities and long-term growth potential.
Outlook
- Management has maintained its FY27 consolidated revenue and profit growth guidance of 10–12%, supported by steady freight demand and continued expansion in supply chain services.
- Revenue projected at ₹5,579 crore in FY27 and ₹6,367 crore in FY28, with EBITDA margins expected to remain around 10.6%.
- The company plans to invest approximately ₹600 crore in FY27 capex, including ₹240 crore towards ships, to expand capacity and support future growth.
- Increasing LTL penetration, fresh automobile inventory replenishment and the commissioning of additional rail rakes are expected to support growth and improve logistics efficiency.
- Key risks to monitor include volatile fuel prices, persistent freight cost pressures, moderating supply chain growth and lower Seaways margins.
Recent Updates on Transport Corporation of India Ltd.
- China Expansion: TCI announced plans to incorporate a wholly owned subsidiary in China, supporting its international expansion strategy.
- Coastal Fleet Expansion: Plans to increase coastal shipping capacity by 30–40% over four to five years, supported by new vessels and fleet investment.
- Flying Whales Partnership: Entered a strategic collaboration to explore heavy-lift airship-based logistics solutions for remote and difficult-to-access locations.
- Rail Infrastructure: Two double-deck rail rakes are planned to expand capacity and strengthen multimodal freight capabilities.
- New Vessel Investment: Two coastal vessels are expected to be delivered during FY27, supporting capacity growth and operating efficiency.
Company valuation insights – Transport Corporation of India Ltd.
Transport Corporation of India (TCI) is currently trading at a TTM P/E of 14.64x, significantly below the industry average of 46.45x. The stock has delivered a 93% return over the last five years, outperforming the NIFTY 50’s 25.9%, reflecting its strong long-term performance and established position in the logistics sector.
The investment thesis is supported by steady freight growth, expanding supply chain solutions, multimodal logistics capabilities and long-term capacity expansion. In Q1FY27, revenue grew 9.58% YoY to ₹1,248.50 crore, while EBITDA increased 11.74% YoY, with margins improving to 10.83%. The freight business benefited from healthy volume growth and traction in less-than-truckload (LTL) services, while Supply Chain Solutions continued to see demand across automotive, retail, consumer goods and quick commerce. The company is expanding its LTL network, investing in additional rail rakes and strengthening its warehousing and fleet capacity. Its Seaways business also offers long-term growth potential amid increasing multimodal logistics adoption and policy support for coastal shipping. Management has maintained its FY27 revenue and profit growth guidance of 10–12%, supported by continued expansion across its core businesses.
We value TCI at 14x FY28E EPS of ₹75, arriving at a 12-month target price of ₹1,050, implying an upside potential of 24% from current levels. The valuation is supported by its diversified logistics operations, steady earnings growth, expansion in multimodal transportation and continued investments in capacity. For the near term, we maintain a 3-month target price of ₹900, implying a 6% upside potential from current levels.
Major risk factors for Transport Corporation of India Ltd.
- Fuel Cost Risk: Higher diesel and bunker fuel prices can pressure margins if cost increases cannot be passed on promptly.
- Economic Slowdown: Weaker industrial activity and consumption can reduce freight volumes and logistics demand.
- Execution Risk: Delays in vessel delivery, rail capacity expansion or new investments can defer expected growth.
- Working Capital Risk: Customer payment cycles and capital-intensive operations can affect cash flow.
- Geopolitical Risk: Trade disruptions and international conflicts can affect freight costs, shipping routes and cross-border demand.
Technical analysis of Transport Corporation of India Ltd. share
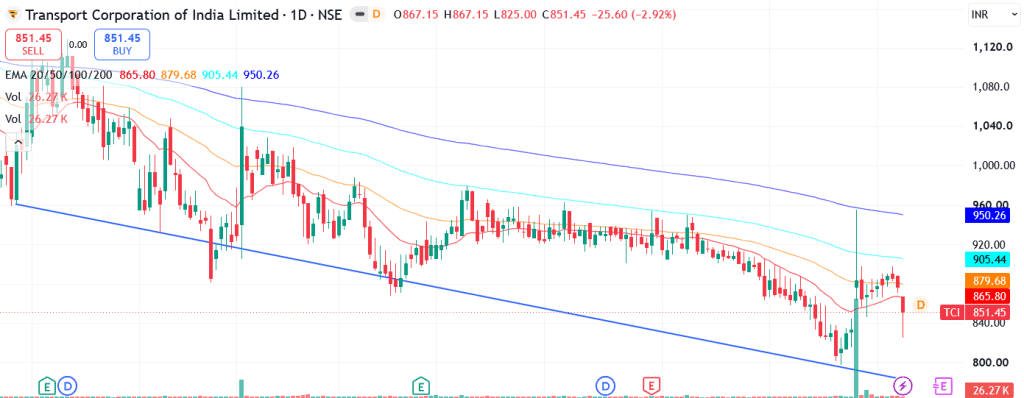
TCI was previously in a downtrend but has bounced back positively from an important support level, indicating a potential reversal in its near-term price structure. The stock is approaching a crossover above its 20-day EMA, which could present a potential entry opportunity if confirmed. A sustained move above ₹900, the key resistance level, could strengthen bullish momentum and pave the way towards ₹1,050, our 12-month fundamental target.
Momentum indicators are showing early signs of improvement. The MACD at -0.55 remains in negative territory but is above its signal line, suggesting a potential recovery in momentum. The RSI at 43.98 indicates improving buying interest, although momentum remains below the bullish threshold of 50. The 21-day and 55-day Relative RSI readings of 0.02 and 0.01, respectively, indicate marginal outperformance against the benchmarks.
Trend strength remains strong, with the ADX at 34.37, indicating a well-established trend, although the recent price rebound and momentum indicators suggest that confirmation of a sustained reversal is still important. A decisive move above ₹900 could support further upside towards ₹1,050. On the downside, ₹800 remains the key support and stop-loss level.
- RSI: 43.98 (Decent buying interest)
- ADX: 34.37 (Strong trend)
- MACD: -0.55 (Negative; above signal line)
- Resistance: ₹900
- Support: ₹800
Transport Corporation of India Ltd. stock recommendation
Current Stance: Buy, with a 3-month target price of ₹900 (6% upside) and a 12-month target price of ₹1,050 (24% upside), based on 14x FY28E EPS of ₹75.

Why buy now?

Steady revenue growth: Q1FY27 revenue grew 9.58% YoY to ₹1,248.50 crore, supported by healthy freight volumes and continued expansion across core business segments.

Expanding freight network: TCI added 10 new branches during the quarter and plans to add another 30, strengthening its less-than-truckload (LTL) network and market reach.

Supply chain growth: Supply Chain Solutions revenue grew approximately 10% YoY, supported by demand across automotive, retail, consumer goods and quick commerce. Management expects 10–15% growth in this segment.

Multimodal logistics opportunity: Two additional rail rakes are expected to be commissioned over the next 12–15 months, enhancing automobile logistics capabilities and supporting the shift towards integrated transportation solutions.

Healthy earnings outlook: Management maintained its FY27 revenue and profit growth guidance of 10–12%, supported by capacity expansion, continued investments in logistics infrastructure and growth across its core businesses.

Portfolio fit

TCI provides exposure to India’s expanding logistics and supply chain sector through its diversified freight, supply chain and seaways businesses. Its established operating network, growing LTL presence, investments in multimodal transportation and long-term opportunities in coastal shipping position it to benefit from rising logistics demand and infrastructure development. While near-term fuel-price volatility and margin pressure remain key risks, its diversified business model and planned capacity expansion support its long-term growth prospects.
If you found this helpful and want regular stock trade calls, check out my community on StockGro here:Transport Corporation of India Ltd.: Budget 2026-27 opportunities
- Infrastructure Spending: Continued investment in highways, ports and freight corridors can improve logistics efficiency and expand freight demand.
- PM Gati Shakti: Integrated infrastructure planning can improve multimodal connectivity and reduce logistics bottlenecks.
- Manufacturing Expansion: Domestic manufacturing incentives can increase transportation and contract-logistics requirements.
- Rail & Coastal Freight: Greater emphasis on efficient freight movement can support modal shifts from road to rail and coastal shipping.
- Digital & Green Logistics: Focus on supply-chain digitisation, emissions measurement and cleaner transportation can favour organised logistics providers.
Final thoughts
TCI stands at an important stage in its evolution, with Supply Chain Solutions gaining scale and planned investments in coastal shipping and rail infrastructure strengthening its integrated logistics offering. Its diversified business model, established customer relationships and exposure to India’s manufacturing and infrastructure growth provide multiple avenues for expansion.
For investors seeking exposure to India’s logistics formalisation, multimodal transportation and supply-chain modernisation, TCI offers a diversified business with structural growth opportunities. Revenue growth, freight demand, fuel-cost pass-through, vessel utilisation, working-capital efficiency and returns on new investments will remain the key factors to monitor.