Water infrastructure is becoming increasingly important as India expands rural drinking-water coverage, modernises irrigation networks and invests in wastewater treatment. These projects require reliable pumping systems, specialised engineering and long-term maintenance—creating opportunities for companies with established manufacturing capabilities and project-execution expertise.
WPIL Ltd. is positioned across this value chain through its pump products, turnkey water projects and international engineering operations. Its global expansion through acquisitions has broadened its capabilities and geographic reach, while its domestic business provides exposure to India’s water infrastructure investment cycle.
The investment thesis rests on three drivers: a recovery in domestic project execution, continued growth in international operations and an increasing contribution from products, aftermarket sales and operations and maintenance (O&M). The key challenge is converting these opportunities into sustainable earnings and stronger cash flows.
But does WPIL Ltd. offer a compelling case for long-term investors? Let’s delve deeper.
Stock overview
| Ticker | WPIL |
| Industry/Sector | Capital Goods |
| CMP | 433.80 |
| Market Cap (₹ Cr.) | 4,209 |
| P/E | 17.69 (Vs Industry P/E of 23.12) |
| 52 W High/Low | 510.35 / 383.55 |
| EPS (TTM) | 23.84 |
| Dividend Yield | 0.47% |
About WPIL Ltd.
Water infrastructure is becoming increasingly important as India expands rural drinking-water coverage, modernises irrigation networks and invests in wastewater treatment. These projects require reliable pumping systems, specialised engineering and long-term maintenance, creating opportunities for companies with established manufacturing capabilities and project-execution expertise.
WPIL Ltd. is positioned across this value chain through its pump products, turnkey water projects and international engineering operations. Its global expansion through acquisitions has broadened its capabilities and geographic reach, while its domestic business provides exposure to India’s water infrastructure investment cycle.
The investment thesis rests on three drivers: a recovery in domestic project execution, continued growth in international operations and an increasing contribution from products, aftermarket sales and operations and maintenance (O&M). The key challenge is converting these opportunities into sustainable earnings and stronger cash flows.
Key business segments
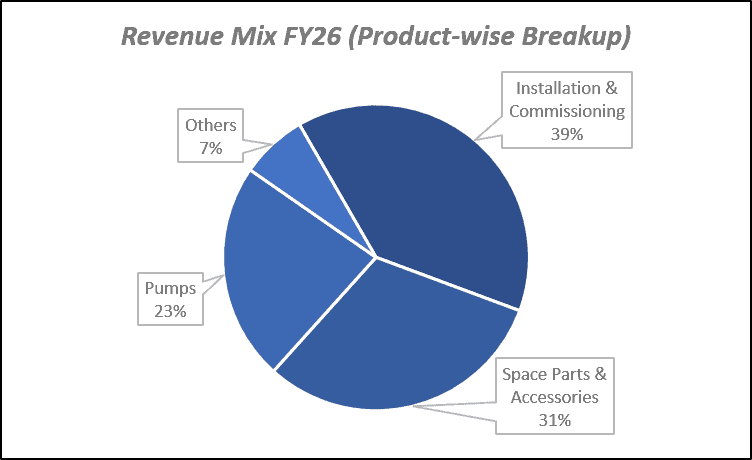
WPIL Ltd. operates primarily in the following key business segments:
- Assembled-to-Order Pumps: Standardised and customised pump solutions for municipal water supply and industrial applications.
- Engineered-to-Order Pumps: Specialised, high-capacity pumping systems for irrigation, power and other demanding applications.
- Domestic Projects: Turnkey water-supply, irrigation and pumping infrastructure projects in India.
- International Projects: Water infrastructure and engineering projects executed through overseas subsidiaries.
- Aftermarket and O&M: Spare parts, maintenance, servicing and long-term operation of pumping infrastructure.
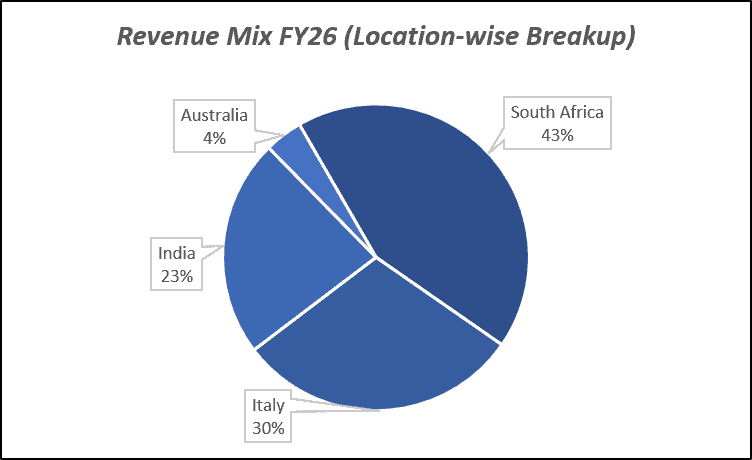
Primary growth factors for WPIL Ltd.
WPIL Ltd. key growth drivers:
- Jal Jeevan Mission 2.0: Renewed rural drinking-water investment can support demand for pumps and water-supply infrastructure.
- International Expansion: Overseas subsidiaries and large water projects provide opportunities to expand revenue beyond India.
- Product Business Growth: Rising demand for specialised pumps across municipal, industrial and power applications can support product revenue.
- Aftermarket and O&M: A larger installed base can generate recurring service revenue and improve earnings visibility.
- Water and Wastewater Infrastructure: Investments in irrigation, sewage treatment, desalination and industrial water systems can expand the addressable market.
Detailed competition analysis for WPIL Ltd.
Key financial metrics – TTM;
| Company | Sales (₹ Cr.) | EBITDA (₹ Cr.) | EBITDA Margin (%) | PAT (₹ Cr.) | PAT Margin (%) | P/E |
| WPIL Ltd. | 1976.52 | 344.45 | 17.43% | 216.43 | 10.95% | 17.69 |
| Elgi Equipments Ltd. | 4146.20 | 613.30 | 14.79% | 442.40 | 10.67% | 40.97 |
| KSB Ltd. | 2725.60 | 346.80 | 12.72% | 230.70 | 8.46% | 55.57 |
| Kirloskar Brothers Ltd. | 4663.90 | 548.20 | 11.75% | 357.40 | 7.66% | 35.57 |
| Ingersol-Rand (India) Ltd. | 1456.51 | 349.35 | 23.99% | 267.51 | 18.37% | 47.53 |
Key insights on WPIL Ltd.
- Consolidated Performance: FY26 revenue from operations rose to approximately ₹1,855 crore from ₹1,807 crore, while reported net profit including discontinued operations increased to approximately ₹200 crore from ₹127 crore.
- International Business Momentum: International revenue increased to approximately ₹1,136 crore in FY26 from ₹668 crore in FY25, becoming a major contributor to consolidated revenue.
- Domestic Product Strength: Product-division revenue increased to ₹374 crore from ₹323 crore, supported by growth in both assembled-to-order and engineered-to-order pumps.
- Domestic Project Weakness: Project-division revenue declined sharply to approximately ₹391 crore from ₹823 crore, reflecting execution and funding constraints in the domestic water-infrastructure market.
- Large Order Pipeline: WPIL has reported a consolidated order book of around ₹6,000 crore in 2026, providing potential revenue visibility; execution, collections and cash conversion remain critical.
Recent financial performance of WPIL Ltd. for Q1 FY27
| Metric | Q1 FY26 | Q4 FY26 | Q1 FY27 | QoQ Growth (%) | YoY Growth (%) |
| Sales (₹ Cr.) | 378.58 | 511.25 | 500.54 | -2.09% | 32.22% |
| EBITDA (₹ Cr.) | 49.20 | 76.16 | 75.30 | -1.13% | 53.05% |
| EBITDA Margin (%) | 13.00% | 14.90% | 15.04% | 14 bps | 204 bps |
| PAT (₹ Cr.) | 22.66 | 47.04 | 47.79 | 1.59% | 110.90% |
| PAT Margin (%) | 5.99% | 9.20% | 9.55% | 35 bps | 356 bps |
| Adjusted EPS (₹) | 2.29 | 4.14 | 3.47 | -16.18% | 51.53% |
WPIL Ltd. financial update (Q1 FY27)
Financial performance
- Revenue grew 32.22% YoY to ₹500.54 crore, supported by strong international execution and growth across pumps, accessories and project businesses.
- EBITDA increased 53.05% YoY to ₹75.30 crore, with EBITDA margin expanding 204 bps to 15.04%, reflecting improved operating leverage and a stronger business mix.
- PAT increased 110.90% YoY to ₹47.79 crore, supported by revenue growth and improved operating profitability.
- PAT margin improved by 356 bps YoY to 9.55%, indicating a substantial improvement in bottom-line profitability.
- Adjusted EPS rose 51.53% YoY to ₹3.47, reflecting stronger earnings performance compared with Q1 FY26.
Business highlights
- International business remained the key growth driver, with revenue increasing to approximately ₹386 crore from ₹197 crore in Q1 FY26, supported by strong execution across global subsidiaries.
- The international order book stood at approximately ₹2,891 crore, providing medium-term revenue visibility across product and project operations.
- The product business witnessed healthy demand across the Middle East, particularly in water and oil & gas applications, while Australian operations benefited from opportunities in LNG, mining and industrial projects.
- PCI Africa commenced execution of large water-sector contracts secured in FY26, while MISA Italy completed legacy projects and continued to build its irrigation and drainage pipeline.
- Domestic project execution remained subdued due to delays in government-funded water infrastructure projects, particularly under the Jal Jeevan Mission, although the pumps and accessories business continued to grow.
Outlook
- Management expects consolidated quarterly revenue to remain around ₹500 crore, with potential improvement as domestic project execution normalises.
- The international business is expected to sustain momentum, supported by strong order books, project execution in South Africa and demand across Europe, Australia and the Middle East.
- A recovery in Jal Jeevan Mission-related fund disbursements could support domestic project invoicing and improve execution during the second half of FY27.
- Consolidated EBITDA margins are expected to remain within the 15–20% range, with potential improvement as international operations scale and the business mix strengthens.
- Management plans to improve subsidiary ownership over the medium term, beginning with increasing its stake in PCI Africa, which could streamline the group structure and enhance its share of subsidiary earnings.
Recent Updates on WPIL Ltd.
- PCI Africa Order: WPIL’s South African subsidiary secured a consortium share worth approximately ₹1,172 crore for the Lower Umkhomazi Bulk Water Supply Scheme Phase 2, with a 36-month construction period.
- Jal Jeevan Mission 2.0: The government extended the mission to December 2028, with a total outlay of ₹8.69 lakh crore, creating a potential demand tailwind for water infrastructure suppliers.
- MP Jal Nigam Correspondence: WPIL disclosed receipt of a letter from Madhya Pradesh Jal Nigam in June 2026, making the nature and commercial implications of the communication worth monitoring.
- Australian Subsidiary Divestment: WPIL disclosed the sale of its Australian subsidiary, Sterling Pumps, as part of changes to its international portfolio.
- Dividend Recommendation: The Board recommended a final dividend of ₹2 per equity share for FY26, subject to shareholder approval.
Company valuation insights – WPIL Ltd.
WPIL is currently trading at a TTM P/E of 17.69x, below the industry average of 23.12x. The stock has delivered a 1.3% return over the last year, outperforming the NIFTY 50’s -10.7%, demonstrating relative resilience amid broader market weakness.
The investment thesis is supported by strong international demand, a robust overseas order book, improving profitability and opportunities in water infrastructure. In Q1FY27, revenue grew 32.22% YoY to ₹500.54 crore, while EBITDA increased 53.05% YoY to ₹75.30 crore, with margins expanding to 15.04%. International operations remain a key growth driver, supported by project execution across Africa, Europe, Australia and the Middle East. The international order book provides revenue visibility, while demand across water management, irrigation, mining and industrial applications offers opportunities for sustained growth. A recovery in domestic government-funded water infrastructure projects could provide an additional growth driver as execution improves.
We value WPIL at 17x FY28E EPS of ₹32, arriving at a 12-month target price of ₹544, implying an upside potential of 25% from current levels. The valuation is supported by strong international order visibility, improving operating margins, expanding global operations and long-term demand for water infrastructure and pumping solutions. For the near term, we maintain a 3-month target price of ₹460, implying a 6% upside potential from current levels.
Major risk factors for WPIL Ltd.
- Working-Capital Risk: Delayed project payments and rising receivables can constrain operating cash flow despite reported profits.
- Execution Risk: Delays in large water projects can defer revenue recognition and increase project costs.
- Government Spending Risk: Dependence on public infrastructure projects exposes the company to funding delays and changes in implementation priorities.
- International Risk: Currency movements, geopolitical conditions and differences in overseas operating environments can affect subsidiary performance.
- Acquisition and Integration Risk: Integrating international businesses and managing their profitability, capital requirements and operational complexity may affect returns.
Technical analysis of WPIL Ltd. share
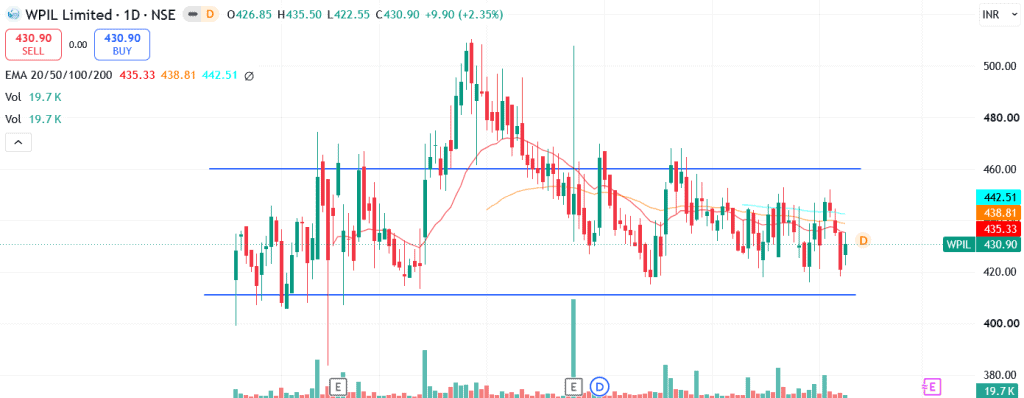
WPIL is currently trading within a sideways channel, with the price approaching the lower trendline, which could present a potential entry opportunity if support holds and momentum improves. Although the stock is trading below all its key EMAs, a recovery from the lower end of the channel could signal improving price momentum. A sustained breakout above ₹460, the key resistance level, could pave the way towards ₹544, our 12-month fundamental target.
Momentum indicators remain mixed. The MACD at -2.08 is in negative territory and below its signal line, with a bullish crossover awaited to confirm improving momentum. The RSI at 47.46 indicates moderate buying interest, although the stock remains below the bullish threshold of 50. The 21-day and 55-day Relative RSI readings of 0.06 and 0.01, respectively, indicate outperformance against the benchmarks.
Trend strength is low, with the ADX at 9.13, indicating a range-bound market rather than a strong directional trend. A rebound from the lower trendline, followed by a bullish MACD crossover and a sustained move above ₹460, could strengthen the technical setup and support a move towards ₹544. On the downside, ₹400 remains the key support and stop-loss level.
- RSI: 47.46 (Moderate buying interest)
- ADX: 9.13 (Range-bound trend)
- MACD: -2.08 (Negative; below signal line, crossover awaited)
- Resistance: ₹460
- Support: ₹400
WPIL Ltd. stock recommendation
Current Stance: Buy, with a 3-month target price of ₹460 (6% upside) and a 12-month target price of ₹544 (25% upside), based on 17x FY28E EPS of ₹32.

Why buy now?

Strong revenue growth: Q1FY27 revenue grew 32.22% YoY to ₹500.54 crore, supported by international operations.

Improving profitability: EBITDA grew 53.05% YoY, with margins expanding 204 bps to 15.04%.

Strong order visibility: A robust international order book supports medium-term revenue visibility.

Global expansion: Operations across Africa, Europe, Australia and the Middle East provide diversified growth opportunities.

Domestic recovery potential: Improved execution of government-funded water infrastructure projects could support incremental growth.

Portfolio fit

WPIL offers exposure to global water infrastructure and industrial pumping demand, supported by international operations, a strong order book and improving profitability. Its global expansion and domestic recovery potential provide long-term growth opportunities, although project execution remains a key monitorable.
If you found this helpful and want regular stock trade calls, check out my community on StockGro here:WPIL Ltd.: Budget 2026-27 opportunities
- Jal Jeevan Mission: The ₹67,670 crore Budget allocation for the mission could support rural drinking-water infrastructure and related pumping requirements.
- Higher Public Capex: The ₹12.2 lakh crore central public-capital-expenditure allocation could indirectly support infrastructure demand across water, energy and industry.
- Irrigation Investments: Support for irrigation and water-resource management could create opportunities for high-capacity pumps and engineered pumping systems.
- Wastewater and River Rejuvenation: Continued investment in wastewater treatment and river-cleaning programmes could support demand for pumping equipment and related infrastructure.
- Water Infrastructure Modernisation: Greater focus on reliable service delivery, digital monitoring and long-term maintenance under water programmes could create opportunities in equipment upgrades and O&M.
Final thoughts
WPIL offers exposure to the intersection of specialised pump engineering, global water infrastructure and India’s long-term water-security requirements. Its international business and product division provide growth avenues, while a recovery in domestic project execution could support the next phase of expansion.
For investors evaluating WPIL, the critical distinction is between order-book growth and cash-generating growth. International project execution, domestic payment cycles, working-capital efficiency, subsidiary profitability and returns on new investments will determine the quality and sustainability of earnings. Valuation should be assessed alongside these factors before drawing an investment conclusion.