Stock overview
| Ticker | Avenue Supermarts |
| Sector | Retail |
| Market Cap | ₹ 2,77,200 Cr |
| CMP (Current Market Price) | ₹ 4,261 |
| 52-Week High/Low | ₹ 5,485/3,337 |
| Beta | 0.9 (Low volatility) |
About Avenue Supermarts India Ltd.
Avenue Supermarts Ltd. was founded by the legendary investor and entrepreneur Radhakishan Damani in 2002. With a unique EDLP (Everyday Low Pricing) strategy and strict focus on operational efficiency, DMart has grown to over 370 stores, dominating the Indian organized retail landscape with a loyal customer base and robust store-level profitability.
Primary growth factors for Avenue Supermarts India Ltd
- Value Pricing Strategy: Everyday Low Pricing ensures high footfalls and volume-driven margins.
- Store Expansion: Aggressive yet disciplined expansion into Tier 2/3 cities.
- Supply Chain Strength: In-house logistics reduces costs and ensures inventory efficiency.
- Private Labels: Growing contribution from private label products supports higher margins.
- Urban Consumption Growth: Rising discretionary spending in urban India sustains growth runway.
Q4 FY25 financial performance
| Metric | Q4 FY 25 | YoY Growth | QoQ Growth |
| Revenue | ₹ 14,871 cr | 17% | -7% |
| Operating Expense | ₹ 14,157 cr | 18% | -5% |
| Operating Income | ₹ 714 cr | -4% | -27% |
| PAT | ₹ 551 cr | -2% | -24% |
Avenue Supermarts delivered a mixed bag of results in Q4 FY 25. While they have reported a healthy double digit growth of 17% in revenue, their expenses have also risen by 18% which has put a dent on their overall profitability.
Detailed competition analysis for Avenue Supermarts India
| Company | Market Cap | Revenue | P/E Multiple | RoCE |
| Avenue Supermarts | ₹ 2,77,200 cr | ₹ 14,871 cr | 102 x | 18% |
| Vishal Mega Mart | ₹ 60,200 cr | ₹ 2,547 cr | 95 x | 13% |
| V Mart Retail | ₹ 6,200 cr | ₹ 780 cr | 290 x | 8% |
| Electronics Mart | ₹ 5,500 cr | ₹ 1,718 cr | 34 x | 10% |
The valuation looks fair to slightly expensive, but its execution consistency and MOAT justify premium multiples.
Company valuation insights: Avenue Supermarts India
As per the Discounted Cash Flow analysis:
It estimates the intrinsic value of Avenue Supermarts shares based on expected future cash flows:
- Intrinsic Value Estimate: ₹4650 per share
- Upside Potential: 10%
- WACC: 10.5%
- Terminal Growth Rate: 3%
Major risk factors affecting Avenue Supermarts India
- Competitive Pressures: E-commerce giants and quick-commerce apps eating into grocery market share.
- Rising Rentals: New leases in urban areas could impact store-level margins.
- Execution Risk: Large-scale expansion always risks diluting operational excellence.
- Premium Valuation: Leaves little cushion if growth falters.
Technical analysis of Avenue Supermarts India
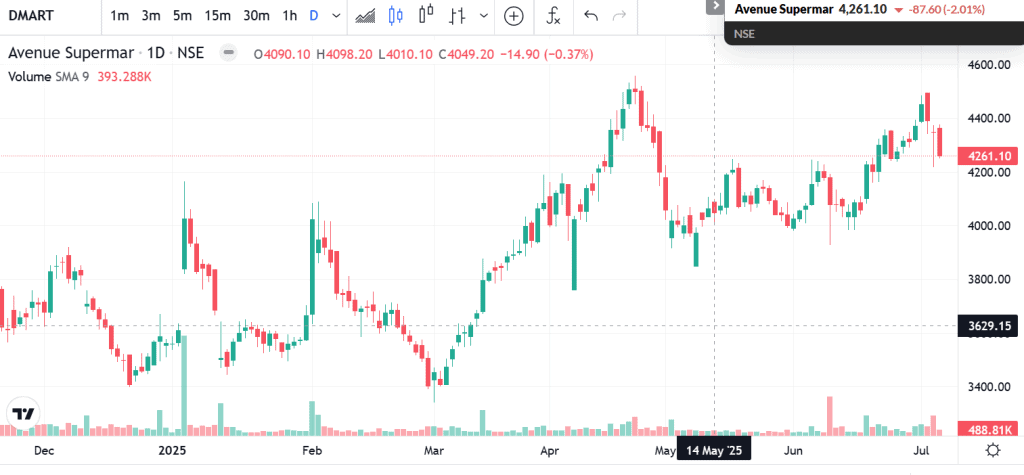
- Resistance: ₹4500
- Support: ₹ 4120
- Momentum: Neutral
- RSI (Relative Strength Index): 41 (Neutral)
- 50-Day Moving Average: ₹4380
- 200-Day Moving Average: ₹4190
- MACD: Positive crossover; bullish divergence
Technically bullish with potential for breakout above ₹4500
Avenue Supermarts India stock recommendation by Ketan Mittal
Recommendation: Buy on dips / Long-term accumulate

Target Price: ₹4400 (6-month horizon); ₹4650 (12-month horizon);

Investment Horizon: 2–4 years for stable returns

Rationale

Recommend a Buy on Dips / Accumulate approach for Avenue Supermarts.

Recommendation

Accumulate / Buy on Dips

DMart’s proven retailing strategy, robust balance sheet, and razor-sharp execution make it a solid long-term compounder. Its moat in supply chain and low-price leadership gives comfort even in volatile consumption cycles.
If you found this helpful and want regular stock trade calls, check out my StockGro profile here Conclusion
Avenue Supermarts (DMart) remains a best-in-class retail play, albeit at rich valuations. For long-term investors who value predictable execution, it could still deliver steady compounding, though near-term upside might be capped without a major trigger.