India’s trucking industry remains the backbone of domestic freight movement, yet truck operators continue to face fragmented payment systems, inefficient freight discovery, limited access to financing and challenges in vehicle utilisation. As logistics becomes increasingly technology-driven, platforms that simplify these everyday operations have the potential to create value across the trucking ecosystem.
BlackBuck Ltd. is positioning itself at the intersection of logistics, financial services and digital infrastructure. By integrating FASTag-based toll payments, fuel payments, vehicle telematics, freight discovery and vehicle financing, the company aims to become a comprehensive digital platform for truck operators. Its investment story rests on three key themes: deeper customer engagement, monetisation through multiple services and the ability to scale profitably as India’s freight ecosystem formalises.
But does BlackBuck Ltd. offer a compelling case for long-term investors? Let’s delve deeper.
Stock overview
| Ticker | BLACKBUCK |
| Industry/Sector | Logistics |
| CMP | 592.60 |
| Market Cap (₹ Cr.) | 10,790 |
| P/E | 63.47 (Vs Industry P/E of 46.45) |
| 52 W High/Low | 748.00 / 496.00 |
| EPS (TTM) | 9.26 |
| Dividend Yield | 0.00% |
About BlackBuck Ltd.
BlackBuck, formerly known as Zinka Logistics Solutions Ltd., is a technology-led platform focused on digitally empowering India’s trucking community. The company connects truck operators with services that help manage payments, monitor vehicles, discover freight opportunities and access financing.
Its business model combines a digital platform with financial services through its subsidiary, Blackbuck Finserve, which holds an NBFC licence. Rather than operating primarily as a traditional fleet owner, BlackBuck focuses on providing technology and services that improve the efficiency of existing trucking operations.
The company’s long-term opportunity lies in increasing the number of active customers, encouraging existing users to adopt more services and expanding the contribution of growth businesses while maintaining profitability.
Key business segments
BlackBuck Ltd. operates primarily in the following key business segments:
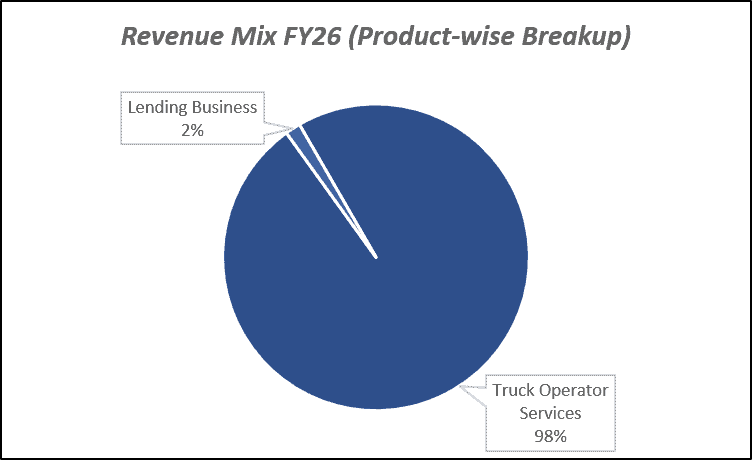
- Tolling and Payments: FASTag-led toll payments and related digital payment services for truck operators.
- Fuel Payments: Digital fuel payment solutions designed to simplify fuel purchases and expense management.
- Telematics: GPS-based vehicle tracking and monitoring solutions that improve fleet visibility and utilisation.
- SuperLoads: Digital freight discovery and load-matching services connecting truck operators with freight opportunities.
- Vehicle Financing: Commercial vehicle financing through its lending subsidiary, Blackbuck Finserve.
Primary growth factors for BlackBuck Ltd.
BlackBuck Ltd. key growth drivers:
- Digitalisation of Trucking: Increasing adoption of digital payments and fleet-management tools can expand BlackBuck’s addressable customer base.
- Cross-Selling Opportunities: Encouraging existing customers to use multiple services can increase revenue per customer and strengthen engagement.
- SuperLoads Expansion: Improving load discovery, productivity and geographic reach can support growth in the freight marketplace.
- Telematics Adoption: Demand for real-time tracking, route visibility and fleet efficiency can support device sales and recurring customer engagement.
- Vehicle Finance Growth: Scaling commercial vehicle financing while managing credit costs can create an additional earnings stream.
Detailed competition analysis for BlackBuck Ltd.
Key financial metrics – TTM;
| Company | Sales (₹ Cr.) | EBITDA (₹ Cr.) | EBITDA Margin (%) | PAT (₹ Cr.) | PAT Margin (%) | P/E |
| BlackBuck Ltd. | 712.52 | 176.07 | 24.71% | 168.81 | 23.69% | 63.47 |
| Delhivery Ltd. | 11145.04 | 633.33 | 5.68% | 81.65 | 0.73% | 318.40 |
| Transport Corporation of India Ltd. | 5026.00 | 531.30 | 10.57% | 377.00 | 7.50% | 14.64 |
| VRL Logistics Ltd. | 3355.61 | 685.18 | 20.42% | 267.31 | 7.97% | 18.59 |
| TVS Supply Chain Solutions Ltd. | 11745.88 | 818.44 | 6.97% | 63.12 | 0.54% | 81.26 |
Key insights on BlackBuck Ltd.
- First Full Year of Profitability: BlackBuck reported FY26 profit after tax of approximately ₹160.3 crore, compared with a loss of approximately ₹86.6 crore in FY25.
- Expanding Customer Base: Annual transacting customers reached approximately 8.18 lakh, growing 13% year-on-year.
- Deeper Platform Engagement: Users accessing at least two services increased to approximately 4.12 lakh, reflecting broader adoption of the platform.
- Strong Tolling Activity: FY26 tolling gross transaction value reached approximately ₹25,904 crore, up 27% year-on-year.
- Improving Operating Leverage: Greater customer activity and multi-product usage can support profitability as the platform scales, although investment in growth businesses remains important.
- Growth Businesses Gaining Traction: SuperLoads and vehicle financing provide additional monetisation opportunities beyond the established payments and telematics businesses.
Recent financial performance of BlackBuck Ltd. for Q1 FY27
| Metric | Q1 FY26 | Q4 FY26 | Q1 FY27 | QoQ Growth (%) | YoY Growth (%) |
| Sales (₹ Cr.) | 143.61 | 185.43 | 204.17 | 10.11% | 42.17% |
| EBITDA (₹ Cr.) | 40.40 | 45.06 | 49.71 | 10.32% | 23.04% |
| EBITDA Margin (%) | 28.13% | 24.30% | 24.35% | 5 bps | -378 bps |
| PAT (₹ Cr.) | 33.70 | 65.73 | 42.17 | -35.84% | 25.13% |
| PAT Margin (%) | 23.46% | 35.45% | 20.65% | -1480 bps | -281 bps |
| Adjusted EPS (₹) | 1.88 | 3.62 | 2.32 | -35.91% | 23.40% |
BlackBuck Ltd. financial update (Q1 FY27)
Financial performance
- Revenue grew 42.2% YoY to ₹204.2 crore, while net revenue increased 25.2% YoY to ₹170.7 crore, reflecting strong business momentum.
- EBITDA increased 23.1% YoY to ₹49.7 crore, although EBITDA margin declined 378 bps to 24.35%, reflecting higher direct costs and operating investments.
- PAT stood at ₹42.2 crore, down from ₹65.7 crore in Q4 FY26, primarily due to the previous quarter’s tax benefit.
- Core businesses, comprising tolling and telematics, grew 20.7% YoY to ₹150 crore, while growth businesses expanded 152.6% YoY to ₹58.9 crore, led by Super Loads.
- Adjusted EPS stood at ₹2.32, compared with ₹1.88 in Q1 FY26, reflecting an improvement in earnings per share.
Business highlights
- Monthly transacting truck operators increased 12.8% YoY to approximately 883,000, while customers using two or more services grew around 19%, indicating deeper platform engagement.
- Telematics gained traction through sales of new AIS, non-AIS and specialised tracking devices, creating a pipeline for recurring subscription revenue.
- Super Loads scaled rapidly, with volumes increasing 50% QoQ and operations expanding to 14 cities, including four mature markets and 10 newer locations.
- AI adoption improved operating efficiency, reducing manpower requirements in KYC workflows by approximately 85% and operating costs by 65–70%.
- Tolling activity faced near-term pressure, with transactions declining 3% QoQ and gross transaction value (GTV) falling 1% QoQ, amid weaker freight movement in April.
Outlook
- Net revenue projected at ₹819 crore in FY27 and ₹1,062 crore in FY28, supported by core business growth and the scaling of newer businesses.
- EBITDA margin is projected to improve from 25.6% in FY26 to 27.0% in FY27 and 30.6% in FY28, driven by operating leverage and a higher contribution from recurring telematics subscriptions.
- Tolling growth is expected to recover from Q2 FY27 as freight activity normalises, while telematics device sales and subscription renewals should support recurring revenues.
- Super Loads remains a key growth driver, with management targeting approximately 5,000 loads per month per hub as the threshold for stronger network effects, customer retention and margin expansion.
- The vehicle finance business remains on track to achieve profitability by the end of FY27, while continued AI-led automation could improve productivity and operating efficiency.
Recent Updates on BlackBuck Ltd.
- FY26 Annual Report: The company highlighted its focus on strengthening core businesses while investing selectively in growth opportunities.
- SuperLoads Expansion: Management identified expansion into new geographies and productivity improvements in existing markets as key priorities.
- Telematics Momentum: The company reported record quarterly sales of new telematics devices in its FY27 Q1 investor presentation, supporting its focus on fleet digitisation.
- Vehicle Finance Development: BlackBuck Finserve continues to focus on scaling its lending business while moving towards sustainable profitability.
- Corporate Governance Disclosures: BlackBuck published its FY26 Annual Report and Business Responsibility and Sustainability Report in August 2026.
Company valuation insights – BlackBuck Ltd.
BlackBuck is currently trading at a TTM P/E of 63.5x, above the industry average of 46.5x. The stock has delivered a 3.8% return over the last six months, outperforming the NIFTY 50’s -5.6%, reflecting relative resilience amid market weakness.
The investment thesis is supported by strong growth in digital freight solutions, expanding telematics adoption, scaling of new businesses and potential operating leverage. In Q1FY27, revenue grew 42.2% YoY to ₹204.2 crore, while core businesses comprising tolling and telematics grew 20.7% YoY. Monthly transacting truck operators increased 12.8% YoY to approximately 883,000, highlighting continued platform adoption. Telematics device sales across AIS, non-AIS and specialised trackers are expected to drive future subscription revenue, supported by attractive renewal rates. Meanwhile, Super Loads expanded into 14 cities, with volumes increasing 50% QoQ, creating an additional growth avenue. AI-led automation is also improving operating efficiency, while the vehicle finance business is expected to achieve profitability by the end of FY27. ICICI Securities expects net revenue to grow from ₹652 crore in FY26 to ₹1,062 crore in FY28, alongside EBITDA margin expansion from 25.6% to 30.6%, supported by subscription growth, scaling of new businesses and operating leverage.
We value BlackBuck at 49x FY28E EPS of ₹15, arriving at a 12-month target price of ₹735, implying an upside potential of 24% from current levels. While the stock trades at a premium to industry valuations, its growth potential is supported by increasing digital adoption in freight logistics, recurring telematics revenue and the scaling of Super Loads. For the near term, we maintain a 3-month target price of ₹630, implying a 6% upside potential from current levels.
Major risk factors for BlackBuck Ltd.
- Competition Risk: Competition from digital freight platforms, payment providers and telematics companies could constrain market share and monetisation.
- Growth Investment Risk: Higher spending on SuperLoads and other expansion initiatives may delay profitability improvements.
- Credit Risk: Defaults and deterioration in asset quality within vehicle financing could increase credit costs.
- Customer Concentration and Engagement Risk: Weak retention or limited adoption of multiple services could constrain revenue per customer.
- Regulatory and Technology Risk: Changes in payments or lending regulations, cybersecurity incidents and service disruptions could affect operations and customer trust.
Technical analysis of BlackBuck Ltd. share
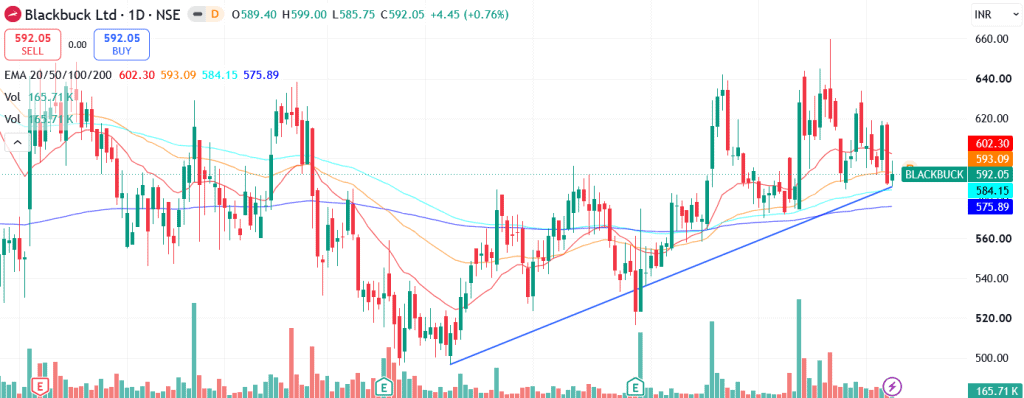
BlackBuck remains in an uptrend, with the stock trading above its 20-day, 50-day and 100-day EMAs, indicating a positive underlying price structure. A sustained move above ₹630, the key resistance level, could strengthen bullish momentum and pave the way towards ₹735, our 12-month fundamental target.
Momentum indicators remain mixed but show potential for improvement. The MACD at 1.18 is in positive territory but remains below its signal line, with a bullish crossover awaited to confirm renewed momentum. The RSI at 47.02 indicates decent buying interest, although the stock has yet to cross the bullish threshold of 50. The 21-day and 55-day Relative RSI readings of 0.08 and 0.13, respectively, indicate outperformance against the benchmarks.
Trend strength is moderate, with the ADX at 25.02, indicating an established trend. A bullish MACD crossover followed by a sustained breakout above ₹630 could strengthen the technical setup and support a move towards ₹735. On the downside, ₹560 remains the key support and stop-loss level.
- RSI: 47.02 (Decent buying interest)
- ADX: 25.02 (Established trend)
- MACD: 1.18 (Positive; below signal line, crossover awaited)
- Resistance: ₹630
- Support: ₹560
BlackBuck Ltd. stock recommendation
Current Stance: Buy, with a 3-month target price of ₹630 (6% upside) and a 12-month target price of ₹735 (24% upside), based on 49x FY28E EPS of ₹15.

Why buy now?

Strong business growth: Q1FY27 revenue grew 42.2% YoY to ₹204.2 crore, supported by growth across BlackBuck’s digital freight platform and newer businesses.

Increasing platform adoption: Monthly transacting truck operators grew 12.8% YoY to approximately 883,000, while greater adoption of multiple services indicates deeper customer engagement.

Recurring revenue opportunity: Telematics expansion across AIS, non-AIS and specialised tracking devices offers potential for higher subscription revenue and improved revenue visibility.

Scaling growth businesses: Super Loads volumes increased 50% QoQ, with operations expanding to 14 cities, creating an additional growth driver beyond core tolling and telematics.

Improving profitability potential: We expect net revenue to reach ₹1,062 crore in FY28, with EBITDA margin expanding to 30.6%, supported by operating leverage, subscription growth and scaling of newer businesses.

Portfolio fit

BlackBuck provides exposure to India’s digital freight ecosystem through its technology-led platform, tolling solutions and telematics services. Its expanding base of transacting truck operators, growing recurring subscription opportunity and scaling of Super Loads offer multiple avenues for long-term growth. While the premium valuation and execution risks in newer businesses warrant monitoring, improving operating leverage and AI-led efficiencies could support profitability as the platform scales.
If you found this helpful and want regular stock trade calls, check out my community on StockGro here:BlackBuck Ltd.: Budget 2026-27 opportunities
- Higher Infrastructure Spending: The Union Budget’s ₹12.2 lakh crore public capital expenditure allocation could support freight activity as infrastructure projects progress.
- Dedicated Freight Corridors: Expanded freight connectivity may create opportunities for trucking platforms to serve first-mile and last-mile transportation requirements.
- National Waterways Expansion: The proposed operationalisation of 20 new national waterways over five years could encourage multimodal logistics and increase demand for road-linked cargo movement.
- Manufacturing and Industrial Growth: Policy support for manufacturing and industrial clusters could increase freight volumes and the need for efficient truck utilisation.
- MSME Formalisation and Digital Adoption: Measures supporting small businesses could indirectly encourage greater use of digital payments, vehicle tracking and freight-discovery services.
Final thoughts
BlackBuck stands at an important stage in its evolution, transitioning from a digital payments-led trucking platform towards a broader ecosystem spanning payments, telematics, freight discovery and vehicle financing. Its expanding customer base, increasing multi-service adoption and FY26 profitability milestones provide a foundation for its next phase of growth.
For investors seeking exposure to the digitisation of India’s logistics ecosystem, BlackBuck offers a combination of platform scalability and multiple monetisation opportunities. However, sustained growth in SuperLoads, customer retention, vehicle-finance asset quality, operating cash flow and the durability of profitability will remain critical. A valuation assessment is essential before drawing a conclusion on the stock’s investment attractiveness.