Agricultural productivity is becoming increasingly important as India seeks to improve farm yields, reduce crop losses and strengthen farmer incomes. Crop protection products play a critical role in addressing pest attacks, fungal diseases and weeds, making agrochemicals an essential component of modern farming.
Dhanuka Agritech Ltd. is positioned to benefit from this structural requirement through its portfolio of insecticides, fungicides, herbicides and specialised crop-protection solutions. Its growth strategy includes new product launches, manufacturing expansion, international market development and greater adoption of precision agriculture.
But does Dhanuka Agritech Ltd. offer a compelling case for long-term investors? Let’s delve deeper.
Stock overview
| Ticker | DHANUKA |
| Industry/Sector | Chemicals |
| CMP | 847.00 |
| Market Cap (₹ Cr.) | 3,709 |
| P/E | 13.88 (Vs Industry P/E of 23.74) |
| 52 W High/Low | 1470.00 / 820.00 |
| EPS (TTM) | 60.13 |
| Dividend Yield | 0.24% |
About Dhanuka Agritech Ltd.
Dhanuka Agritech Ltd. is an Indian agrochemical company headquartered in Gurugram, Haryana. It develops, manufactures and markets crop-protection products that help farmers manage insects, weeds and crop diseases.
The company operates through a broad distribution network serving farmers across agricultural markets in India. Its portfolio includes insecticides, fungicides, herbicides and other agricultural solutions, supported by collaborations, product registrations and research-led product development.
Dhanuka is also investing in manufacturing capabilities, international expansion and newer technologies such as precision spraying and drone-based agricultural applications. These initiatives provide opportunities to strengthen its product portfolio, improve market reach and diversify growth beyond established formulations.
Key business segments
Dhanuka Agritech Ltd. operates primarily in the following key business segments:
- Insecticides: Products designed to control insect pests across major crops.
- Fungicides: Solutions to manage fungal diseases and protect crop health.
- Herbicides: Products that control weeds and reduce crop-yield losses.
- Other Agricultural Solutions: Specialised crop-protection products and emerging agricultural technologies.
- International Business: Export opportunities and overseas expansion through product registrations and distribution partnerships.
Primary growth factors for Dhanuka Agritech Ltd.
Dhanuka Agritech Ltd. key growth drivers:
- New Product Launches: Innovative formulations and new active ingredients can expand the portfolio and improve market penetration.
- Manufacturing Expansion: Investment in additional production capacity can strengthen supply capabilities and support future growth.
- Precision Agriculture: Drone-based spraying and targeted application technologies can create opportunities beyond conventional agrochemicals.
- International Expansion: Overseas subsidiaries and product registrations can broaden market access and diversify revenue sources.
- Agricultural Demand Recovery: Favourable monsoons, improved farm incomes and stronger pest-management demand can support volume growth.
Detailed competition analysis for Dhanuka Agritech Ltd.
Key financial metrics – TTM;
| Company | Sales (₹ Cr.) | EBITDA (₹ Cr.) | EBITDA Margin (%) | PAT (₹ Cr.) | PAT Margin (%) | P/E |
| Dhanuka Agritech Ltd. | 1953.43 | 375.30 | 19.21% | 268.03 | 13.72% | 13.88 |
| UPL Ltd. | 52804.00 | 9326.00 | 17.66% | 2618.00 | 4.96% | 18.39 |
| PI Industries Ltd. | 6515.50 | 1547.90 | 23.76% | 1160.20 | 17.81% | 26.69 |
| Sumitomo Chemical India Ltd. | 3222.38 | 652.70 | 20.26% | 559.03 | 17.35% | 31.06 |
| Bayer CropScience Ltd. | 5595.40 | 892.90 | 15.96% | 732.10 | 13.08% | 20.79 |
Key insights on Dhanuka Agritech Ltd.
- Revenue Moderation: FY26 revenue from operations declined 0.75% year-on-year to ₹2,019.79 crore.
- Profitability Pressure: FY26 profit after tax declined 3.28% to ₹287.23 crore, highlighting the need for renewed earnings growth.
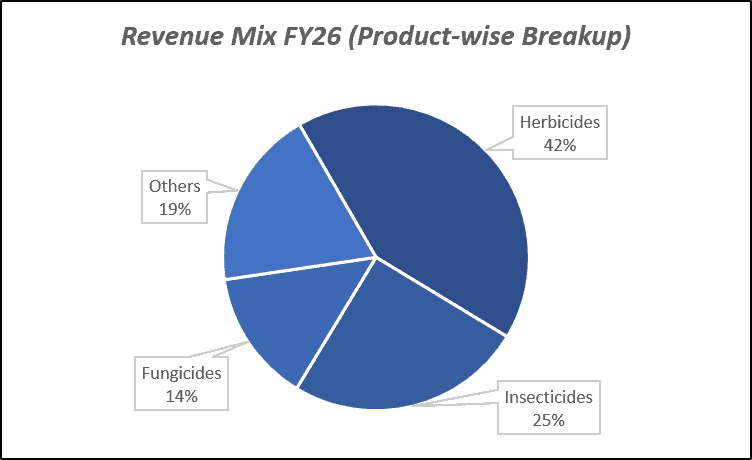
- Established Product Portfolio: In FY26, insecticides contributed approximately 35% of revenue, herbicides 31%, fungicides 19% and other products 15%.
- Margin Resilience: EBITDA margin remained close to 20% in FY26, although EBITDA declined year-on-year.
- Manufacturing Investment: The proposed Nagpur pesticide manufacturing unit, with an investment of up to ₹200 crore, could strengthen long-term production capabilities.
Recent financial performance of Dhanuka Agritech Ltd. for Q1 FY27
| Metric | Q1 FY26 | Q4 FY26 | Q1 FY27 | QoQ Growth (%) | YoY Growth (%) |
| Sales (₹ Cr.) | 528.29 | 483.34 | 461.93 | -4.43% | -12.56% |
| EBITDA (₹ Cr.) | 83.19 | 124.89 | 55.01 | -55.95% | -33.87% |
| EBITDA Margin (%) | 15.75% | 25.84% | 11.91% | -1393 bps | -384 bps |
| PAT (₹ Cr.) | 55.50 | 97.77 | 36.30 | -62.87% | -34.59% |
| PAT Margin (%) | 10.51% | 20.23% | 7.86% | -1237 bps | -265 bps |
| Adjusted EPS (₹) | 12.31 | 21.69 | 8.14 | -62.47% | -33.87% |
Dhanuka Agritech Ltd. financial update (Q1 FY27)
Financial performance
- Revenue declined 12.56% YoY to ₹461.93 crore in Q1FY27, impacted by delayed monsoon onset, weak sowing activity and lower demand for herbicides across key agricultural markets.
- EBITDA declined 33.87% YoY to ₹55.01 crore, with EBITDA margin contracting 384 bps to 11.91%, reflecting lower volumes and limited pricing power amid elevated input costs.
- PAT declined 34.59% YoY to ₹36.30 crore, while PAT margin fell 265 bps to 7.86%, reflecting operating deleverage amid subdued demand.
- Herbicides, contributing 42% of revenue, faced pressure due to rainfall deficits in key soybean and cotton markets, while fungicides benefited from demand in horticulture crops.
- Adjusted EPS declined 33.87% YoY to ₹8.14, as weaker operating performance weighed on earnings.
Business highlights
- Monsoon impact: Rainfall deficits and delayed sowing across key states affected seasonal demand, particularly for herbicides.
- Product innovation: New products such as MYCORe SUPER and Verdor gained traction, supporting the innovation-led growth strategy.
- New launches: Five products are planned for launch in the coming months, including three fungicides, one herbicide and one liquid fertiliser.
- International expansion: Dhanuka is building distribution for Bayer-acquired products across global markets, including Brazil and Europe.
- Capacity expansion: A new automated formulation plant in Nagpur, with planned capacity of 23,000 tonnes annually, is expected to become operational by April 2028.
Outlook
- Modest growth: Management expects low single-digit revenue growth in FY27, with recovery dependent on seasonal demand.
- Seasonal recovery: Improved rainfall and sowing trends could support demand in subsequent quarters, although near-term conditions remain challenging.
- Biological products: Additional biological and nutrition product launches are expected to strengthen the portfolio and support growth.
- Manufacturing expansion: The Nagpur facility involves planned investment of up to ₹200 crore, with commissioning targeted for Q4 FY28.
- Strong financial position: A debt-free balance sheet and healthy cash generation provide flexibility for capacity expansion and selective acquisitions.
Recent Updates on Dhanuka Agritech Ltd.
- Nagpur Manufacturing Unit: Approved an investment of up to ₹200 crore to establish a pesticide manufacturing facility in Maharashtra.
- European Expansion: Incorporated a wholly owned subsidiary in Ireland to support its international business strategy.
- New Product Launches: Announced launches including Wetcit Neo, Fujita, Polin and Tembotrax, expanding its crop-protection offering.
- Share Buyback: Approved a buyback of up to 5 lakh equity shares at a maximum price of ₹1,400 per share, aggregating up to ₹70 crore.
- Shareholder Returns: Recommended a final dividend of ₹2 per equity share for FY26, subject to shareholder approval.
Company valuation insights – Dhanuka Agritech Ltd.
Dhanuka Agritech is currently trading at a TTM P/E of 13.88x, significantly below the industry average of 23.74x, indicating a valuation discount relative to its peers. While the company faced near-term pressure in Q1FY27 due to delayed monsoon onset, weak sowing activity and lower agrochemical demand, its established distribution network and long-standing farmer relationships provide a strong foundation for recovery.
The investment thesis is supported by Dhanuka Agritech’s strong domestic presence, diversified crop protection portfolio and focus on introducing innovative, premium agrochemical products. Its extensive distribution network reaches over 10 million farmers, supported by approximately 6,500 distributors and 80,000 retailers. New product launches, growing traction in biological and nutrition products, and the commercialisation of products acquired from Bayer provide additional growth opportunities. The planned Nagpur manufacturing facility and expansion into international markets could further strengthen its manufacturing capabilities and growth prospects, while its debt-free balance sheet provides financial flexibility to pursue strategic investments.
Using a valuation multiple of 14x FY28E EPS of ₹75, we arrive at a 12-month target price of ₹1,050, implying an upside potential of 24% from current levels. The valuation reflects the potential for demand recovery, continued product innovation, expansion of premium and biological product categories, and improved manufacturing capabilities. For the near term, we maintain a 3-month target price of ₹900, implying an upside potential of 6% from current levels.
Major risk factors for Dhanuka Agritech Ltd.
- Monsoon Risk: Erratic rainfall and unfavourable weather can affect crop conditions, farmer incomes and agrochemical demand.
- Regulatory Risk: Changes in pesticide regulations, product approvals or restrictions on active ingredients can affect sales.
- Competition Risk: Intense competition and pricing pressure from domestic and multinational agrochemical companies can compress margins.
- Raw-Material Risk: Dependence on chemical intermediates and imported inputs exposes the company to price and supply-chain volatility.
- Execution Risk: Delays in manufacturing expansion, new-product adoption or overseas growth can postpone expected returns.
Technical analysis of Dhanuka Agritech Ltd. share
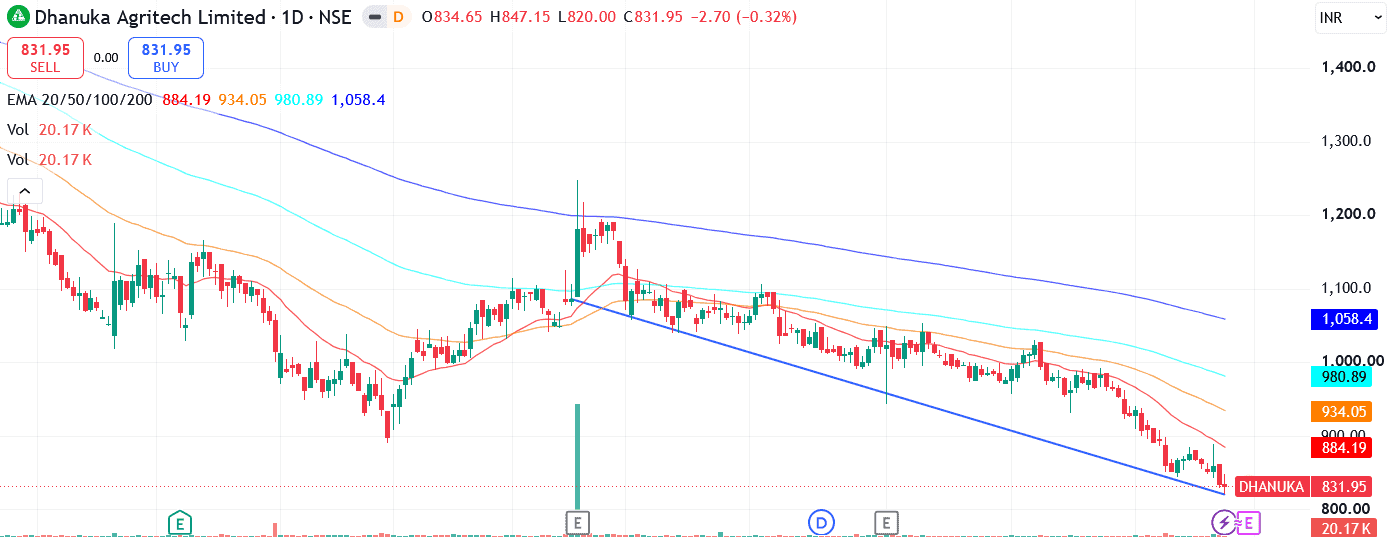
Dhanuka Agritech has corrected meaningfully and is trading near its 52-week low, presenting a potential entry opportunity for investors looking to benefit from a recovery. However, the stock remains below all its key EMAs, indicating continued weakness in the underlying price structure. A sustained move above ₹900 could signal improving momentum and pave the way towards ₹1,050, our 12-month fundamental target.
Momentum indicators remain weak but suggest the stock is deeply oversold. The MACD at -32.67 remains in negative territory and just below its signal line, with a bullish crossover awaited to confirm a potential reversal. The RSI at 25.69 is in the oversold region, increasing the possibility of a technical bounce. However, the 21-day and 55-day Relative RSI readings of -0.13 and -0.10, respectively, indicate continued underperformance against the benchmarks.
Trend strength remains elevated, with the ADX at 44.90, indicating a strong prevailing downtrend. However, as the stock approaches an important support zone, the downtrend could gradually lose strength, creating scope for a recovery. A sustained move above ₹900, supported by improving momentum, could open the way towards ₹1,050. On the downside, ₹800 remains the key support and stop-loss level.
- RSI: 25.69 (Oversold)
- ADX: 44.90 (Strong downtrend; potential weakening could support a bounce)
- MACD: -32.67 (Negative; below signal line, crossover awaited)
- Resistance: ₹900
- Support: ₹800
Dhanuka Agritech Ltd. stock recommendation
Current Stance: Buy, with a 3-month target price of ₹900 (6% upside) and a 12-month target price of ₹1,050 (24% upside), based on a valuation of 14x FY28E EPS of ₹75.

Why buy now?

Attractive valuation: Dhanuka trades at a TTM P/E of 13.88x, below the industry average of 23.74x.

Strong distribution network: Reaches over 10 million farmers through approximately 6,500 distributors and 80,000 retailers.

Product innovation: New product launches and premium agrochemical formulations provide opportunities for growth and margin improvement.

Expansion in biologicals: Growing traction in biological and nutrition products offers additional growth avenues.

Capacity expansion: The planned Nagpur facility and international expansion could strengthen manufacturing capabilities and broaden market reach.

Portfolio fit

Dhanuka Agritech offers exposure to India's crop protection industry through its established distribution network, innovative product portfolio and expansion into biologicals. A potential recovery in seasonal demand, new manufacturing capacity and international opportunities provide long-term growth prospects, while monsoon conditions and input costs remain key monitorables.
If you found this helpful and want regular stock trade calls, check out my community on StockGro here:Dhanuka Agritech Ltd.: Budget 2026-27 opportunities
- Agricultural Development Spending: The Ministry of Agriculture and Farmers Welfare received an allocation of ₹1.41 lakh crore, potentially supporting agricultural development and farm productivity.
- Rashtriya Krishi Vikas Yojana: The allocation increased to ₹8,550 crore, creating a potential indirect tailwind for agricultural productivity initiatives.
- Namo Drone Didi: The ₹677 crore allocation could support agricultural drone adoption and precision application services.
- High-Value Agriculture: The ₹350 crore allocation for high-value agriculture could create opportunities in specialised crop-protection solutions for selected crops.
- Agricultural Research: The ₹9,967 crore allocation for agricultural education and research could support innovation and the longer-term development of improved crop-protection technologies.
Final thoughts
Dhanuka Agritech offers exposure to India’s crop-protection market through an established product portfolio, a broad distribution network and investments in manufacturing and agricultural technology. New product launches and international expansion provide additional avenues for growth as the company seeks to strengthen its position in the agrochemical value chain.
For investors evaluating Dhanuka, the focus should be on a recovery in revenue growth, the sustainability of margins, successful execution of the Nagpur investment and the commercial contribution of new products. Monsoon conditions, regulatory developments, raw-material costs and capital-allocation decisions will remain key monitorables. A valuation assessment is essential before determining whether the stock offers an attractive investment opportunity.