India’s manufacturing ambitions are creating demand for advanced machine tools capable of producing complex components with greater accuracy, speed and consistency. CNC machines are essential across aerospace, defence, automotive, electronics, medical equipment and general engineering, making them a critical part of the industrial supply chain.
Jyoti CNC Automation Ltd. is positioning itself to benefit from this shift through a broad portfolio of CNC turning centres, milling machines, multi-axis systems and advanced machining solutions. Its French subsidiary, Huron, strengthens its presence in high-precision engineering, particularly aerospace and industrial applications.
The investment thesis rests on three themes: increasing demand for high-end CNC machines, expansion into aerospace and defence, and entry into electronics manufacturing services (EMS). Government support for domestic manufacturing and the company’s investment in backward integration could provide additional growth opportunities. The key challenge is to convert its growing order book into profitable revenue while managing working capital and executing its capacity expansion.
But does Jyoti CNC Automation Ltd. offer a compelling case for long-term investors? Let’s delve deeper.
Stock overview
| Ticker | JYOTICNC |
| Industry/Sector | Capital Goods |
| CMP | 922.00 |
| Market Cap (₹ Cr.) | 21,064 |
| P/E | 63.93 (Vs Industry P/E of 41.45) |
| 52 W High/Low | 1134.60 / 580.10 |
| EPS (TTM) | 14.15 |
| Dividend Yield | 0.00% |
About Jyoti CNC Automation Ltd.
Jyoti CNC Automation Ltd., incorporated in 1989 and headquartered in Rajkot, Gujarat, is one of India’s leading manufacturers of computer numerical control (CNC) metal-cutting machines. The company designs, develops, manufactures and exports precision machine tools used in industrial production.
Its product portfolio includes CNC turning centres, vertical and horizontal machining centres, turn-mill centres, five-axis machines and multi-tasking systems. These products serve customers across aerospace, defence, automotive, electronics, general engineering, healthcare and other industrial sectors.
The company operates vertically integrated manufacturing facilities in India, supported by in-house machining, foundry, assembly and research capabilities. Its French subsidiary, Huron Graffenstaden SAS, provides access to advanced five-axis machining technology and established international customers.
Jyoti CNC is expanding its manufacturing capacity, developing in-house electronic components for CNC machines and targeting emerging sectors such as EMS. These initiatives could improve supply-chain control, increase product sophistication and strengthen its position in the global machine-tool industry.
Key business segments
Jyoti CNC Automation Ltd. operates primarily in the following key business segments:
- CNC Turning Centres: Precision machining of cylindrical components used in automotive and industrial applications.
- Vertical and Horizontal Machining Centres: Multi-purpose milling solutions for complex industrial components.
- Five-Axis and Multi-Tasking Machines: Advanced systems for high-precision aerospace, defence and engineering applications.
- Huron – International Operations: High-end machining solutions and established European engineering capabilities.
- Emerging EMS Applications: CNC machines for electronics and component manufacturing, including opportunities linked to semiconductor-related supply chains.
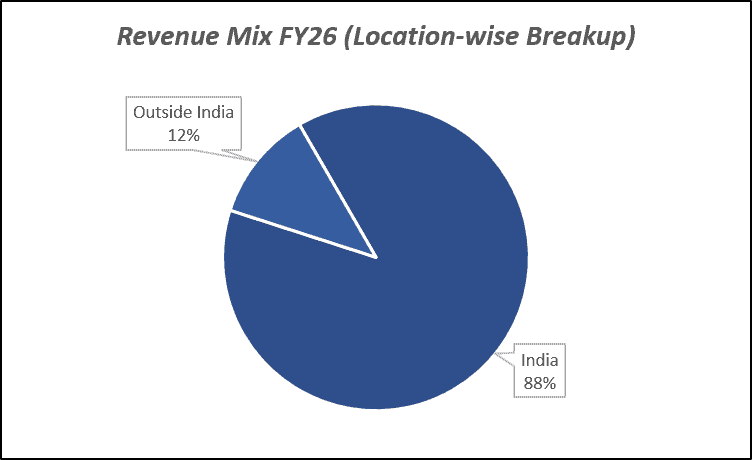
Primary growth factors for Jyoti CNC Automation Ltd.
Jyoti CNC Automation Ltd. key growth drivers:
- Aerospace and Defence: Rising defence procurement and demand for precision-engineered components can increase orders for high-end CNC machines.
- EMS and Electronics Manufacturing: Domestic electronics manufacturing expansion creates a potential new market for advanced machining equipment.
- Capacity Expansion: Increasing annual production capacity from 6,000 to 16,000 machines can support order execution and future growth.
- Backward Integration: Developing in-house CNC controllers, drives and motors can reduce import dependence and improve product economics.
- International Expansion: Huron’s technology capabilities and expanded European capacity can strengthen access to global aerospace and industrial customers.
Detailed competition analysis for Jyoti CNC Automation Ltd.
Key financial metrics – TTM;
| Company | Sales (₹ Cr.) | EBITDA (₹ Cr.) | EBITDA Margin (%) | PAT (₹ Cr.) | PAT Margin (%) | P/E |
| Jyoti CNC Automation Ltd. | 2191.43 | 535.37 | 24.43% | 321.72 | 14.68% | 63.93 |
| Triveni Turbine Ltd. | 2252.50 | 428.00 | 19.00% | 337.30 | 14.97% | 42.27 |
| Thermax Ltd. | 10839.35 | 869.78 | 8.02% | 590.83 | 5.45% | 64.21 |
| Honeywell Automation Ltd. | 4777.70 | 659.90 | 13.81% | 565.30 | 11.83% | 50.44 |
| Azad Engineering Ltd. | 638.48 | 240.45 | 37.66% | 139.29 | 21.82% | 118.05 |
Key insights on Jyoti CNC Automation Ltd.
- Strong FY26 Revenue Growth: Consolidated revenue from operations increased approximately 15% to ₹2,093 crore in FY26.
- Profitability Improvement: Consolidated profit after tax rose approximately 6% to ₹336 crore, indicating slower earnings growth than revenue growth.
- Healthy Order Visibility: The consolidated order book stood at approximately ₹4,848 crore as of June 30, 2026, equivalent to roughly 2.1 times FY26 revenue.
- High-End Product Opportunity: Aerospace and defence demand, together with Huron’s technology capabilities, provides scope to increase the contribution of higher-value machines.
- Capacity and Integration Investments: The company is expanding capacity and investing in in-house electronic components, with execution, utilisation and working-capital efficiency critical to returns.
Recent financial performance of Jyoti CNC Automation Ltd. for Q1 FY27
| Metric | Q1 FY26 | Q4 FY26 | Q1 FY27 | QoQ Growth (%) | YoY Growth (%) |
| Sales (₹ Cr.) | 410.17 | 599.16 | 508.47 | -15.14% | 23.97% |
| EBITDA (₹ Cr.) | 100.21 | 147.39 | 108.83 | -26.16% | 8.60% |
| EBITDA Margin (%) | 24.43% | 24.60% | 21.40% | -320 bps | -303 bps |
| PAT (₹ Cr.) | 71.42 | 90.57 | 57.14 | -36.91% | -19.99% |
| PAT Margin (%) | 17.41% | 15.12% | 11.24% | -388 bps | -617 bps |
| Adjusted EPS (₹) | 3.14 | 3.98 | 2.51 | -36.93% | -20.06% |
Jyoti CNC Automation Ltd. financial update (Q1 FY27)
Financial performance
- Revenue grew 23.97% YoY to ₹508.47 crore in Q1 FY27, supported by strong domestic demand, despite a 15.14% QoQ decline.
- EBITDA increased 8.60% YoY to ₹108.83 crore, while EBITDA margin declined 303 bps to 21.40%, impacted by Huron’s lower revenue recognition and forex losses.
- PAT declined 19.99% YoY to ₹57.14 crore, with PAT margin falling 617 bps to 11.24%.
- Huron’s delayed export licences and end-user certifications resulted in approximately ₹35 crore of revenue remaining unrecognised, affecting reported profitability.
- Adjusted EPS declined 20.06% YoY to ₹2.51, reflecting lower reported earnings.
Business highlights
- Order book: Strong order book of approximately ₹4,848 crore provides healthy revenue visibility.
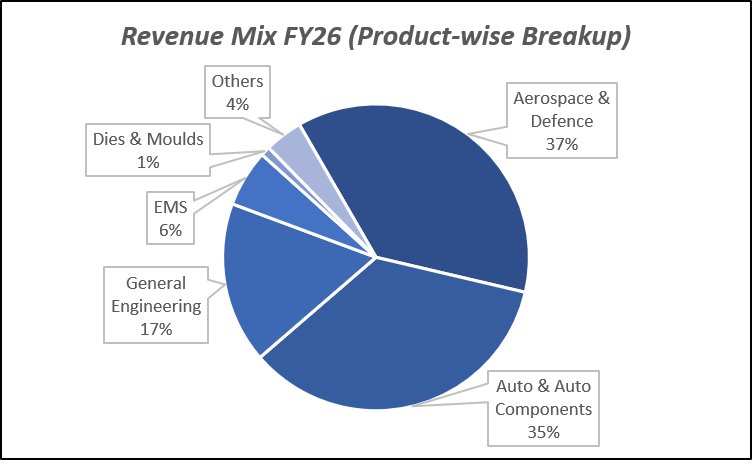
- Diversified demand: Aerospace and defence contributed 37% of revenue, followed by automotive at 35%, general engineering at 17% and EMS at 6%.
- Capacity expansion: New facility with ₹450 crore planned capex will add 10,000 machines of annual capacity.
- Product innovation: Launched the NX high-precision double-column machine targeting railway, infrastructure, power and heavy engineering.
- Technology development: Developing in-house CNC controllers, drives and motors, with controller commercialisation targeted over the next two years.
Outlook
- Growth guidance: Management reiterated FY27 revenue growth guidance of 25–30% and an EBITDA margin target of approximately 25%.
- Stronger H2: Second-half performance is expected to improve with higher capacity and better execution.
- Production ramp-up: Additional capacity is expected to support annual production of over 8,000 machines in FY27.
- Huron recovery: FY27 revenue is expected at ₹300–325 crore, with an EBITDA margin of 8–10%.
- Long-term growth: Import substitution, defence indigenisation, automation and replacement demand offer growth opportunities, while improved execution could support working capital efficiency.
Recent Updates on Jyoti CNC Automation Ltd.
- ECMS Approval: Received approval for a ₹1,020.65 crore investment under the ECMS, eligible for capital incentives of up to 25%.
- Rajkot Capacity Expansion: Plans to increase annual manufacturing capacity from 6,000 to 16,000 machines.
- Huron Facility Expansion: Expanded production capacity at its Strasbourg facility in France to strengthen international operations.
- Credit Rating: CRISIL assigned an A+/Stable rating, citing market position, order visibility and profitability.
- Rajkot Fire Incident: Issued a stock exchange clarification in September 2026 regarding a reported fire at its manufacturing facility.
Company valuation insights – Jyoti CNC Automation Ltd.
Jyoti CNC Automation is currently trading at a TTM P/E of 63.93x, significantly above the industry average of 41.45x, reflecting a valuation premium relative to its peers. The stock has delivered a 6-month return of 21.2%, outperforming the NIFTY 50’s decline of 5.57%, supported by strong demand for precision manufacturing equipment and the company’s growth prospects.
The investment thesis is supported by Jyoti CNC’s established position in the CNC machine tools industry and its exposure to structural growth in domestic manufacturing, aerospace and defence, automotive, general engineering and electronics manufacturing services. The company’s healthy order book provides revenue visibility, while capacity expansion at its Rajkot facility is expected to strengthen production capabilities and support higher execution. Its focus on advanced, high-precision machines, import substitution and in-house CNC controller development offers additional growth opportunities. Huron’s international presence further strengthens its global reach, while government initiatives such as Make in India, PLI schemes and defence indigenisation provide long-term industry tailwinds. However, execution, working capital requirements and delays in Huron’s export clearances remain key monitorables.
Using a valuation multiple of 46x FY28E EPS of ₹25, we arrive at a 12-month target price of ₹1,150, implying an upside potential of 24% from current levels. The valuation reflects the company’s growth potential, strong order visibility, capacity expansion and opportunities arising from manufacturing localisation and automation. For the near term, we maintain a 3-month target price of ₹980, implying an upside potential of 6% from current levels.
Major risk factors for Jyoti CNC Automation Ltd.
- Execution Risk: Delays in capacity expansion or order delivery can affect revenue conversion and customer commitments.
- Working-Capital Risk: Long manufacturing cycles and high inventory requirements can constrain operating cash flow and increase borrowing needs.
- Customer and Industry Concentration: Dependence on capital expenditure by aerospace, defence, automotive and industrial customers can make demand cyclical.
- Technology and Import Risk: Dependence on imported controllers, drives, motors and other components can expose the company to currency and supply-chain volatility.
- Regulatory and International Risk: Regulatory reviews involving overseas subsidiaries, including Huron, could create uncertainty around compliance, exports or future business if adverse developments arise.
Technical analysis of Jyoti CNC Automation Ltd. share
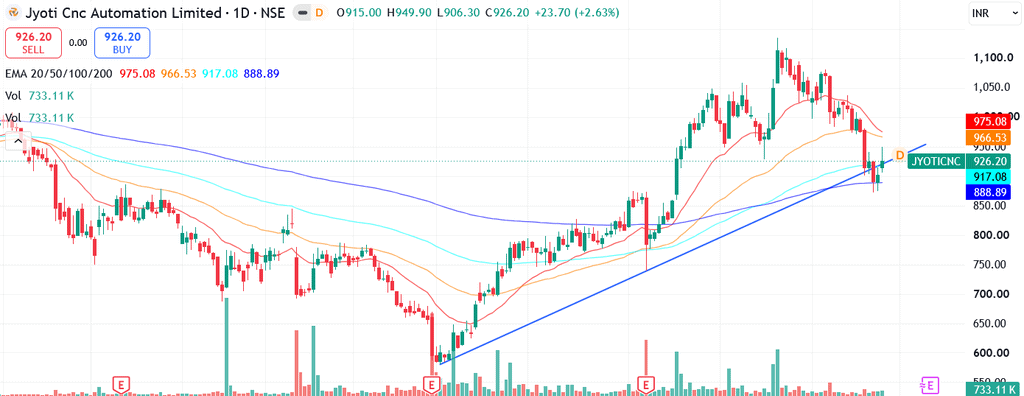
Jyoti CNC Automation has witnessed a recent correction after a sustained long-term uptrend and is trading near an important trend support zone, presenting a potential entry opportunity. The stock remains above its 100-day and 200-day EMAs, indicating that its broader long-term trend remains constructive despite near-term weakness. A sustained move above ₹980 could signal improving momentum and pave the way towards ₹1,150, our 12-month fundamental target.
Momentum indicators remain mixed. The MACD at -25.39 is in negative territory and below its signal line, with a bullish crossover awaited to confirm a potential reversal. The RSI at 40.79 indicates moderate buying interest, suggesting scope for momentum to improve. Meanwhile, the 21-day and 55-day Relative RSI readings of -0.12 and 0.16, respectively, indicate recent underperformance but longer-term outperformance against the benchmark.
The ADX at 27.12 indicates a strong prevailing downtrend in the near term. However, as the stock approaches an important trend support zone, the downtrend could gradually weaken, creating scope for a recovery. A sustained move above ₹980, supported by improving momentum, could open the way towards ₹1,150. On the downside, ₹825 remains the key support and stop-loss level.
- RSI: 40.79 (Moderate buying interest)
- ADX: 27.12 (Strong downtrend; potential weakening could support a bounce)
- MACD: -25.39 (Negative and below signal line; bullish crossover awaited)
- Resistance: ₹980
- Support: ₹825
Jyoti CNC Automation Ltd. stock recommendation
Current Stance: Buy, with a 3-month target price of ₹980 (6% upside) and a 12-month target price of ₹1,150 (24% upside).

Why buy now?

Strong order book: An order book of approximately ₹4,848 crore provides healthy revenue visibility across domestic and international markets.

Capacity expansion: The new Rajkot facility is expected to add annual capacity of 10,000 machines, supporting higher production and execution.

Manufacturing tailwinds: Make in India, defence indigenisation and import substitution create opportunities for domestic CNC machine manufacturers.

Diversified demand: Exposure to aerospace and defence, automotive, general engineering and electronics manufacturing services supports growth across industries.

Technology and global expansion: Advanced high-precision machines, in-house CNC controller development and Huron's international presence offer additional growth opportunities.

Portfolio fit

Jyoti CNC Automation offers exposure to India's manufacturing and automation growth through its CNC machine tools business, capacity expansion and diversified end-market presence. Rising demand for precision engineering, defence indigenisation and import substitution provides long-term growth potential, while execution, working capital requirements and delays in Huron's export clearances remain key monitorables.
If you found this helpful and want regular stock trade calls, check out my community on StockGro here:Jyoti CNC Automation Ltd.: Budget 2026-27 opportunities
- Public Capex: ₹12.2 lakh crore central capex allocation could boost infrastructure investment and machine-tool demand.
- Defence Manufacturing: ₹7.85 lakh crore defence allocation, including ₹1.39 lakh crore for domestic procurement, could drive precision-machining demand.
- ECMS: The ₹40,000 crore scheme and Jyoti CNC’s approved investment could strengthen domestic CNC-related electronics manufacturing.
- Capital Goods Modernisation: Government initiatives for high-tech tool rooms and capital goods could support domestic precision engineering.
- Semiconductor and EMS: Semiconductor Mission 2.0 and electronics manufacturing incentives could expand long-term demand for precision machinery.
Final thoughts
Jyoti CNC Automation is positioned at the intersection of precision engineering, domestic manufacturing and the increasing demand for advanced industrial machinery. Its diversified product portfolio, Huron’s technology capabilities, capacity expansion and entry into EMS provide multiple potential growth avenues.
For investors, the key monitorables are order-book conversion, capacity utilisation, the contribution of high-end machines, backward-integration progress and working-capital efficiency. Regulatory developments involving overseas operations and the returns generated by its expansion investments also warrant close attention. Valuation should be assessed against the sustainability of growth, profitability and cash generation before reaching an investment conclusion.