India’s banking sector is entering a phase where credit growth, deposit mobilisation, secured retail lending and improving asset quality are becoming increasingly important differentiators. Within the private banking space, RBL Bank is undergoing a transition from a relatively niche lender toward a more diversified banking franchise, with increasing emphasis on secured retail assets, commercial banking and granular deposits.
The bank’s recent performance reflects this transition. As of June 2026, advances stood at ₹1.16 lakh crore, up 23% YoY, while deposits grew 11% to ₹1.25 lakh crore. Asset quality also improved, with GNPA declining to 1.30% and NNPA to 0.37%.
But does RBL Bank Ltd. offer a compelling case for long-term investors? Let’s delve deeper.
Stock overview
| Ticker | RBLBANK |
| Industry/Sector | Financial Services |
| CMP | 407.95 |
| Market Cap (₹ Cr.) | 64,504 |
| P/B | 1.47 |
| 52 W High/Low | 420.40 / 261.60 |
| EPS (TTM) | 5.79 |
| Dividend Yield | 0.10% |
About RBL Bank Ltd.
RBL Bank is a private-sector bank with a diversified lending franchise spanning retail, commercial and wholesale banking. Historically known for its credit-card, microfinance and specialised lending businesses, the bank has been progressively rebalancing its portfolio toward secured retail assets and commercial banking.
The bank’s FY26 advances grew 23% YoY, while secured retail advances increased 36% YoY. Retail and wholesale advances represented a 59:41 mix at FY26-end, reflecting a relatively diversified balance sheet. Granular deposits also remained a strategic focus, with CASA plus term deposits below ₹3 crore accounting for 65% of total deposits at March 2026.
RBL Bank is also strengthening its capital and funding base, including through strategic investment by Emirates NBD and access to international debt markets. The strategic investment by Emirates NBD was completed in June 2026 following regulatory and governmental approvals.
Key business segments
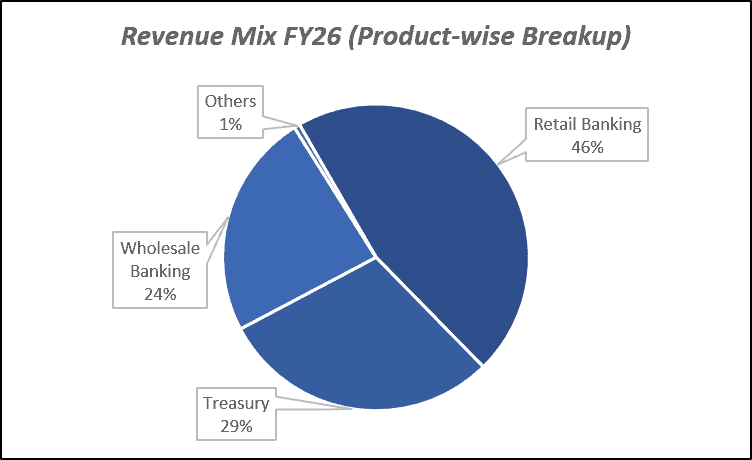
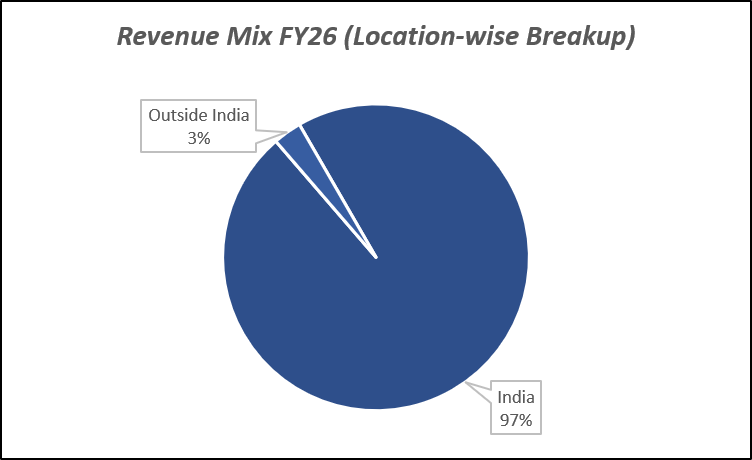
RBL Bank Ltd. operates primarily in the following key business segments:
- Retail Banking: Housing, personal loans, credit cards, deposits and other retail products.
- Commercial Banking: Lending to MSMEs and mid-sized businesses.
- Wholesale Banking: Corporate lending, structured finance and institutional relationships.
- Microfinance: Joint-liability and other financial-inclusion lending.
- Credit Cards: Consumer credit and card-based payment solutions.
- Treasury: Investment portfolio, liquidity management and market-related activities.
- Digital Banking: Digital payments, deposits, lending and technology-enabled customer services.
Primary growth factors for RBL Bank Ltd.
RBL Bank Ltd. key growth drivers:
- Secured Retail Expansion: Growing housing and other secured retail assets can improve portfolio quality and diversification.
- Commercial Banking: Expansion in MSME and mid-market lending can support faster credit growth.
- Granular Deposits: Higher retail and CASA deposits can strengthen the funding profile and reduce reliance on wholesale funding.
- Credit Card Franchise: A large card ecosystem provides opportunities for consumer lending and fee-income growth.
- Distribution Expansion: A wider branch and business-correspondent network can improve customer acquisition and cross-selling.
Detailed competition analysis for RBL Bank Ltd.
Key financial metrics – TTM;
| Company | NII (₹ Cr.) | PAT (₹ Cr.) | PAT Margin (%) | GNPA (%) | NNPA (%) | P/B |
| RBL Bank Ltd. | 6536.59 | 899.06 | 4.80% | 1.30% | 0.37% | 1.47 |
| Equitas Small Finance Bank Ltd. | 3635.01 | 510.45 | 6.27% | 2.42% | 0.71% | 1.35 |
| Bandhan Bank Ltd. | 10993.03 | 1353.27 | 5.53% | 3.15% | 0.93% | 1.09 |
| Karur Vysya Bank Ltd. | 5281.95 | 2744.58 | 20.13% | 0.74% | 0.19% | 2.27 |
| Ujjivan Small Finance Bank Ltd. | 4202.39 | 905.95 | 10.72% | 2.16% | 0.34% | 1.85 |
Key insights on RBL Bank Ltd.
- Strong Credit Growth: Advances increased 23% YoY to ₹1.16 lakh crore as of June 2026.
- Secured Portfolio Growth: Secured retail advances grew 36% YoY in FY26, supporting portfolio diversification.
- Improving Asset Quality: GNPA/NNPA improved to 1.30%/0.37% in Q1 FY27.
- Granular Liability Focus: CASA plus deposits below ₹3 crore accounted for 65% of total deposits at FY26-end.
- Improving Profitability: Q1 FY27 PAT increased 9% YoY to ₹234 crore, while RoA stood at 0.57%.
- Lower Credit Costs: Credit cost declined to 54 bps in Q1 FY27 versus 235 bps for FY26.
- Capital Strength: CRAR stood at 33.28% as of June 2026, providing substantial capital headroom for growth.
- Distribution Reach: The bank had 1,942 total touchpoints at March 2026, including 603 branches and 1,339 business-correspondent branches.
Recent financial performance of RBL Bank Ltd. for Q1 FY27
| Metric | Q1 FY26 | Q4 FY26 | Q1 FY27 | QoQ Growth (%) | YoY Growth (%) |
| NII (₹ Cr.) | 1480.75 | 1672.07 | 1655.25 | -1.01% | 11.78% |
| PAT (₹ Cr.) | 214.22 | 244.42 | 234.23 | -4.17% | 9.34% |
| PAT Margin (%) | 4.75% | 5.10% | 4.92% | -18 bps | 17 bps |
| GNPA (%) | 2.78% | 1.45% | 1.30% | -15 bps | -148 bps |
| NNPA (%) | 0.45% | 0.39% | 0.37% | -2 bps | -8 bps |
| Adjusted EPS (₹) | 3.52 | 3.95 | 1.51 | -61.77% | -57.10% |
RBL Bank Ltd. financial update (Q1 FY27)
Financial performance
- Net Interest Income (NII): NII grew 11.78% YoY to ₹1,655 crore, although it declined 1.01% QoQ as NIM contracted during the quarter.
- Profit After Tax (PAT): PAT stood at ₹234 crore, increasing 9.34% YoY but declining 4.17% QoQ, reflecting pressure from lower NIM and elevated credit costs.
- Operating Performance: Operating profit increased 31.3% YoY to ₹923 crore, supported by a sharp 8.5% YoY decline in other operating expenses.
- Asset Quality: GNPA improved to 1.30% from 1.45% QoQ, while NNPA declined to 0.37% from 0.39%, indicating continued asset-quality improvement.
- NIM Pressure: NIM contracted by 28 bps QoQ as the cost of deposits increased; the sell-side report expects a potential 30-40 bps NIM recovery in the near term.
Business highlights
- Strong Loan Growth: Advances grew 23.1% YoY to ₹1.16 lakh crore, led by 38% growth in wholesale and 18% growth in secured retail advances.
- Wholesale Expansion: Wholesale advances grew 38.3% YoY, with C&IB and commercial banking growing 39.4% and 34.1%, respectively.
- Business Loans: Business loans grew 47.4% YoY to ₹17,184 crore, strengthening the bank’s commercial and MSME franchise.
- Credit Card Stress: Credit-card slippages remained elevated at ₹739 crore, with annualised slippage rising to 15.3%; management expects improvement during H2 FY27.
- MFI Improvement: MFI slippages moderated to ₹57 crore, with annualised slippage falling to 2.8%, while MFI GNPA improved to 3.7%.
Outlook
- Credit Growth: Strong loan growth is expected to remain a key driver, with wholesale and secured retail lending continuing to lead the portfolio.
- NIM Recovery: Management expects a 30-40 bps improvement in NIM in the near term as funding costs moderate.
- Credit Card Normalisation: Credit-card stress is expected to moderate in Q2 and improve more materially during H2 FY27.
- Liability Franchise: The Emirates NBD transaction has significantly strengthened capital, with CET1 rising to 33.3%, while the bank expects opportunities to improve its retail liability franchise over the next 1-2 years.
- Profitability Improvement: The sell-side report expects RoA to improve as NIM recovers, credit costs moderate and operating leverage strengthens. Its FY27/FY28 estimates are 0.9%/1.3% RoA.
Recent Updates on RBL Bank Ltd.
- Emirates NBD Investment: Strategic investment by Emirates NBD was completed in June 2026 following regulatory approvals.
- International Funding: RBL Bank approved a $350 million five-year senior unsecured notes issuance under its EMTN programme in September 2026.
- Credit Rating: Moody’s assigned RBL Bank a Baa2 long-term issuer rating in July 2026, while CRISIL assigned a AAA/Stable rating to specified debt instruments.
- Credit Card Expansion: RBL Bank and Shoppers Stop launched three-tier co-branded credit cards, strengthening the consumer-credit franchise.
- Branch Expansion: The bank crossed the 600-branch milestone after adding 23 branches in March 2026.
Company valuation insights – RBL Bank Ltd.
RBL Bank is currently trading at a P/B of 1.47x, while the stock has delivered a 51.3% return over the last one year, compared with a 7.4% decline in the NIFTY 50, reflecting a significant improvement in market sentiment as the bank progresses through its balance-sheet and business transformation.
The investment thesis is supported by strong loan growth, improving asset quality, capital strengthening and potential profitability recovery. Advances grew 23% YoY in Q1 FY27, led by 38% growth in wholesale and 18% growth in secured retail lending. At the same time, GNPA/NNPA improved to 1.30%/0.37%. The bank’s capital position has strengthened materially following the Emirates NBD transaction, with CET1 rising to 33.3%. The sell-side report also highlights the potential for a 30–40 bps NIM recovery, improving credit-card asset quality in H2 FY27, stronger retail liability franchise and operating leverage to drive RoA recovery. Business loans grew 47% YoY, while wholesale advances increased 38%, providing additional avenues for balance-sheet expansion.
We value RBL Bank at 1.4x FY28E BVPS, arriving at a 12-month target price of ₹508, implying an upside potential of 24% from current levels. The valuation is supported by the potential for improving RoA and RoE, lower credit costs, NIM recovery, stronger liability franchise and operating leverage as the transformation progresses. For the near term, we maintain a 3-month technical target of ₹434, implying an upside potential of 6% from current levels.
Major risk factors for RBL Bank Ltd.
- Asset Quality Risk: Stress in unsecured, microfinance or consumer portfolios can increase credit costs.
- Funding Risk: Competition for retail deposits can pressure funding costs and margins.
- Credit Card Risk: Consumer-credit stress can impact delinquencies and provisions.
- Execution Risk: Rapid expansion across secured retail and commercial banking requires disciplined underwriting.
- Competition: Larger private banks and NBFCs can intensify competition for quality borrowers and deposits.
Technical analysis of RBL Bank Ltd. share
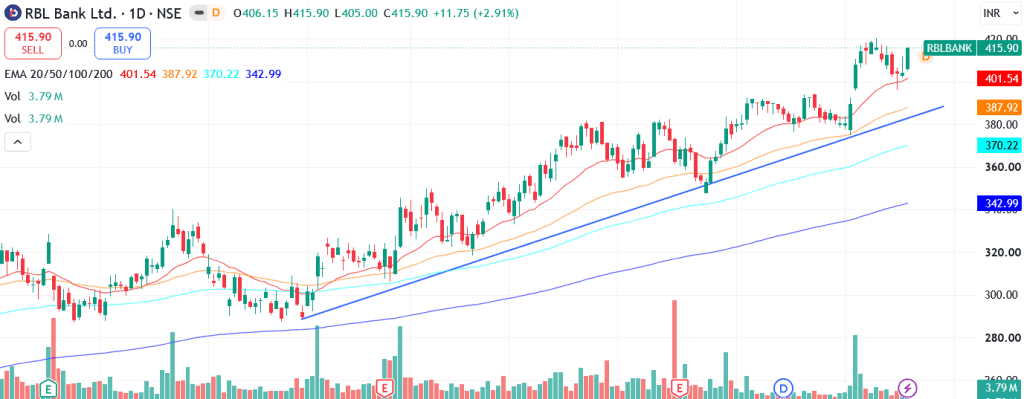
RBL Bank remains in a long-term uptrend, with the stock trading above all its key EMAs, indicating a strong underlying price structure. The sustained position above the short-, medium- and long-term moving averages suggests that the broader trend remains constructive, with the stock maintaining its upward trajectory.
Momentum indicators remain supportive. The MACD at 7.68 is positive and trading above its signal line, indicating sustained bullish momentum. The RSI at 65.39 reflects good buying interest, while remaining below the traditionally overbought zone. Additionally, the 21-day and 55-day Relative RSI at 0.12 and 0.21, respectively, indicate strong outperformance against the broader benchmarks.
Trend strength also remains healthy, with the ADX at 24.59, suggesting that the prevailing trend has meaningful strength. A sustained move above ₹434 could reinforce the bullish setup and potentially pave the way towards our ₹508 12-month fundamental target. On the downside, ₹380 remains the key support and stop-loss level.
- RSI: 65.39 (Good buying interest)
- ADX: 24.59 (Strong trend)
- MACD: 7.68 (Positive; above signal line)
- Resistance: ₹434
- Support: ₹380
RBL Bank Ltd. stock recommendation
Current Stance: Current Stance: Buy, with a 3-month target price of ₹434 (6% upside) and a 12-month target price of ₹508 (24% upside), based on a valuation of 1.4x FY28E BVPS.

Why buy now?

Strong Loan Growth: Advances grew 23% YoY to ₹1.16 lakh crore, led by 38% growth in wholesale and 18% growth in secured retail lending.

Improving Asset Quality: GNPA/NNPA improved to 1.30%/0.37%, while MFI stress moderated significantly, supporting gradual credit-cost normalisation.

Portfolio Diversification: Business loans grew 47% YoY, while C&IB and commercial banking grew 39% and 34%, respectively, strengthening the bank’s diversified lending franchise.

Capital & Liability Strength: The Emirates NBD transaction lifted CET1 to 33.3%, while stronger parentage and funding access provide scope to strengthen the retail liability franchise.

Profitability Recovery: Management expects a 30-40 bps NIM recovery and significant improvement in credit-card stress in H2 FY27, creating scope for higher RoA through margin recovery and operating leverage.

Portfolio fit

RBL Bank offers exposure to India's structural credit growth through a diversified private banking franchise spanning wholesale, commercial and secured retail lending. With strong growth in advances, improving asset quality, substantial capital headroom and a growing business-loan franchise, the bank has multiple avenues for balance-sheet expansion. A potential recovery in NIMs, moderation in credit-card stress and operating leverage could further support improvement in profitability and return ratios over the medium to long term.
If you found this helpful and want regular stock trade calls, check out my community on StockGro here:RBL Bank Ltd.: Budget 2026-27 opportunities
- MSME Credit: Continued policy support for MSMEs can expand demand for working capital and business loans.
- Housing Growth: Infrastructure and affordable-housing initiatives can support secured retail lending.
- Consumerisation: Rising incomes and formalisation can support credit-card and consumer-finance penetration.
- Financial Inclusion: Greater formal credit penetration can expand the addressable market in underserved segments.
- Digital Banking: Increasing digital adoption can improve customer acquisition, transaction volumes and cross-selling.
Final thoughts
RBL Bank stands at an important inflection point, evolving from a specialised lending franchise into a more diversified private-sector bank. Strong credit growth, expanding secured retail assets, improving asset quality and substantial capital headroom provide multiple avenues for the next phase of growth.
For investors seeking exposure to India’s mid-sized private banking opportunity, the bank offers a combination of balance-sheet expansion, portfolio diversification and potential profitability improvement. Sustaining asset-quality gains, strengthening deposits, controlling credit costs and translating growth into higher RoA and RoE will remain the key factors to monitor.