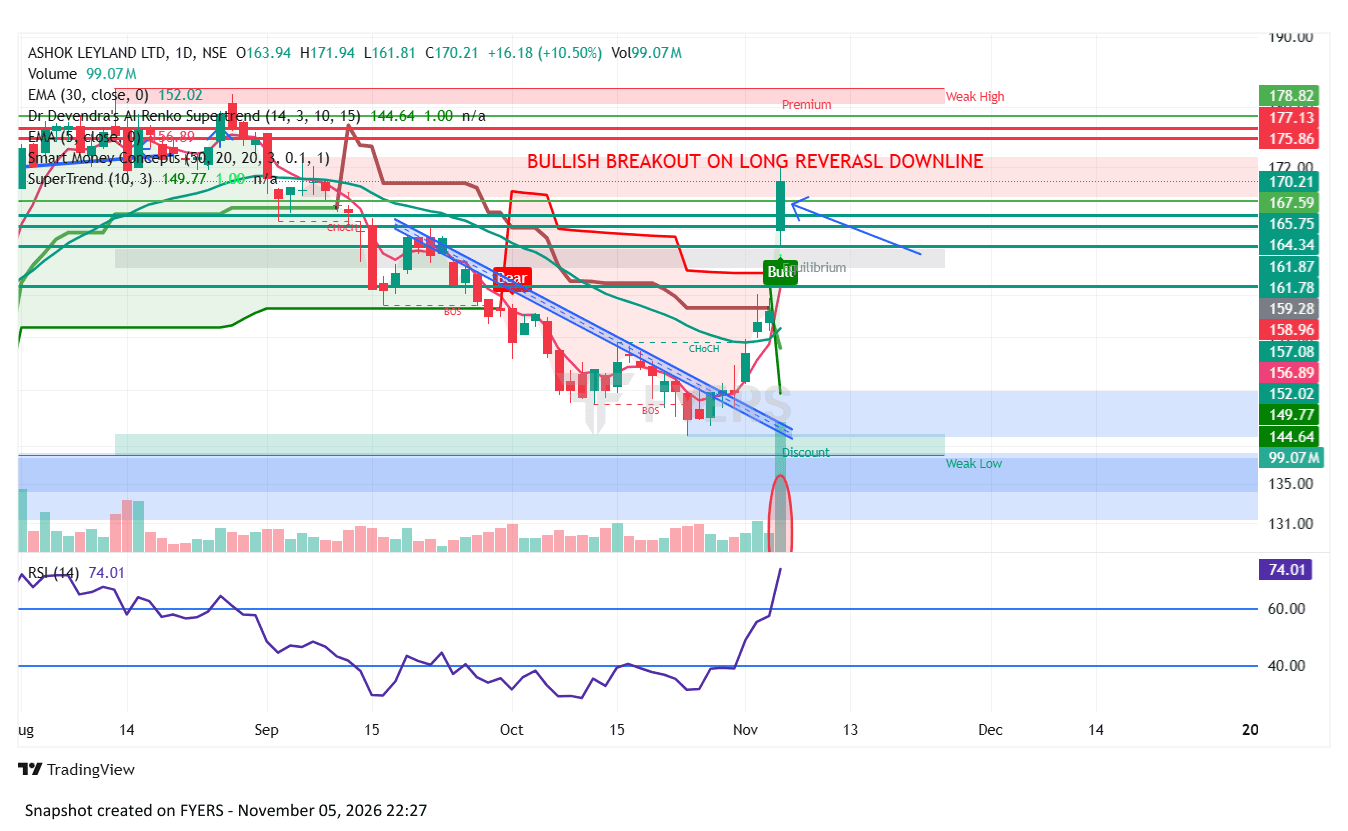
Ashok Leyland Limited (NSE: ASHOKLEY) – SWOT Analysis
ASHOKLEY Strengths - Strong market position: One of India's leading manufacturers of medium and heavy commercial vehicles. - Established brand: Strong reputation in trucks, buses and commercial transportation. - Diversified portfolio: Presence in heavy trucks, buses, LCVs, defence vehicles and power solutions. - Strong FY26 performance: Standalone revenue increased 14% to ₹44,007 crore. - Record profitability: FY26 standalone EBITDA reached ₹5,732 crore, with a 13% EBITDA margin. - Strong cash position: Standalone net cash increased to ₹5,899 crore at March 2026. - Export growth: FY26 export volumes increased 18.5% to 18,082 vehicles. 2. Weaknesses - Cyclical business: Commercial vehicle demand depends on economic growth, infrastructure and freight activity. - High capital requirements: Manufacturing plants, technology development and EV expansion require substantial investment. - Raw material exposure: Steel, aluminium, rubber and other input costs affect margins. - Competitive pressure: Faces competition from Tata Motors, VE Commercial Vehicles and other manufacturers. - EV transition costs: Electric vehicle development and infrastructure require continuous investment. 3. Opportunities - Growing infrastructure and road construction in India. - Increasing demand for heavy trucks and commercial transportation. - Government spending on defence vehicles. - Expansion of electric buses and electric LCVs. - Increasing demand for logistics and fleet modernisation. - Export opportunities in Africa, the Middle East and Southeast Asia. 4. Threats - Economic slowdown affecting commercial vehicle demand. - Competition from Tata Motors and other domestic and global manufacturers. - Rising steel, aluminium and energy prices. - Changes in emission norms and regulatory requirements. - Interest-rate increases affecting vehicle financing. - EV adoption could require significant changes in existing manufacturing operations.