‹ All Posts
AASHISH RA

3rd Oct · SEBI Registration INH000013174

bed & bath linen, rugs, flooring and advanced textiles
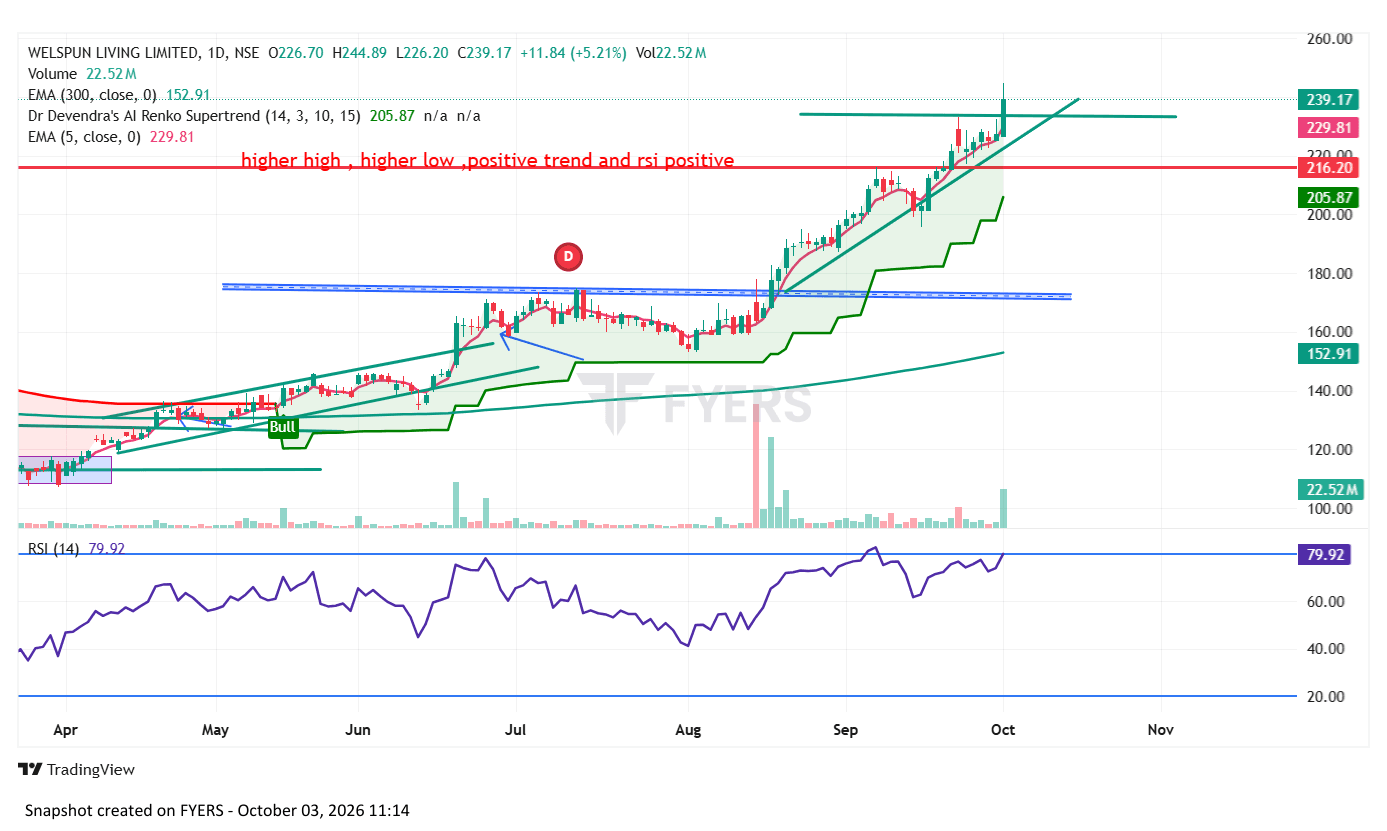
WELSPUNLIV
Strengths Strong global position in home textiles, particularly towels and bed/bath products. Large export-oriented manufacturing base with established international customers. Welspun brand has a significant domestic distribution network; the company described it as the most widely distributed home-textile brand in India in its Q3 FY26 release. Diversification into advanced/technical textiles and flooring. Innovation contributed around 22% of Q3 FY26 business, supporting product diversification. Q1 FY27 showed a significant improvement in revenue and profitability. Weaknesses Earnings remain sensitive to global home-textile demand and consumer spending. FY26 consolidated revenue declined approximately 6.6%, while EBITDA fell substantially versus FY25. Textile manufacturing is exposed to cotton, energy, freight and labour costs. International exposure creates currency and geopolitical risks. Flooring has historically generated lower margins than the core textile business. Opportunities Recovery in US and European home-textile demand. Growth of branded home-textile consumption in India. Premiumisation in towels, bedsheets, bath products and home décor. Expansion of technical/advanced textiles, healthcare and industrial applications. Higher utilisation of manufacturing capacity can improve operating leverage. New product innovation and global-brand expansion. Threats Competition from manufacturers in China, Bangladesh, Vietnam, Pakistan and Turkey. Cotton and other raw-material price volatility. US/EU tariffs and changes in international trade policies. Weak global consumer demand could affect export volumes. Freight-rate and currency volatility. Higher wage and manufacturing costs in India relative to some Asian manufacturing hubs. Q1 FY27 Financial Snapshot

#SectorBreakouts#USMarket#PersonalFinance
WELSPUNLIV-EQ_2026-10-03_11-14-21.png
918 likes·75 comments