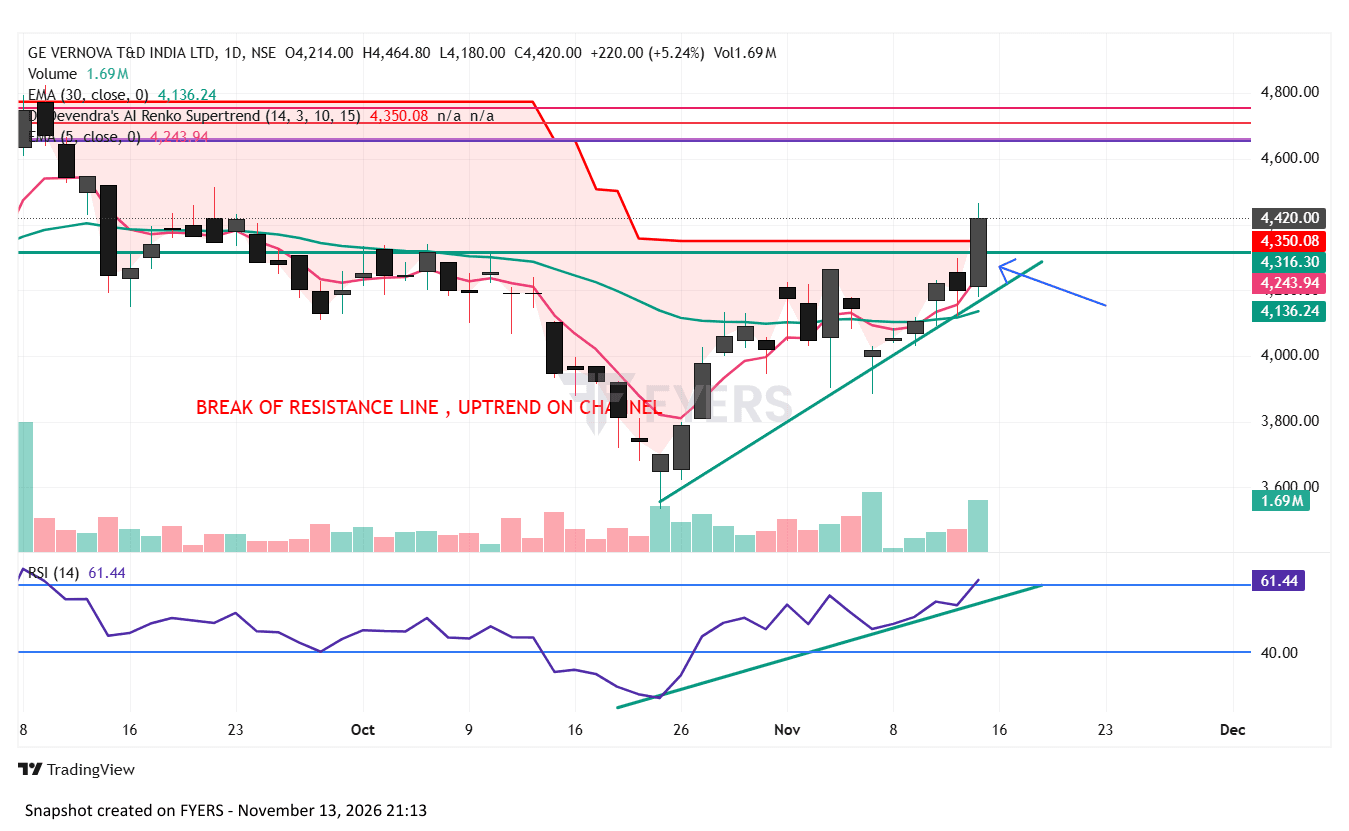
Manufactures power transformers, high-voltage equipment,
GVT&D Strengths - Strong global power technology expertise. - Leadership in HVDC and high-voltage equipment. - Strong order backlog of ₹21,443 Cr. - Q2 revenue growth of 32%. - EBITDA margin above 27%. - Strong cash generation. - Established relationships with Power Grid and utilities. - Advanced grid automation technology. Weaknesses - High dependence on large infrastructure projects. - Long project execution cycles. - High manufacturing capacity requirements. - Working capital needed for large orders. - Quarterly revenue can fluctuate. - Dependence on specialised components and supply chains. Opportunities - India's power transmission expansion. - Renewable energy grid connectivity. - 800 kV HVDC transmission projects. - Data-centre power infrastructure. - Battery storage and grid modernisation. - STATCOM and grid automation demand. - International export opportunities. - Large 6,000 MW Barmer–South Kalamb HVDC project: company received the Power Grid letter of award on 3 November 2026. Key Insights - Screener+2 Threats - Competition from Siemens Energy and other manufacturers. - Copper, steel and raw-material price fluctuations. - Project execution delays. - Supply-chain disruptions. - Government tender delays. - Technology changes and pricing pressure. - High stock valuation risk. 3. Important monitoring points - Order inflow above ₹7,000–8,000 Cr annually. - EBITDA margin above 25%. - HVDC project execution. - Order-book conversion into revenue. - Data-centre and renewable-energy orders. - Cash flow and working capital. - Capacity expansion and delivery timelines.