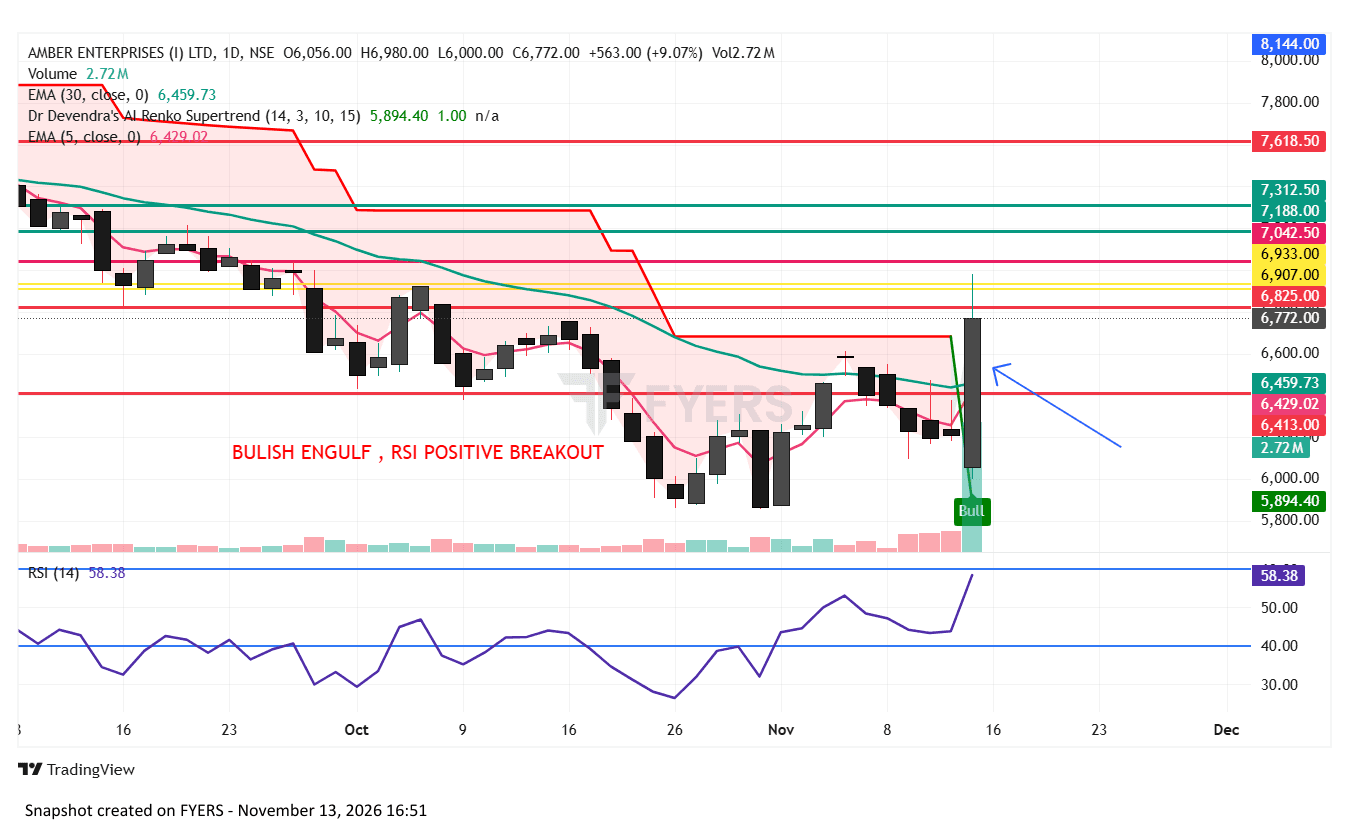
Manufactures room air conditioners, AC components
AMBER Strengths - Strong position in room AC manufacturing. - Diversified into electronics and railway components. - Electronics division revenue growth of 94%. - Strong manufacturing and OEM relationships. - Backward integration opportunities. - Growing PCB and electronics capabilities. - Exposure to India's Make in India programme. Weaknesses - Q2 adjusted net loss of ₹57 Cr. - EBITDA margin declined to 4.8%. - High dependence on seasonal AC demand. - High working-capital requirements. - New plant ramp-up costs. - Increased depreciation and finance expenses. - Negative operating cash flow in H1 FY27. Opportunities - Rising demand for air conditioners in India. - Electronics manufacturing and PCB expansion. - Railway HVAC and defence electronics. - Government PLI incentives. - Data-centre cooling solutions. - Import substitution in electronic components. - Expansion into high-value electronics products. Threats - Competition from Chinese and domestic manufacturers. - Copper, aluminium and component price inflation. - Foreign-exchange fluctuations. - AC industry demand slowdown. - Railway project execution delays. - Low margins in competitive manufacturing segments. - High debt and capex requirements. NSE Archives+3