‹ All Posts
Amit Malviya

1 hour ago · SEBI Registration INH000020615

IGIL Q2 Profit Jumps 43%, Stock Hits Upper Circuit
IGIL
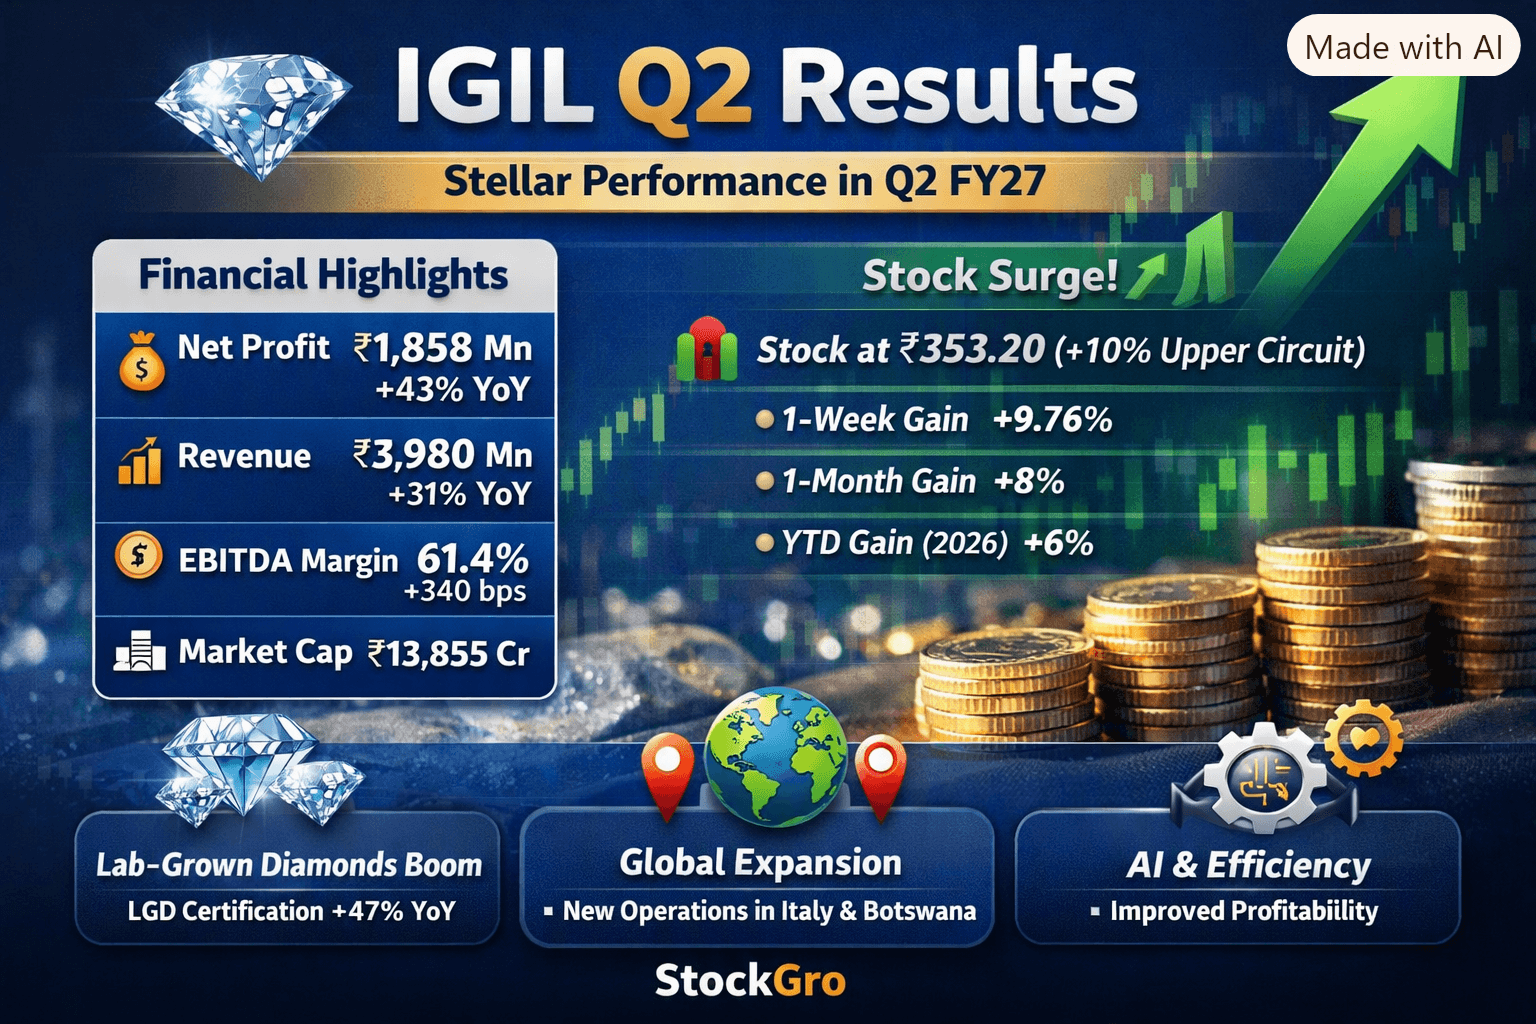
International Gemological Institute Limited (IGIL) has reported a stellar Q2 FY27 performance with net profit up 43% YoY to ₹1,858 million, revenue rising 31% YoY to ₹3,980 million, and EBITDA margins expanding to 61.4%. The stock hit a 10% upper circuit today, trading at ₹353.20 despite a weak broader market. 📊 Key Financial Highlights (Q2 FY27) Net Profit (PAT): ₹1,858 million, +43% YoY Revenue: ₹3,980 million, +31% YoY EBITDA Margin: 61.4% (+340 bps) Cash Flow: ₹415.7 crore generated in H1 FY27 Market Cap: ~₹13,855 crore PE Ratio: 22.7 vs sector average 38.7 📈 Stock Performance NSE Price Today: ₹353.20 (10% upper circuit) Previous Close: ₹321.10 1-Week Gain: +9.76% 1-Month Gain: +8% YTD Gain (2026): +6% 1-Year Gain: +4% 🔑 Growth Drivers Lab-Grown Diamonds (LGD): Certification volumes surged 47% YoY in jewelry, 37% YoY in loose stones. LGD penetration in the US bridal market now exceeds 50%. Strong festive demand in India boosted retail adoption. Operational Efficiency: AI-based grading and machine learning improved turnaround times. Higher-margin LGD reports drove profitability. Global Expansion: New operations launched in Italy. Preparing entries into Botswana and Saudi Arabia. Acquisition of American Gemological Laboratories (AGL) strengthens colored gemstone certification. 🌍 ESG & Corporate Actions ESG Score: 63 (FY26, NSE Sustainability) Dividend: ₹2.55 interim dividend declared for FY27 (paid in Sept 2026). Subsidiary Acquisition: Completed takeover of IGI Botswana in Sept 2026. ⚠️ Risks & Considerations Market Volatility: Despite IGIL’s surge, broader indices (Sensex & Nifty) fell ~1% today. Natural Diamonds: Certification growth only +3% YoY, showing slower demand compared to LGDs. High Valuation Risk: PE ratio (22.7) is below sector average but could expand if LGD demand slows.

#StockInNews#WatchOutFor#TechnicalViews#FundamentalViews
IGIL.png
15 likes·15 comments