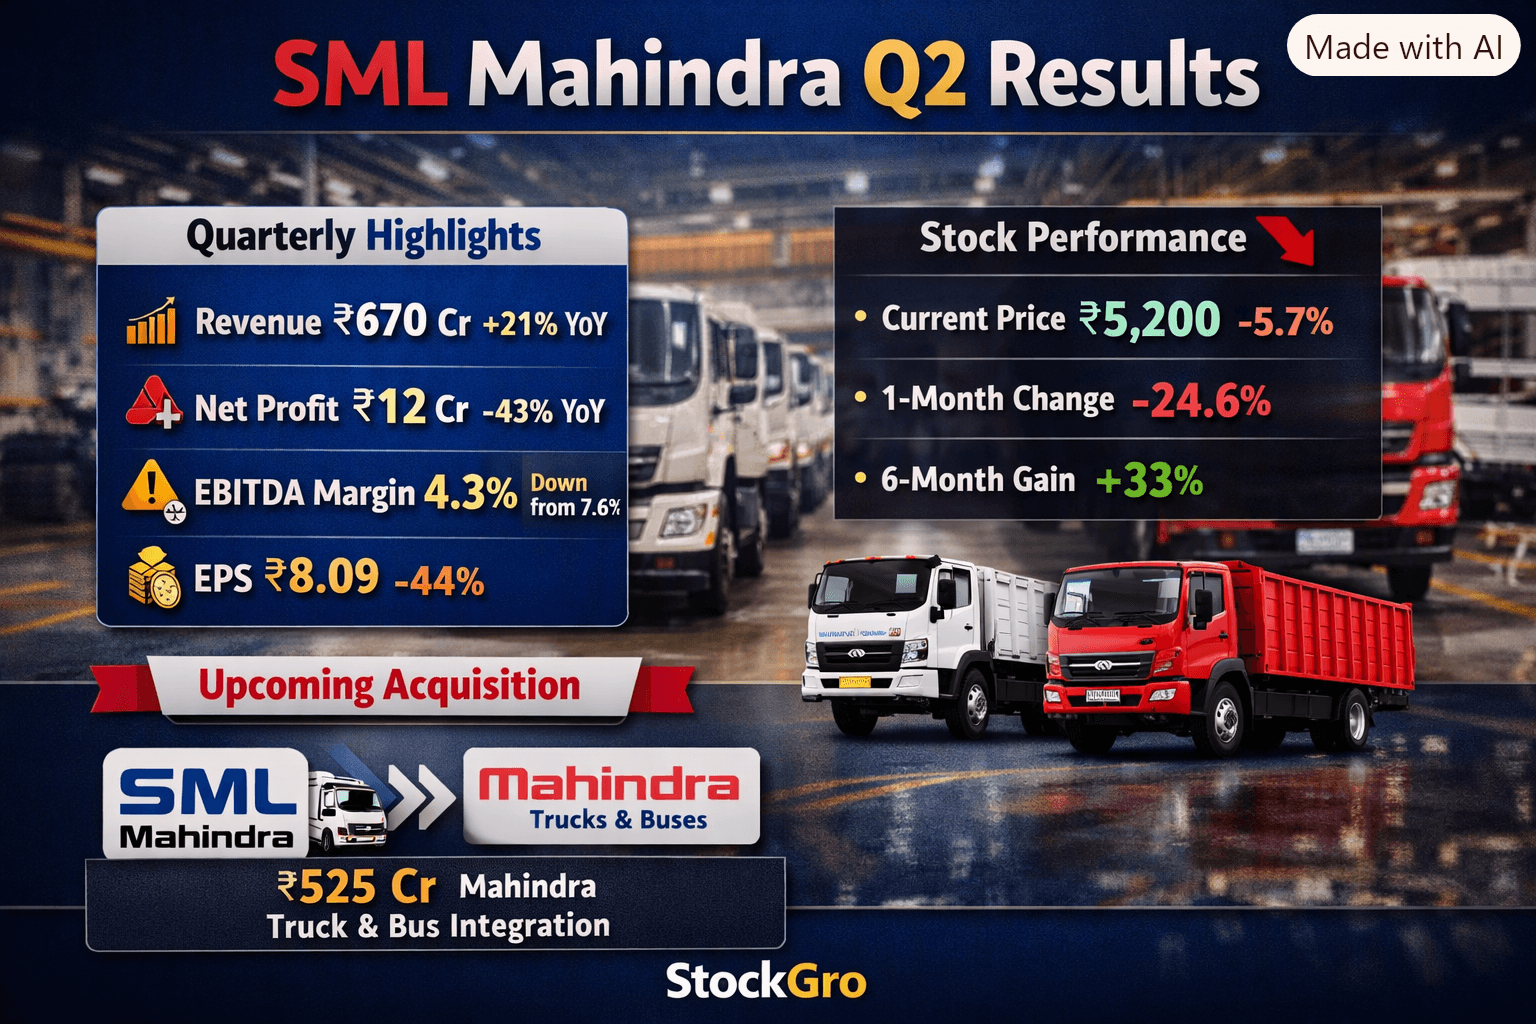
SML Mahindra Ltd (formerly SML Isuzu) reported a sharp 43% YoY drop in Q2 FY27 net profit to ₹11.7 crore, even as revenue rose 21% to ₹670 crore. The company’s EBITDA margin contracted to 4.3%, and the stock has fallen for three consecutive sessions after a strong six‑month rally.
📊 Key Financial Highlights (Q2 FY27)
Metric Q2 FY27 YoY Change Notes
Revenue from Operations ₹669.79 crore +20.7% Driven by truck and bus demand recovery
EBITDA ₹29 crore –31% Margin fell to 4.3% from 7.6%
Net Profit (PAT) ₹11.7 crore –43% Impacted by higher material and employee costs
Finance Cost ₹0.9 crore –69% YoY Debt reduction aided savings
EPS ₹8.09 per share –44% Reflects margin pressure
🚛 Strategic Developments
Mahindra & Mahindra Acquisition:
M&M holds 58.96% stake in SML Mahindra after acquiring it from Sumitomo Corp and Isuzu Motors in 2025.
Truck & Bus Division Transfer:
A ₹525 crore slump‑sale acquisition of M&M’s Truck & Bus Division is expected to close by January 31 2027, creating a unified commercial‑vehicle entity.
Market Ambition:
Mahindra aims for 10–12% CV market share by FY31 and 20% by FY36, leveraging SML’s light‑ and medium‑duty strength with Mahindra’s heavy‑truck technology.
Sustainability Push:
SML is expanding solar‑power use and piped‑natural‑gas energy at its Nawanshahar, Punjab plant.
📈 Stock Performance
Current Price (BSE, Oct 22 2026): ₹5,200 (–5.7%)
Previous Close: ₹5,514.75
1‑Month Change: –24.6%
6‑Month Gain: +33%
3‑Year Return: +290%
5‑Year Return: +583%
Despite short‑term weakness, long‑term investors remain optimistic about the Mahindra integration.
⚠️ Investor Takeaways
Positives: Revenue growth, lower finance costs, strong parent‑group backing, and strategic consolidation.
Concerns: Margin compression, rising input costs, and near‑term stock volatility.
Outlook: The merger with Mahindra’s Truck & Bus Division could unlock scale synergies and improve profitability from FY28 onward.