Astral Limited is one of India's leading building-materials companies.
Its major businesses are:
Pipes & Fittings — the core business
Adhesives & Sealants
Paints
Water tanks
Bathware and other building-material products
Astral's biggest strength is its strong brand, dealer/distribution network and premium positioning in plumbing products.
The company pioneered CPVC piping in India and has built a strong presence in the plumbing market.
Key point
Astral is no longer just a "pipes company." The management has been trying to build a broader building-materials platform, with adhesives, paints and other categories.
That provides a larger long-term opportunity, but it also means investors need to watch whether these newer businesses generate attractive returns.
Fundamental Strengths
🟢 Strong Brand
Astral has created a premium brand in pipes and plumbing products.
🟢 Distribution Network
The company's extensive dealer/distributor network provides a significant competitive advantage.
🟢 Margin Improvement
Q1 FY27 EBITDA margin improved to 15.5% from 14.3%.
🟢 Strong Profit Growth
PAT growth of approximately 48% YoY is an excellent number.
🟡 Volume Growth
This is the weak point.
Revenue has grown strongly, but plumbing volumes were almost flat.
So I would want to see volume growth accelerate, not just price/mix and margin improvement.
🟡 Valuation
Astral is a premium-quality business and consequently commands a premium valuation.
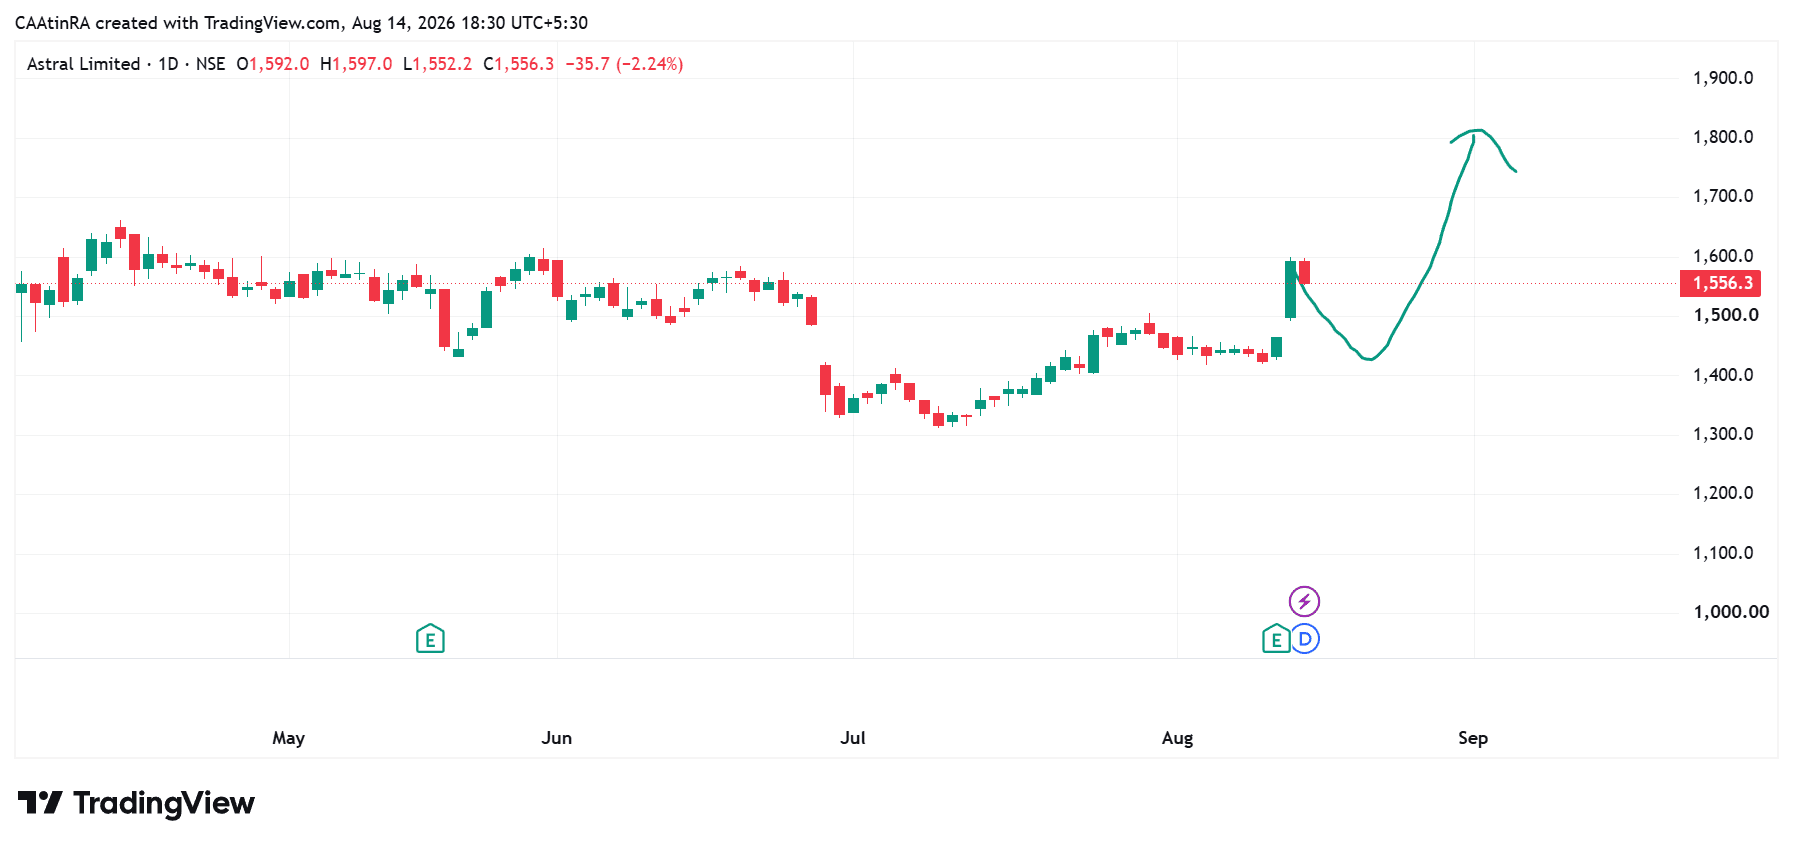
At around ₹1,556–1,578 currently, the market is already pricing in a reasonable amount of future growth. The stock therefore needs continued earnings growth to justify the valuation.