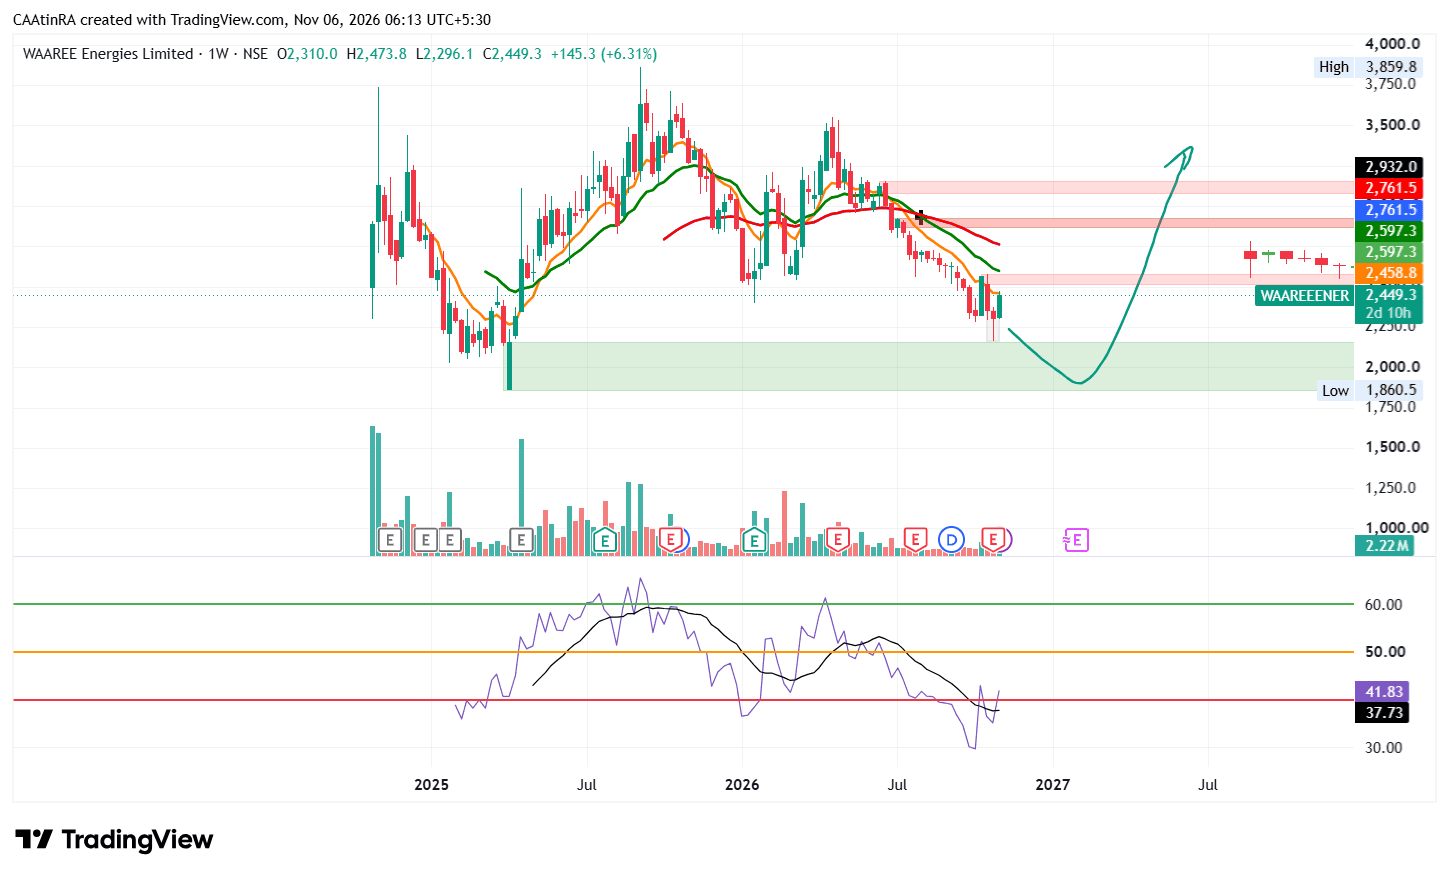
buy on dips strategy to follow for investment
WAAREEENER Waaree Energies Limited is one of India's prominent solar energy manufacturing companies. The company operates across solar photovoltaic (PV) modules, solar cells, inverters, battery energy storage systems (BESS), and renewable energy solutions. The company is benefiting from India's increasing focus on renewable energy, domestic solar manufacturing, energy security and government initiatives promoting clean energy. Waaree is also expanding its international presence, particularly in the United States, which provides opportunities to diversify its geographical revenue base. - Margin Pressure: Q2 FY27 EBITDA declined 5.1% despite revenue growth of 23.9%. Sustained margin pressure could affect future profitability. - International Trade Policies: Changes in US import duties, tariffs and local manufacturing regulations can affect export competitiveness. - Raw Material Costs: Changes in prices of polysilicon, wafers, cells and other inputs may impact operating margins. - Competition: Increasing solar manufacturing capacity in India and overseas could create pricing pressure. - Execution Risk: A large order book does not automatically guarantee future profits. Timely execution and payment collection remain important. - Capital Expenditure: Aggressive expansion requires substantial investment and efficient utilisation of manufacturing capacity. 6. Valuation Analysis Based on the available market data dated 5 November 2026: Parameter Value Market Capitalisation ₹70,454 Cr P/E Ratio 18.98 Sector P/E 54.21 ROE 32.48% ROCE 41.15% Debt/Equity 0.17 Book Value ₹501.90