Revenue Rises 15.55%, but Profitability Faces Pressure
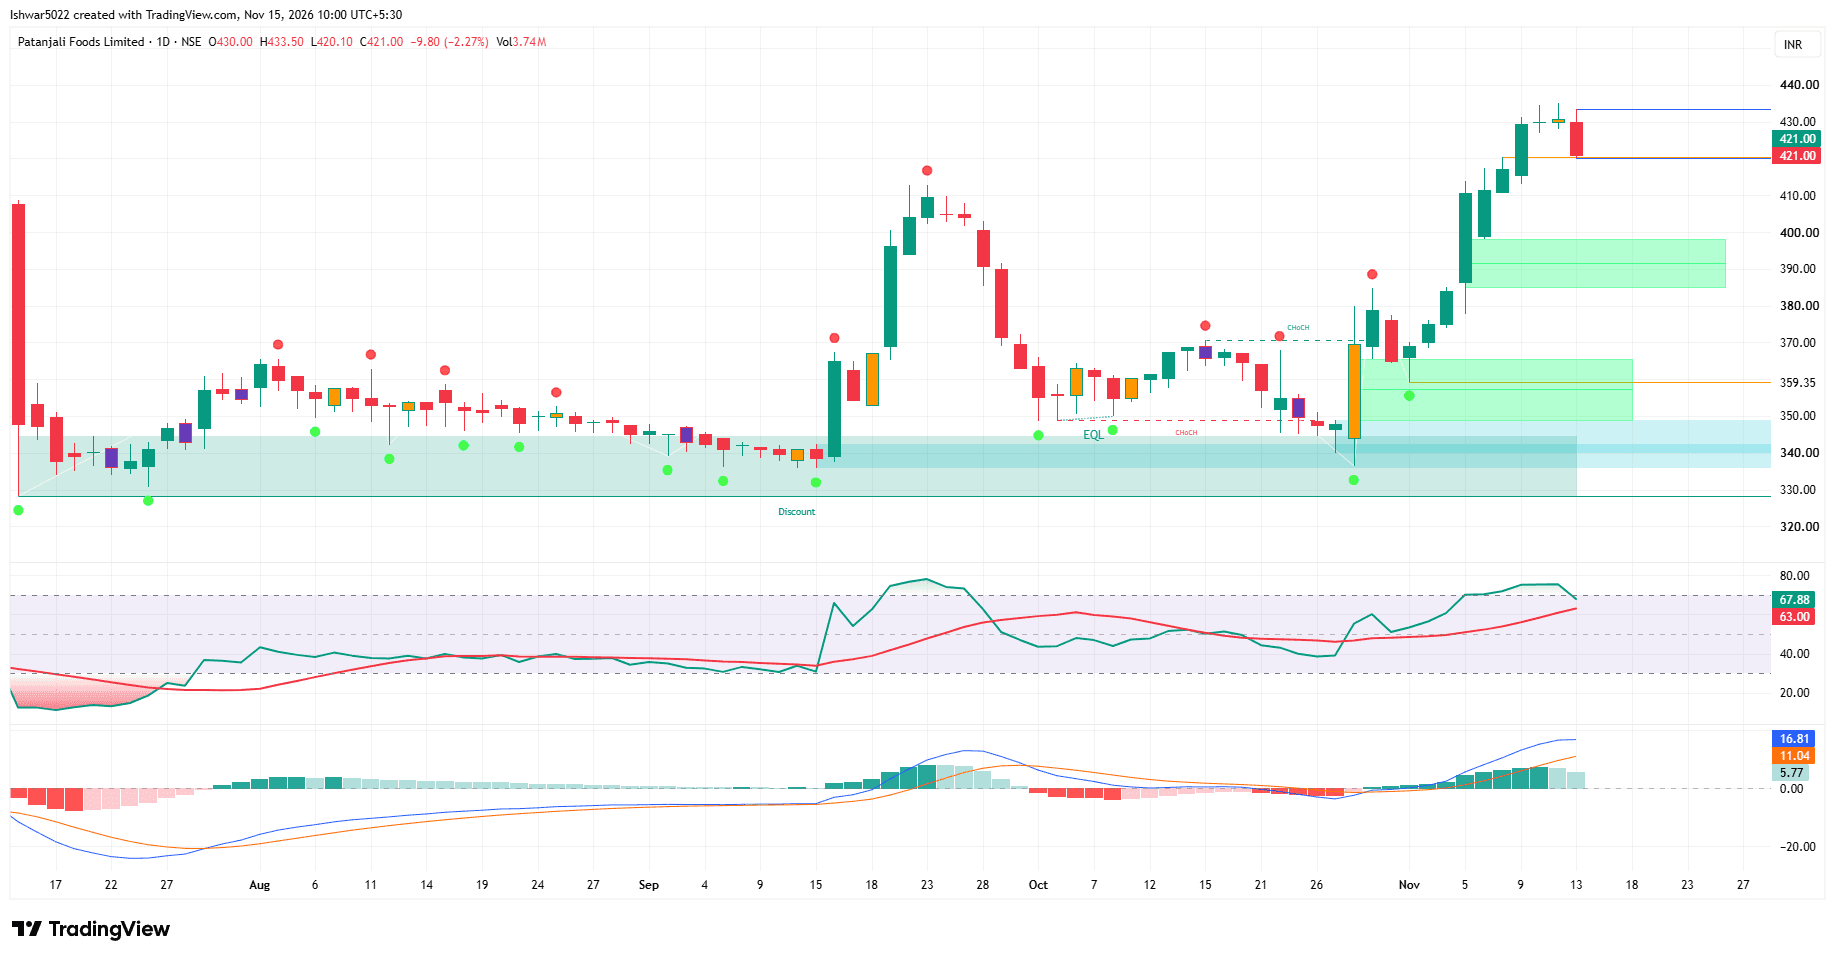
Q2 FY27 Results | September 2026 The company reported healthy revenue growth for the September 2026 quarter, but higher operating costs and interest expenses impacted profitability. Quarterly Financial Highlights Sales: ₹1,13,225.83 million, up 15.55% YoY. Net Profit (PAT): ₹4,197.97 million, down 18.75%. Operating Profit (PBIDT): ₹5,095.45 million, down 15.54%. PBT: ₹4,090.15 million, down 19.02%. Interest Cost: Increased 37.48% to ₹485.64 million. PBIDT Margin: Declined to 4.50% from 6.16%. Year-to-Date Performance Sales increased 22.06% to ₹2,26,600.34 million. PBIDT grew 12.79% to ₹10,573.80 million. PAT increased 8.40% to ₹7,556.54 million. SWOT Analysis Strengths: Strong quarterly revenue growth and positive year-to-date sales and profit growth. Weaknesses: Quarterly PAT and operating profit declined, while operating margin contracted significantly. Opportunities: Better cost management and margin recovery could improve future profitability. Threats: Rising interest expenses, margin pressure and higher operating costs may affect earnings. Investor View The results present a mixed picture. Revenue growth remains encouraging, but the decline in quarterly operating profit and net profit raises concerns about profitability. Investors should monitor margin recovery and cost control in coming quarters. What to Watch Next: Operating margins, interest costs, revenue growth and quarterly profit recovery. Technical View: Not assessed, as no price chart was provided. Disclaimer: Financial analysis based on the figures provided. Not a buy/sell recommendation.