: Accelerating Growth Through Premiumisation, Electronics & EV Opportunities
PRICOLLTD
: Accelerating Growth Through Premiumisation, Electronics & EV Opportunities** 🚗⚡
By Neha Gupta, Research Analyst
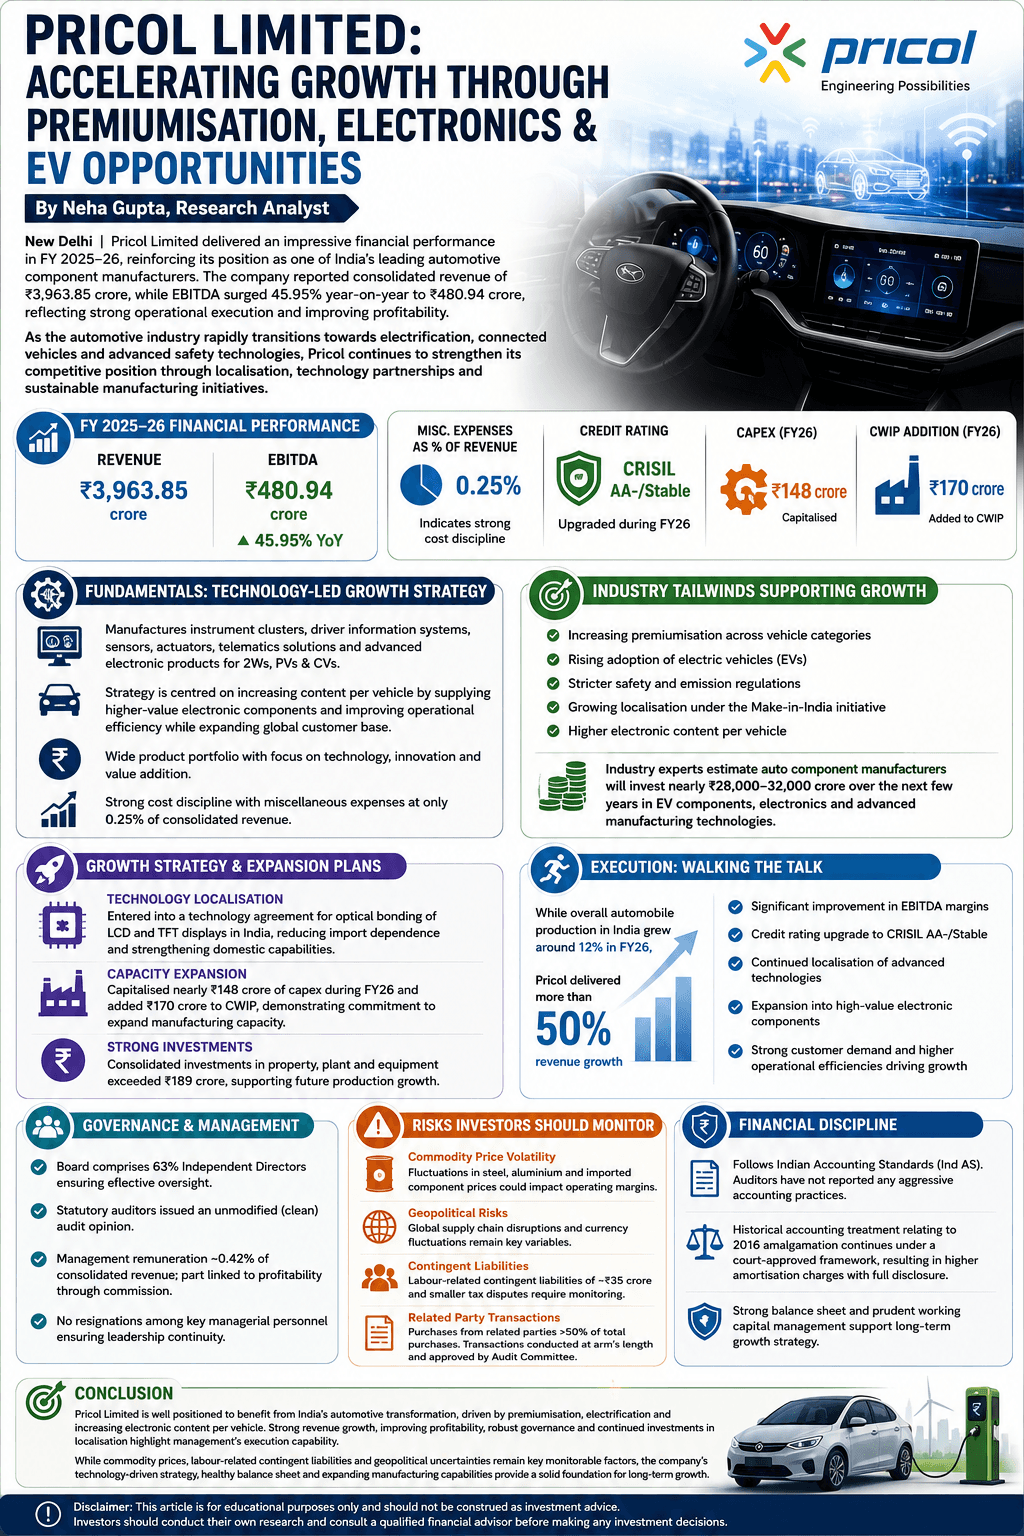
Pricol Limited delivered a strong FY26, reporting **₹3,963.85 Cr revenue** and **₹480.94 Cr EBITDA**, up **45.95% YoY**, reflecting robust execution and improving profitability.
As India's automotive industry moves toward electrification and connected mobility, Pricol is strengthening its position through localisation, electronics, and advanced manufacturing.
**Key Growth Drivers**
✅ Premiumisation across vehicle segments
✅ Rising EV adoption
✅ Higher electronic content per vehicle
✅ Make in India localisation
✅ Stricter safety & emission norms
**Execution Highlights**
• Technology agreement for optical bonding of LCD & TFT displays in India
• ₹148 Cr capitalised CapEx and ₹170 Cr added to CWIP during FY26
• CRISIL rating upgraded to **AA-/Stable**
• Continued expansion into high-value electronic components
**Governance**
✔ 63% Independent Directors
✔ Clean audit opinion
✔ Disciplined financial management
✔ Stable leadership team
**Key Risks**
⚠ Commodity price volatility
⚠ Global supply chain disruptions
⚠ Currency fluctuations
⚠ Labour-related contingent liabilities
⚠ Related-party transaction monitoring
**Conclusion**
Pricol is well-positioned to benefit from India's automotive transformation driven by premiumisation, EV adoption, and increasing electronic content per vehicle. Continued investments in technology, localisation, and capacity expansion provide a strong foundation for long-term growth, though investors should monitor raw material costs, demand trends, and execution.
*Educational purpose only. Not investment advice. Please do your own research.*
#Pricol #EV #AutoComponents #StockMarket #FundamentalAnalysis #IndianStocks