5 hours ago · SEBI Registration INH000020226
SEBI Registration INH000020226 · 5 hours ago
Augmont Q2 FY27 profit up 6.8%, revenue down 27%
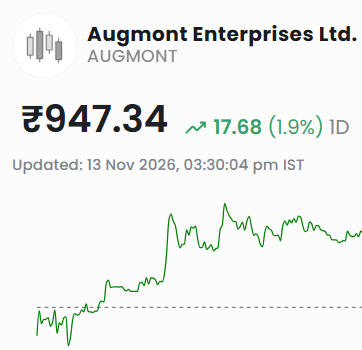
AUGMONT Augmont Enterprises Limited reported Q2 FY27 consolidated profit of Rs 120.3 crore, up 6.8 percent, while revenue fell 27 percent to Rs 15,835.5 crore. Q2 FY27 numbers (consolidated): Revenue from operations: Rs 15,835.5 crore, down 27 percent YoY from Rs 21,692.2 crore PAT: Rs 120.3 crore, up 6.8 percent from Rs 112.7 crore Finance costs: Rs 18.1 crore, from Rs 0.4 crore a year earlier Why it matters: the company said consumer revenue rose 47 percent while enterprise revenue fell 32 percent, as it shifted toward scrap gold. Costs fell faster than revenue, so the profit rise is a margin result, not growth. The finance cost jump is unexplained. Augmont Enterprises [AUGMONT][***** closed at Rs 947.34 on 13 November on StockGro, about 20 percent above its Rs 788 issue price in August. It is down 30.29 percent over one month, within a 52-week range of Rs 806.05 to Rs 1,404.60. P/E is 23.69 against a sector P/E of 46.51, and P/B is 8.73 against 9.11. My view: hold, not a fresh entry. The P/E discount to the sector looks like value, but the earnings behind it are shrinking at the top line, and the finance cost jump is the question I need answered before I call the discount real. Holders can keep the position. Fresh money should wait for the Q3 FY27 result (date not confirmed) showing revenue stabilising and a clear explanation of finance costs. Invalidation: a close below Rs 806.05, the 52-week low, which would show the price losing its base. What would change my mind: enterprise revenue turning up while gold recycling stays a large share of procurement. Disclosure: Vijay Kumar Gupta, SEBI Registered Research Analyst, INH000020226, Vijay Gupta Advisory. SEBI registration and NISM certification do not guarantee performance or assure returns. Securities markets are subject to market risks. No holdings in the subject company.