Info Edge Q1 FY27: Operating Profit Up 33%, Naukri Margin
NAUKRI
Info Edge (India) Limited reported Q1 FY27 results for the June 2026 quarter on 10 August.
Q1 FY27 numbers (consolidated, excluding associate MTM):
Revenue from operations: Rs 880.7 crore, up 11.4% YoY; standalone billings up 14.4% YoY
Standalone operating PBT: Rs 333.9 crore, up 33.4% YoY; margin 40.5% vs 34.0%
Consolidated PAT (ex-associate MTM): Rs 490.1 crore, up 42.9% YoY from Rs 342.9 crore
Recruitment revenue Rs 629.2 crore, up 11.9%; Naukri profit Rs 353 crore
99acres revenue Rs 129.8 crore, up 17.3%; nearing breakeven; loss Rs 2.1 crore
Quarter included a Rs 135.6 crore net exceptional gain; EPS Rs 6.88
Note on the headline: the filing also shows a consolidated net loss of Rs 89.73 crore including Zomato and other associate MTM swings; they measure different things.
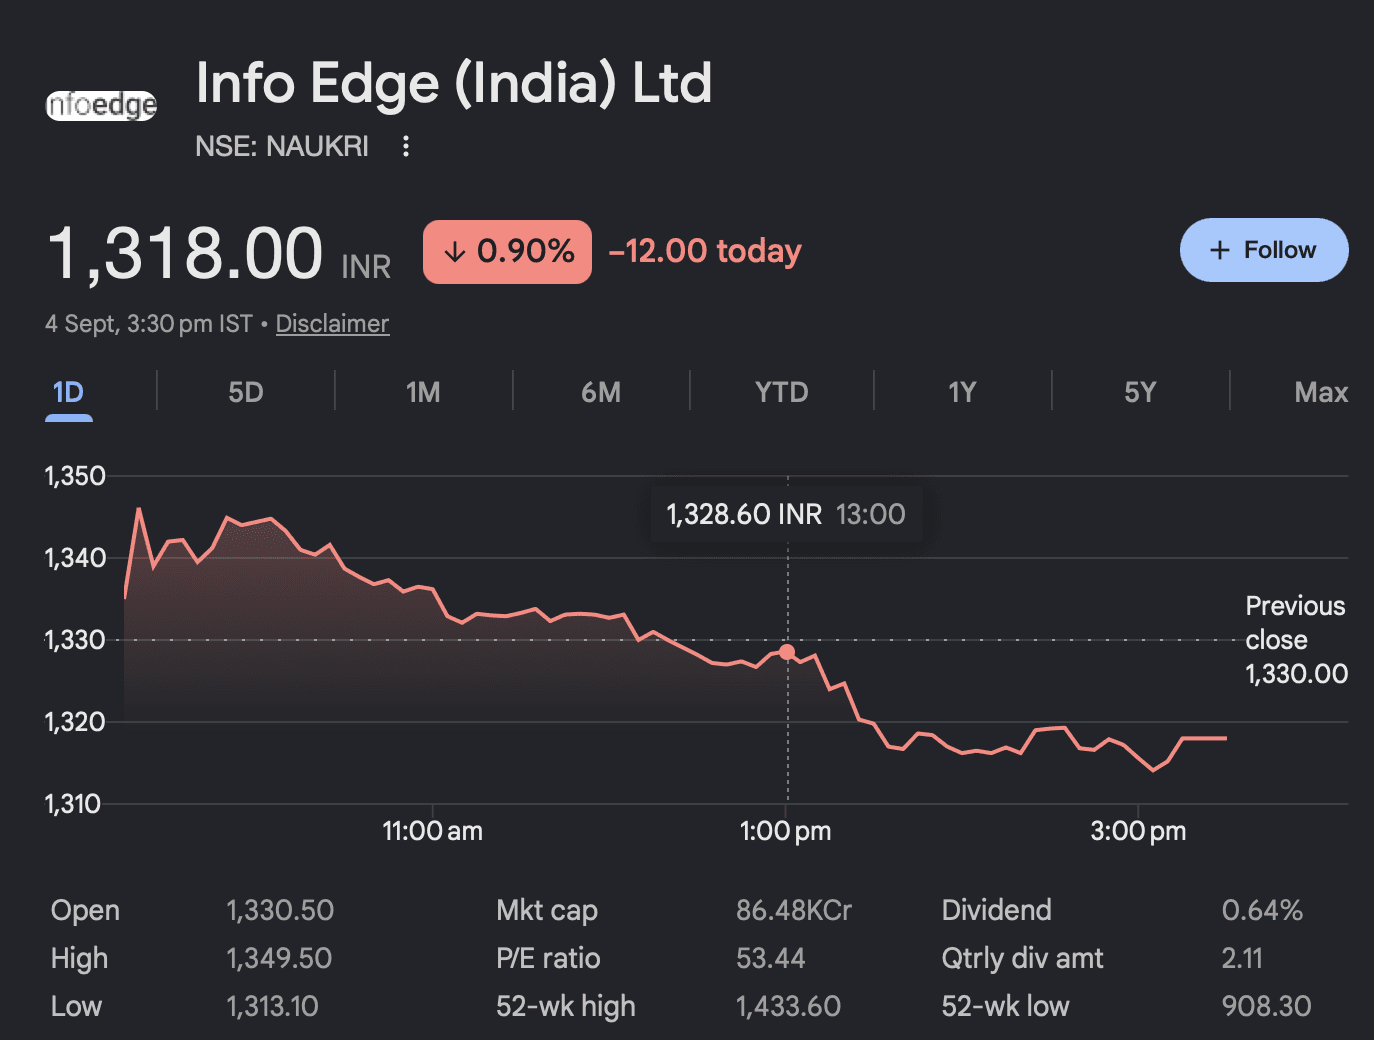
Info Edge [***** shares trade near Rs 1,320 (4 Sep 2026, NSE close), up 45 percent in a year from the Rs 908 low, 8 percent below the Rs 1,434 high. P/E near 54; net cash, zero long-term debt.
My view: the operating business is strong enough to justify a premium. Naukri is the toll gate on Indian white-collar hiring; a 33 percent operating PBT rise and a 40 percent margin show that leverage. 99acres nearing breakeven removes a drag. But 54x for an 11 percent revenue grower is priced for everything right, and the associate MTM line means reported earnings will swing with Zomato's fortunes. Hold; fresh entry on a pullback to Rs 1,210 to 1,270, the post-results base, is the disciplined entry. Levels: Rs 1,210 to 1,270 support; Rs 908 the tested floor; Rs 1,434 to 1,440 the resistance to clear.
Disclosure: Vijay Kumar Gupta, SEBI Registered Research Analyst, INH000020226, Vijay Gupta Advisory. SEBI registration and NISM certification do not guarantee performance or assure returns. Securities markets are subject to market risks. No holdings in the subject company.