‹ All Posts
VIJAY KUMAR GUPTA

3rd Oct · SEBI Registration INH000020226

LTM Q1 earnings surge 17%; stock down 22% YoY
LTM
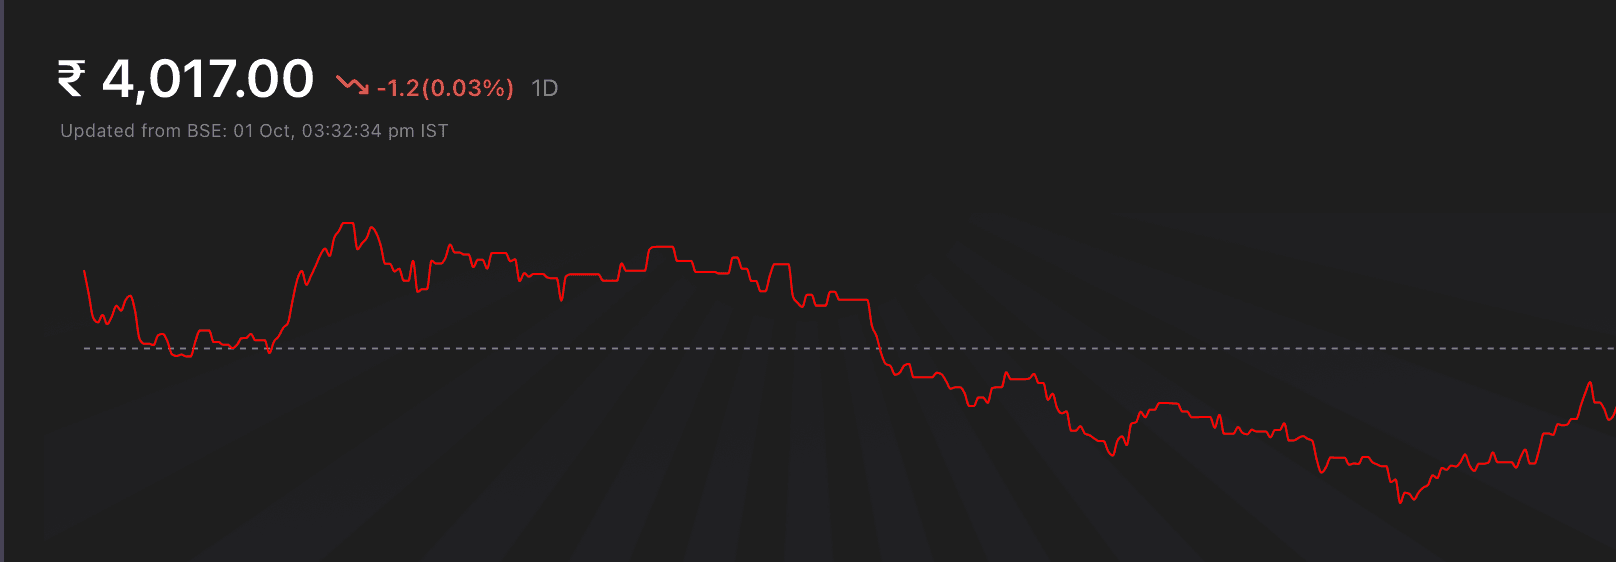
***** Q1 FY27 (ended 30 Jun 2026): Revenue Rs 11,608Cr (+18% YoY, +2.8% QoQ); PAT Rs 1,468.6Cr (+17% YoY, +5.9% QoQ); EPS Rs 49.42 (+16.9% YoY, +5.3% QoQ). EBIT surged 27.9% YoY to Rs 1,799.3Cr; EBIT margin 15.5%, up 121bp YoY and 36bp QoQ. Order inflow $1.68B signals robust deal pipeline. Active client count 740; new clients added 16. Attrition 13.3% TTM. Valuation disconnect evident. PAT and EBIT both accelerating faster than revenue, proving operational excellence and pricing power during macro headwinds. Margin expansion of 121bp YoY is exceptional for IT services. Yet stock down 22% YoY despite 18% revenue and 17% profit growth. Peers (Infosys, HCLTech, TCS) also under pressure, suggesting sector-wide rotation out of IT into value plays. Order book strength ($1.68B inflow) underpins Q2-Q3 visibility. Stock: Rs 4,007 (01 Oct), down 0.94% on the day but down 21.78% YoY. Exited Nifty 50 on 30 Sep. P/E 22.93, dividend yield 1.3% (Rs 53 interim). 52-week range Rs 3,528-Rs 6,429.50. Market cap Rs 1,19,153Cr. Hold pending Q2 results (due 26 Oct). Margin recovery is real; attrition trends and deal conversion into bookings are the watch. Rs 53 dividend per share provides minimal cushion given recent drawdown. Fresh entry justified only sub-Rs 3,800 into macro capitulation signals. Accumulate in zone if growth inflection signals emerge post-Oct guidance. Vijay Gupta Advisory (SEBI RA INH000020226) — This is data and analysis, not a recommendation. See disclosures at *****

#StockInNews#WatchOutFor#Miscellaneous#EquityResearch
ltm_dialy_updates.png