9 mins ago · SEBI Registration INH000020226
SEBI Registration INH000020226 · 9 mins ago
Marico trades at 53x run-rate profit; not a fresh entry
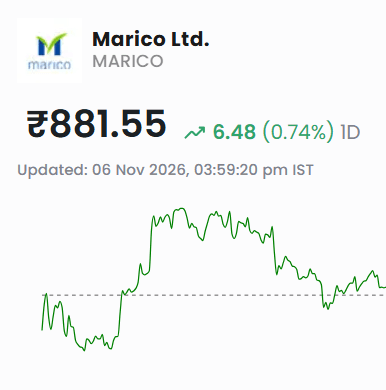
MARICO Marico Limited trades at about 53 times its Q2 FY27 run-rate profit, and one good quarter does not close that gap by itself. Valuation, on the Q2 FY27 numbers (consolidated): Q2 net profit: Rs 550 crore, so Rs 2,200 crore annualised Q2 EBITDA: Rs 709 crore, so Rs 2,836 crore annualised; margin 18.2% Market cap: Rs 1,16,628 crore; 53 times run-rate profit, 41 times run-rate EBITDA Trailing P/E 56.8 against a sector P/E near 31 Run-rate arithmetic is rough. Quarterly profit is seasonal, and the base is soft: Q2 FY26 EBITDA was Rs 560 crore, so part of the 27 percent growth is a low base. Management’s FY27 guide of mid-twenties EBITDA growth would still leave the valuation well above the sector on trailing numbers. Marico [MARICO][***** closed at Rs 881.55 on 6 November on StockGro, 0.4 percent below its 52-week high of Rs 885.33. P/E 56.8; sector P/E near 31. My view: hold, not a fresh entry, unchanged from 7 November. At 53 times run-rate profit, the price assumes the growth continues for longer than one quarter. The 10 percent India volume growth carries most of that case, and it is one quarter of data. Holders stay; exit on a close below Rs 780. Fresh money waits for a close at or below Rs 850.70, the 3 November NSE print, and for Q3 India volume growth at or above 10 percent. What would change my mind: Q3 volume growth below 10 percent, or a Q3 EBITDA print below the mid-twenties guide. Next trigger: Q3 FY27 results, date not yet sourced. Disclosure: Vijay Kumar Gupta, SEBI Registered Research Analyst, INH000020226, Vijay Gupta Advisory. SEBI registration and NISM certification do not guarantee performance or assure returns. Securities markets are subject to market risks. No holdings in the subject company.