3 hours ago · SEBI Registration INH000020226
SEBI Registration INH000020226 · 3 hours ago
MCX Q2 profit up 130% to Rs 455 crore; turnover holds
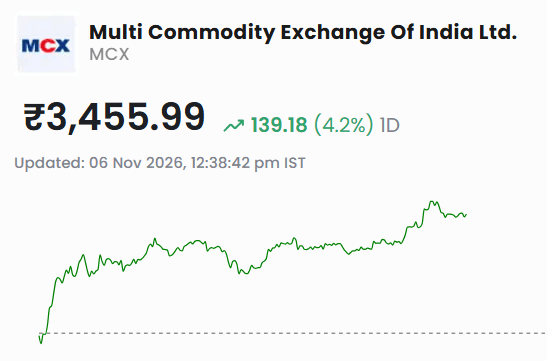
MCX Multi Commodity Exchange of India Limited reported Q2 FY27 consolidated profit of Rs 454.57 crore on 3 November, up about 130 percent, and the shares still fell about 5 percent the next day. Q2 FY27 numbers (consolidated): Revenue from operations: Rs 799.66 crore, up 113.7% from Rs 374.23 crore EBITDA: Rs 611.24 crore; margin 76.4%, against 65.1% PAT: Rs 454.57 crore, against Rs 197.47 crore; EPS Rs 17.83 Futures turnover: Rs 62,819 crore a day; options Rs 12.0 lakh crore a day My gate on 10 October was turnover holding near Q1 levels. Futures turnover rose about 5 percent on Q1 (Rs 59,674 crore) and options about 21 percent (Rs 9.90 lakh crore), so the gate passes. The margin is turnover-led. The FPI rule is not in these numbers. I found no cause for the 4 November fall. MCX [MCX][***** traded at Rs 3,458.28 at 12:37 PM IST on 6 November on StockGro, up 4.3 percent from its previous close of Rs 3,316.81, and up 3.7 percent in a month. P/E 59.7; sector P/E near 19. My view: hold, not a fresh entry. The print passes the turnover gate, so I have no reason to cut. The stock is 8 percent above my Rs 3,200 exit and 2.3 percent below the Rs 3,538 52-week high, so it is not priced for a pullback. Holders stay; exit on a close below Rs 3,200. Fresh money waits for a pullback toward Rs 3,300 (Anand Rathi support, attributed) and Q3 turnover at or above Q2. What would change my mind: Q3 turnover falling below Q2 levels, or the FPI rule delayed past its first trading date. Next trigger: Q3 FY27 results, date not yet sourced. Disclosure: Vijay Kumar Gupta, SEBI Registered Research Analyst, INH000020226, Vijay Gupta Advisory. SEBI registration and NISM certification do not guarantee performance or assure returns. Securities markets are subject to market risks. No holdings in the subject company.