34 mins ago · SEBI Registration INH000020226
SEBI Registration INH000020226 · 34 mins ago
Policybazaar Q2 profit up 42 percent, premium up 38 percent
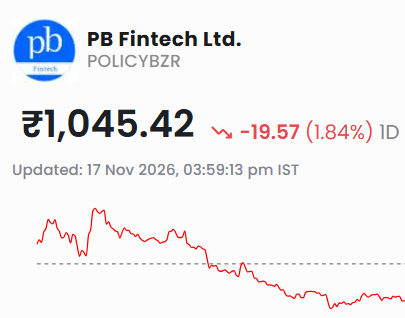
POLICYBZR PB Fintech Limited, the Policybazaar parent, reported consolidated Q2 FY27 results on 30 October. Profit rose 42.7 percent, yet the stock closed at Rs 923.10 on 3 November, below the Rs 927.87 exit level in my 21 October post. Q2 FY27 numbers (consolidated): - Revenue: Rs 2,177.71 crore, up 35% YoY from Rs 1,613.55 crore - PAT: Rs 192.45 crore, up 42.7% YoY from Rs 134.86 crore - Insurance premium: Rs 9,385 crore, up 38% YoY, against 41% in Q1 - Adjusted EBITDA: about Rs 220 crore, up 39% YoY Why it matters: the stock fell 7.19 percent on 2 November; reports cited adjusted EBITDA below some estimates on higher marketing spend. IRDAI's 23 September paper on commission caps is not final; a 13 November report expects a revised draft by mid-December, and the stock rose about 5 percent that day. Policybazaar [POLICYBZR][***** shares closed at Rs 1,045.42 on 17 November on StockGro (NSE Rs 1,052.10), down 1.6 percent in a month and 41 percent in a year, 46 percent below the NSE 52-week high of Rs 1,964.20. P/E 60. My view: the exit stands; this is not a re-entry. My 21 October view was hold with that exit; it fired on 3 November, so holders who followed it are out. The stock is about 14 percent above that close; I am not chasing it. The rebound rests on a press report of a revised draft, not an order, and my Q2 test for fresh money, premium growth near 41 percent, came in at 38 percent. For anyone still holding, the line is the NSE 52-week low, Rs 916. What would change my mind: a revised IRDAI draft that drops or softens the commission caps, with Q3 premium growth of 38 percent or more. Disclosure: Vijay Kumar Gupta, SEBI Registered Research Analyst, INH000020226, Vijay Gupta Advisory. SEBI registration and NISM certification do not guarantee performance or assure returns. Securities markets are subject to market risks. No holdings in the subject company.