2 hours ago · SEBI Registration INH000020226
SEBI Registration INH000020226 · 2 hours ago
TCS up 20% in a month; TCV misses, stance holds
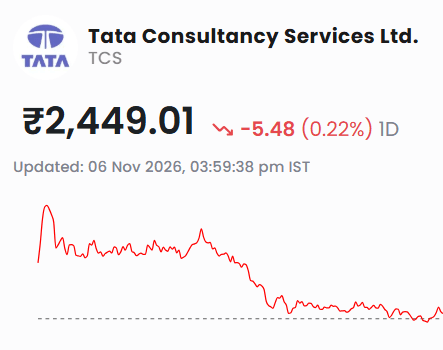
TCS Tata Consultancy Services Limited has risen about 20 percent in a month, and the shares closed at Rs 2,449.01 on 6 November, well above the zone I set on 15 October. Q2 FY27 numbers (consolidated, reported 8 October): Net profit: Rs 13,884 crore, up 15% from Rs 12,075 crore Revenue: Rs 73,188 crore, up 11.2% from Rs 65,799 crore EBITDA: Rs 18,815 crore; margin 25.7%, down 162 bps YoY Total contract value: $9.6 billion, short of my $10 billion test My 15 October post set three conditions for fresh money: constant-currency growth of at least 0.5 percent, a margin near 24 percent, and TCV above $10 billion. The first two passed, and TCV failed. I found no company announcement behind the rally. Sector coverage ties it to the IT rebound after the Q2 result. TCS [TCS][***** closed at Rs 2,449.01 on 6 November on StockGro (previous close Rs 2,454.49), up 20.1 percent in a month and down 18.3 percent over a year. P/E 17.2; sector P/E near 22. My view: hold, not a fresh entry, and the stance is unchanged from 15 October. I have no new fact that changes it, and TCV still misses my test. The stock is 19.5 percent above the Rs 2,050 top of my zone, so it is priced for more than the one condition that passed. Holders stay; exit on a close below Rs 1,976.80, the 1 July low. Fresh money waits for a pullback into the Rs 1,976.80 to 2,050 zone with TCV at or above $10 billion in a quarter. What would change my mind: a Q3 TCV above $10 billion, or a company reason for the rally that changes the earnings base. Next trigger: Q3 FY27 results, date not yet sourced. Disclosure: Vijay Kumar Gupta, SEBI Registered Research Analyst, INH000020226, Vijay Gupta Advisory. SEBI registration and NISM certification do not guarantee performance or assure returns. Securities markets are subject to market risks. No holdings in the subject company.