14 mins ago · SEBI Registration INH000020226
SEBI Registration INH000020226 · 14 mins ago
Wipro valuation: P/B 2.31 against sector 4.96
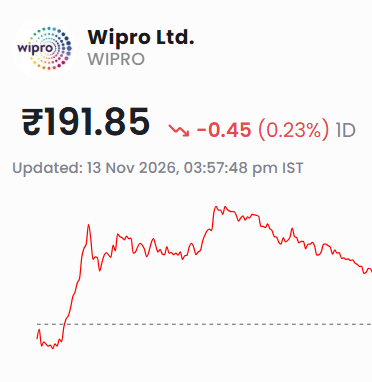
WIPRO Wipro Limited trades at 14.8 times trailing earnings and 2.3 times book value, below the IT sector’s 21.4 times earnings and 5.0 times book, after its Q2 FY27 print. Valuation (StockGro, 13 November): P/E: 14.8 against a sector P/E of 21.4 P/B: 2.3 against a sector P/B of 5.0 Market cap: Rs 1,92,661 crore, about 15 times annualised Q2 profit of Rs 3,201 crore Wipro [WIPRO][***** closed at Rs 191.85 on 13 November on StockGro, up 13.8 percent over one month and down 17.9 percent over one year. Why it matters: the discount is real on paper, but it has a cause. Q2 IT services revenue was flat quarter on quarter, Q3 guidance is minus 1.5 to plus 0.5 percent in constant currency, and the company has not quantified its exposure to the US PERM visa suspension. A cheap multiple on flat revenue does not by itself make a buy. My view: hold, not a fresh entry. The valuation is the strongest case for Wipro so far, and it is still not enough. Holders can keep the position. Fresh money should wait for either a management count or cost estimate for the PERM exposure, or the Q3 FY27 result (date not confirmed) with constant-currency revenue inside the guide. Invalidation: a close below Rs 156.79, the 52-week low, which would mean the price has put a lower value on the earnings than the multiple implies. What would change my mind: a Q3 print above the top of the guide, which would turn the discount into a mispricing. Disclosure: Vijay Kumar Gupta, SEBI Registered Research Analyst, INH000020226, Vijay Gupta Advisory. SEBI registration and NISM certification do not guarantee performance or assure returns. Securities markets are subject to market risks. No holdings in the subject company.