‹ All Posts
AASHISH RA

32 mins ago · SEBI Registration INH000013174

Aditya Birla Real Estate, formerly Century Textiles
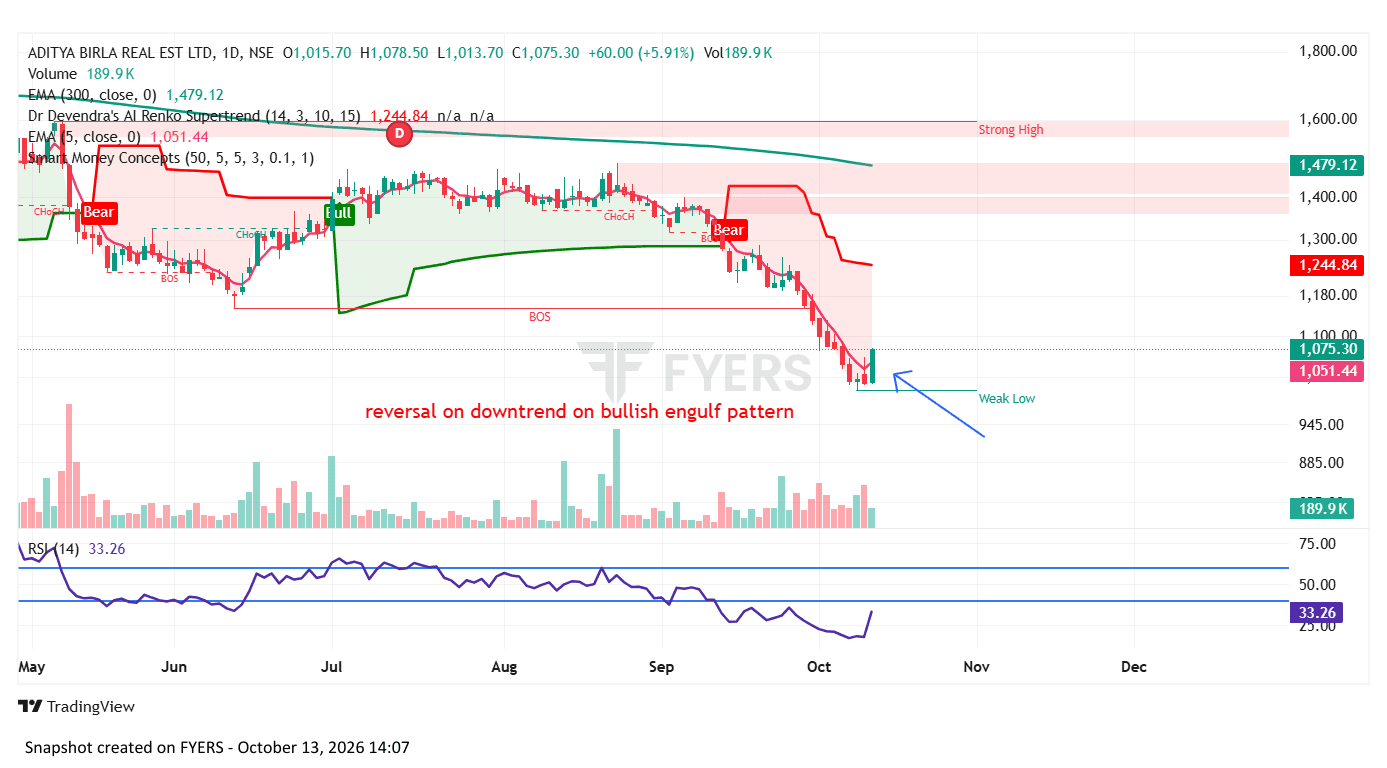
ABREL
Strengths - Strong brand and group backing: Association with the Aditya Birla Group supports brand recognition and customer confidence. - Strong real estate booking base: Birla Estates recorded FY26 booking value of ₹8,136 crore, with collections rising 23.5% year-on-year to approximately ₹3,342 crore. - Presence in key markets: Projects across Delhi-NCR, Mumbai Metropolitan Region, Bengaluru and Pune provide exposure to major urban housing markets. Diversified business history: The company has experience in paper and other industrial businesses in addition to property development. Weaknesses - Consolidated losses: Q1 FY27 reported a net loss of ₹34.59 crore, highlighting the gap between revenue growth and profitability. - High project-related costs: Land acquisition, construction, marketing and financing can weigh on earnings before projects are completed and revenue is recognised. - Uneven booking growth: FY26 booking value rose only about 1.7% year-on-year despite a high base. Complex business mix: Investors must assess the real estate business separately from the company's legacy industrial operations when evaluating performance. Opportunities - Premium and luxury housing: Continued demand for branded homes in major cities may support new project launches and higher booking values. - Redevelopment projects: Urban redevelopment can expand the project portfolio without relying solely on outright land purchases. Threats - Real estate cycle risk: A slowdown in housing demand or a fall in property prices could reduce bookings. - Interest-rate and financing risk: Higher borrowing costs can increase project expenses and pressure profitability. - Execution and regulatory delays: Approval delays, construction overruns or slower handovers may defer cash flows.

#FundamentalViews#Pre-OpeningCommentary#Miscellaneous
ABREL-EQ_2026-10-13_14-07-17.png
8 likes·7 comments