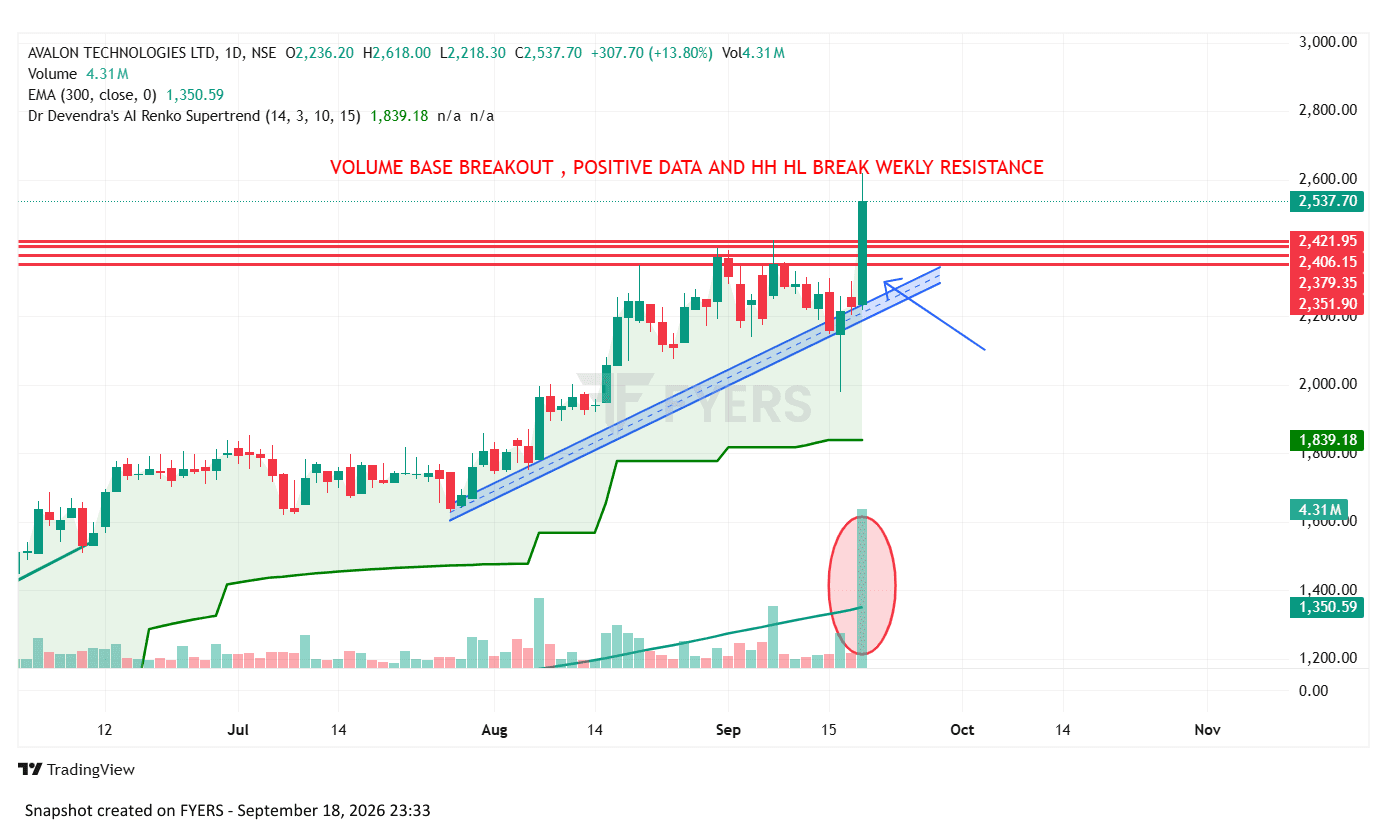
Strengths
Strong Q1 FY27 growth: Consolidated revenue was approximately ₹484 Cr, up 49.9% YoY.
Q1 FY27 net profit was approximately ₹35 Cr, compared with ₹14 Cr in Q1 FY26, a 150% YoY increase.
Integrated manufacturing capabilities across PCB assemblies, box-build, cable harnesses and precision machining.
Weaknesses
EMS is a high-execution and relatively competitive business, with margins dependent on product mix, customer programmes and manufacturing efficiency.
Rapid growth requires continued investment in capacity, technology and working capital.
Customer programme delays or changes in production schedules can affect quarterly revenue.
International exposure creates sensitivity to currency movements and overseas demand.
Opportunities
India's increasing role in global electronics manufacturing and supply-chain diversification can provide long-term opportunities.
Growth in EVs, industrial electronics, power electronics, medical equipment and semiconductor-related applications can expand the addressable market.
Higher-value manufacturing and engineering services can improve the revenue mix.
Expansion of the US and Indian manufacturing ecosystem can support export growth.
Additional customer wins and programme ramp-ups could provide operating leverage.
Threats
Competition from large Indian and global EMS companies.
Component shortages and supply-chain disruptions can affect production.
Rapid technology changes require continuous capex and engineering investment.
Customer concentration/programme dependency can create revenue volatility.
Pricing pressure from large OEM customers can restrict margin expansion.
Global trade restrictions, tariffs and currency fluctuations may affect export economics.