GESHIP — Great Eastern Shipping Company SWOT Analysis
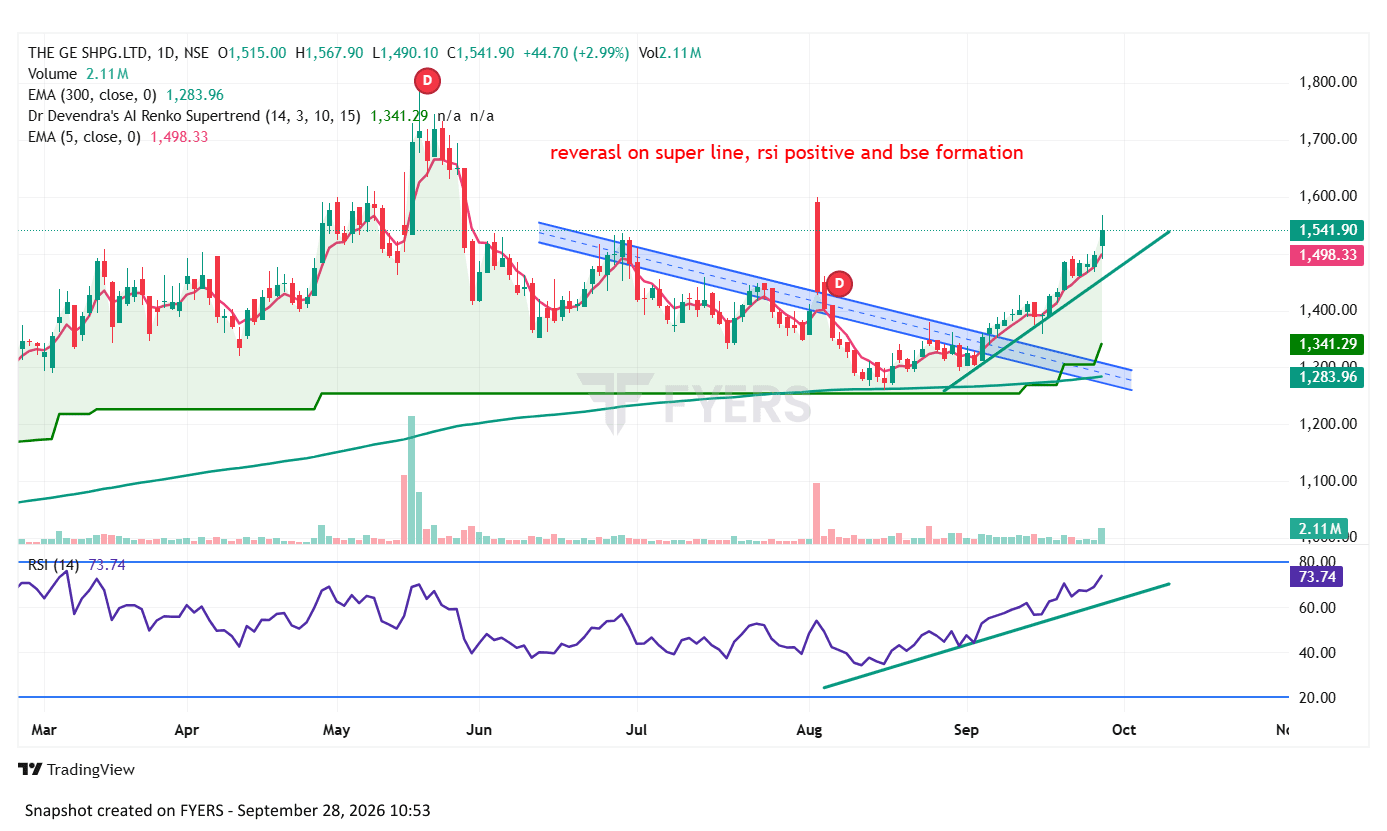
GESHIP
Strengths
One of India's established private-sector shipping companies with exposure to crude/product tankers, dry bulk and offshore services.
Strong balance sheet with a substantial net-cash position historically; FY26 standalone profit was about ₹2,356 Cr.
Q1 FY27 showed strong operating performance: total revenue around ₹2,005 Cr and PAT around ₹1,309 Cr, up approximately 159% YoY.
Active fleet-management strategy, including buying and selling vessels to optimise fleet age and economics.
Significant asset backing from its vessel fleet.
Weaknesses
Earnings are highly dependent on shipping freight rates, which can fluctuate substantially.
Quarterly results can be volatile because vessel-sale gains and charter rates can materially affect reported earnings.
High capital requirement for vessel acquisition and fleet renewal.
Shipping assets are exposed to depreciation and changes in vessel valuations.
International operations create exposure to foreign exchange and geopolitical developments.
Opportunities
Higher tanker demand driven by global oil transportation and changing trade routes.
Fleet renewal can improve operating efficiency and asset values.
Dry-bulk demand can benefit from global commodity and infrastructure activity.
Expansion in offshore services and energy-related maritime transportation.
Industry-wide supply constraints in certain vessel segments could support charter rates.
Threats
Sharp correction in tanker or dry-bulk freight rates.
Global recession reducing commodity transportation demand.
Geopolitical disruptions, sanctions and changes in shipping routes.
Higher vessel prices and financing costs could affect fleet-renewal economics.
Environmental regulations and decarbonisation requirements may increase compliance and capital