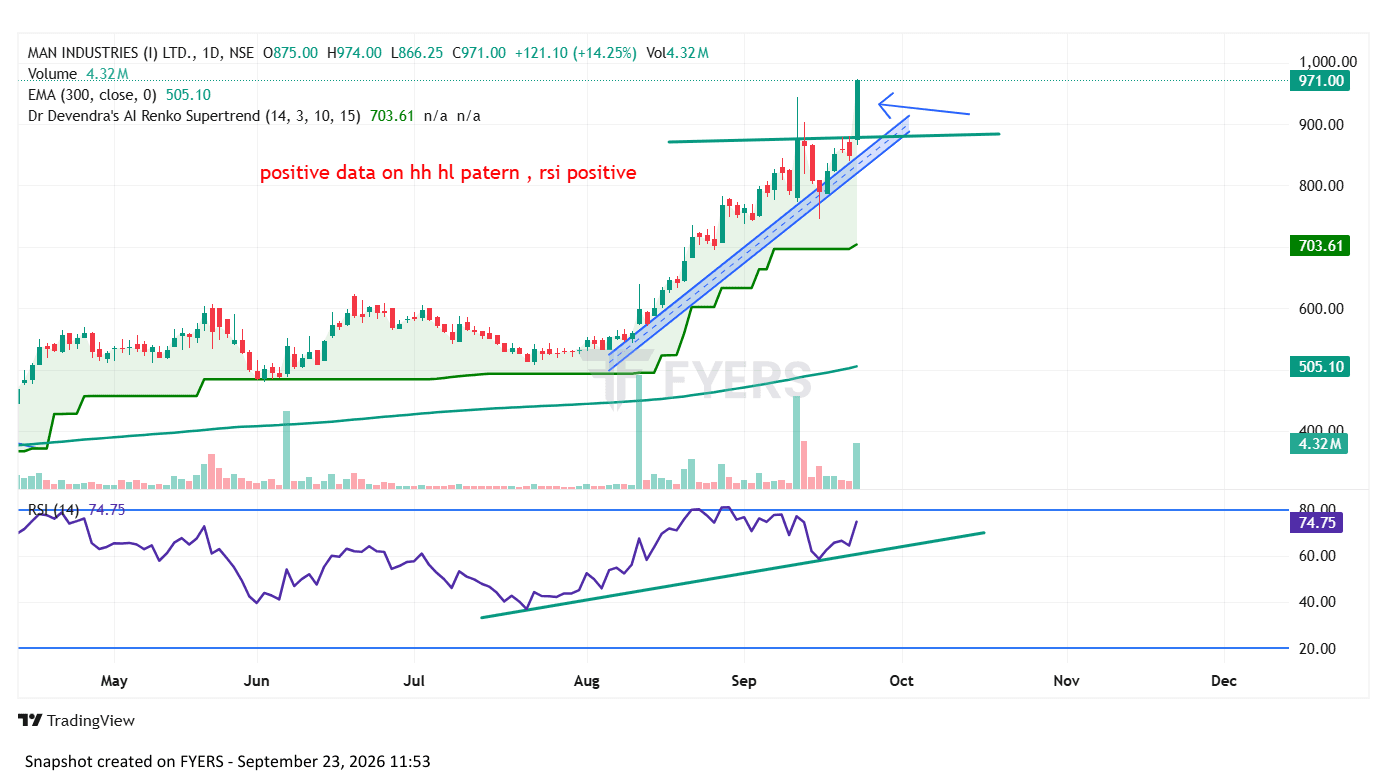
manufactures large-diameter carbon-steel line pipes
MANINDS
Strengths
Strong positioning in large-diameter line pipes and coating solutions.
Global exposure to oil & gas pipeline projects.
FY26 consolidated revenue was about ₹3,592.5 Cr, with EBITDA of ₹468 Cr and a record consolidated EBITDA margin of about 13%.
FY26 standalone EBITDA margin reached a record 14%, supported by product and geographic mix.
Strong order visibility: standalone order book was around ₹3,000 Cr at the beginning of FY27.
Company remained net-cash positive at FY26 year-end despite significant capex.
Weaknesses
Business is dependent on the cyclical oil & gas and infrastructure capex cycle.
Steel prices and raw-material costs can affect margins.
Project-based business can result in quarterly revenue volatility.
Working-capital requirements can increase during periods of rapid growth.
Large manufacturing expansion requires continued capital expenditure.
Opportunities
Increasing investment in oil & gas pipelines and energy infrastructure.
International pipeline projects can expand export opportunities.
Jammu greenfield stainless-steel seamless pipe plant is targeted for commercial production from March 2027, creating an additional growth avenue.
Higher-value products and optimisation of product mix can support margins.
India's infrastructure, energy-transition and industrial-pipeline requirements could provide additional demand.
Threats
Volatility in steel and other raw-material prices.
Delays or cancellations in large pipeline projects.
Competition from domestic and international pipe manufacturers.
Oil-price weakness could reduce upstream/midstream customer capex.
Foreign-exchange, trade-policy and geopolitical risks for international business.
Execution risk associated with new capacity.