Strengths
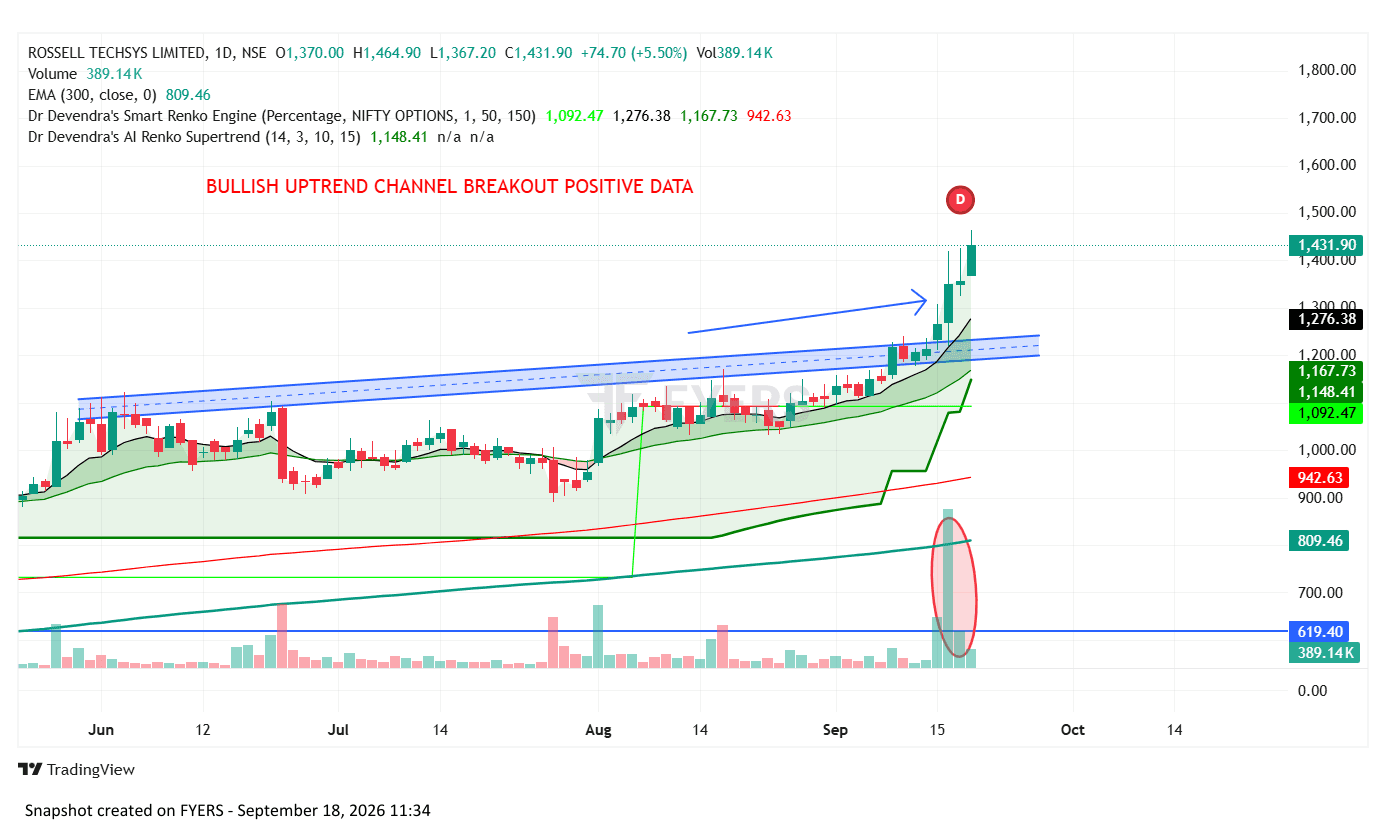
Strong growth momentum: FY26 revenue from operations reached ₹485.2 Cr, up 87% YoY.
Q1 FY27 revenue increased 77.1% YoY to ₹154.46 Cr, while profit after tax increased 116.5% YoY to ₹7.14 Cr.
Aerospace & defence remains the core growth engine, supported by execution for global OEMs and Tier-1 customers.
Weaknesses
The company is still in a rapid expansion phase, so capacity additions and execution remain important for maintaining growth.
A large portion of the business is linked to aerospace/defence programmes, where qualification and customer-programme timelines can be lengthy.
Profitability remains relatively modest compared with the pace of revenue growth.
Opportunities
Indian aerospace and defence manufacturing offers a long-term addressable market as global OEMs expand outsourcing and localisation.
Expansion of semiconductor manufacturing and assembly ecosystems can create additional opportunities for Rossell Techsys.
Space-sector development in India provides a new potential growth market.
Threats
Aerospace and defence programmes can face delays in qualification, certification, procurement and customer production schedules.
Dependence on global OEMs exposes the business to changes in customers' production plans and global aerospace cycles.
Semiconductor businesses face rapid technological change and strong global competition.
Supply-chain disruptions, specialised component availability and geopolitical issues could affect delivery schedules.
Expansion-related capex and execution risks could affect cash flows if programme ramp-ups are delayed.