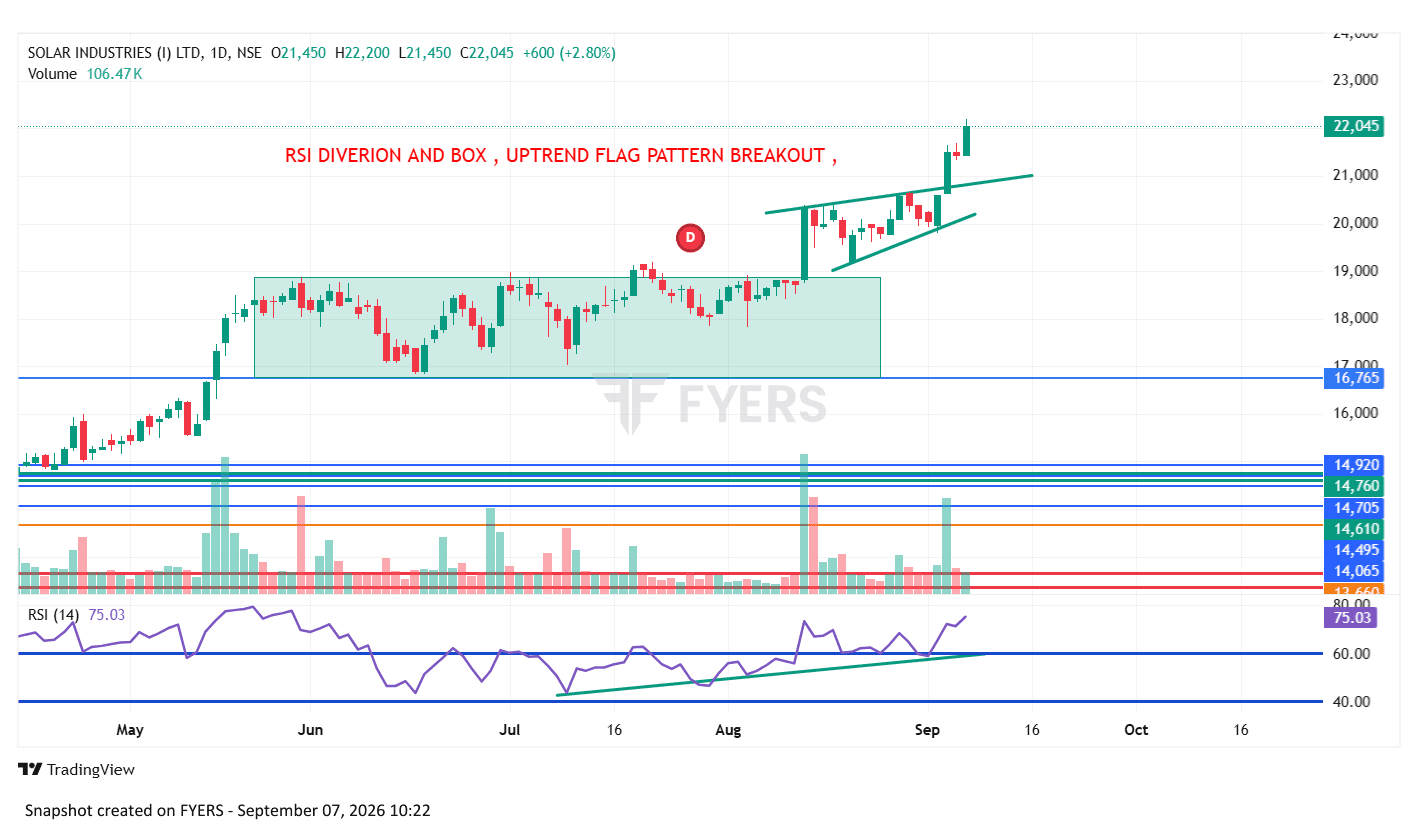
Solar Industries India
Sector: Explosives / Defence
SOLARINDS
Strengths
Strong financial growth: Q3 FY26 revenue reached a record ₹2,548 Cr, up 29% YoY, with EBITDA of ₹733 Cr and PAT of ₹467 Cr.
Strong defence business: Q3 FY26 defence revenue crossed ₹700 Cr, the company's highest quarterly defence revenue at that time.
Large order book: Consolidated order book crossed ₹21,000 Cr, including more than ₹18,000 Cr of defence orders, providing substantial medium-term visibility.
International presence: International business revenue exceeded ₹960 Cr in Q2 FY26, demonstrating growing global contribution.
Weaknesses
Defence execution dependence: A large part of the future growth story depends on successful execution of sizeable defence contracts.
Working-capital requirements: Large order books can require significant inventory, receivables and project-related capital.
Raw-material sensitivity: Explosives and defence manufacturing remain exposed to the cost and availability of key chemical and other inputs.
Opportunities
India's defence indigenisation: The government's emphasis on Make in India and reducing defence imports creates a significant opportunity for domestic defence manufacturers.
Large defence pipeline: The company's ₹18,000+ Cr defence order book provides substantial revenue visibility if execution remains on schedule.
Ammunition and missile systems: Growing domestic demand for ammunition, propulsion systems and defence technologies can expand Solar's addressable market.
Threats
Defence execution delays: Delays in government procurement, testing or deliveries could postpone revenue recognition.
Regulatory risk: Explosives and defence products are highly regulated businesses requiring strict compliance.
Geopolitical risk: International operations can be affected by sanctions, trade restrictions and geopolitical tensions.