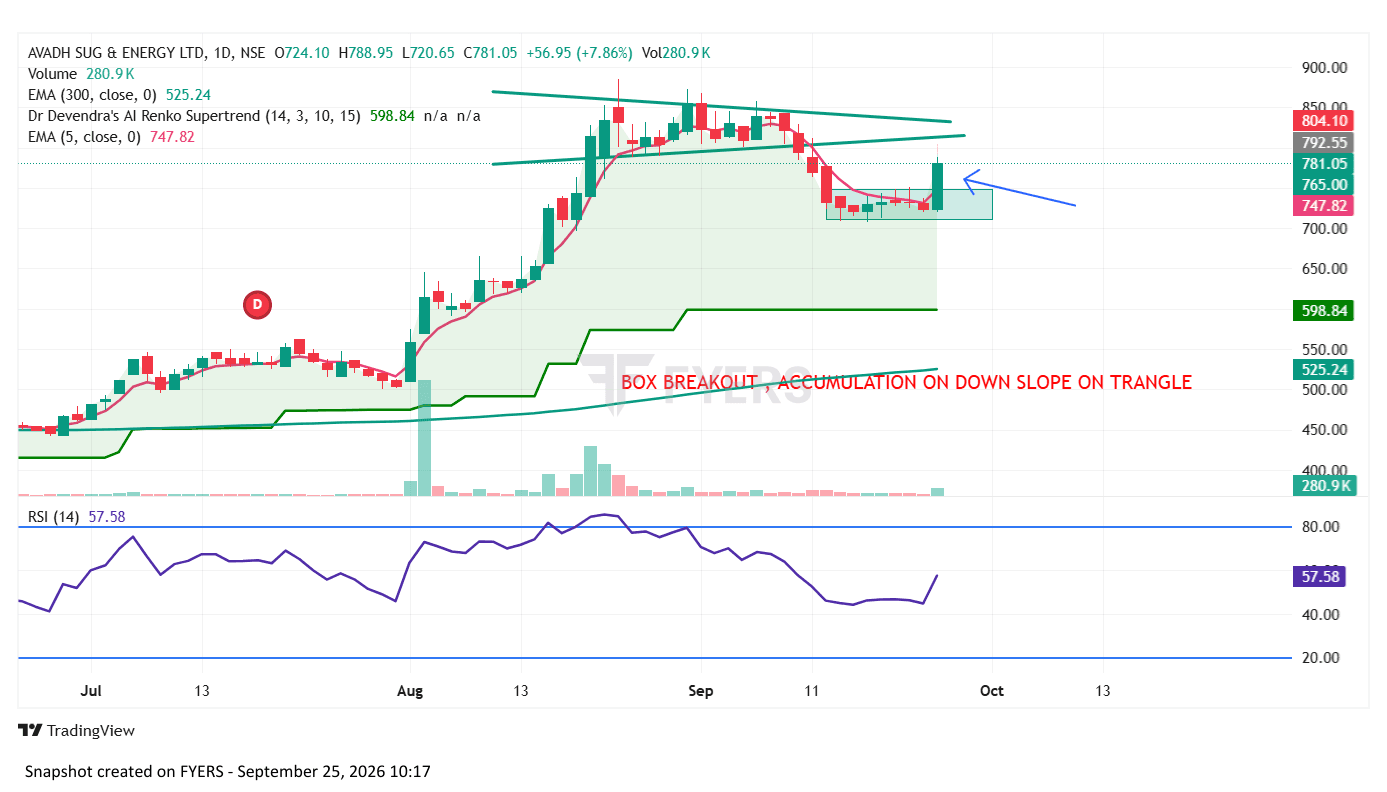
sugar and its by-products, spirits including ethanol
AVADHSUGAR
Strengths
Diversified sugar-industry model covering sugar, ethanol/distillery and co-generation power.
Established manufacturing presence in Uttar Pradesh.
Hargaon unit's cane-crushing capacity was increased from 10,000 TCD to 13,000 TCD, operational from Sugar Season 2025–26.
FY26 revenue from operations increased to approximately ₹2,694 Cr from ₹2,636 Cr.
FY26 finance cost reduced substantially to about ₹74 Cr from ₹136 Cr in FY25.
Board recommended ₹10 per share dividend for FY26.
Weaknesses
Sugar profitability is highly dependent on sugar prices, cane costs, recovery rates and government policy.
FY26 EBITDA declined to ₹226 Cr from ₹280 Cr.
FY26 PAT declined to ₹57 Cr from ₹88 Cr.
Profitability can fluctuate significantly between sugar cycles.
High working-capital requirements are inherent in the sugar business.
Opportunities
Expansion of ethanol blending and India's growing biofuel requirement.
Higher cane-crushing capacity can support volume growth.
Better sugar realisations could improve mill profitability.
Co-generation provides an additional revenue stream from bagasse.
Improved cane recovery and operational efficiency can support margins.
Continued reduction in finance costs could improve bottom-line performance.
Threats
Increase in sugarcane SAP without corresponding increases in sugar/ethanol prices can pressure margins.
Weather conditions, drought, floods and cane disease can affect sugarcane availability.
Government controls on sugar exports, domestic prices and ethanol allocation can affect profitability.
Sugar-price volatility.
Rising labour, power and agricultural-input costs.
Lower sugar recovery rates can negatively affect production economics.