Tech M provides IT consulting, digital transformation
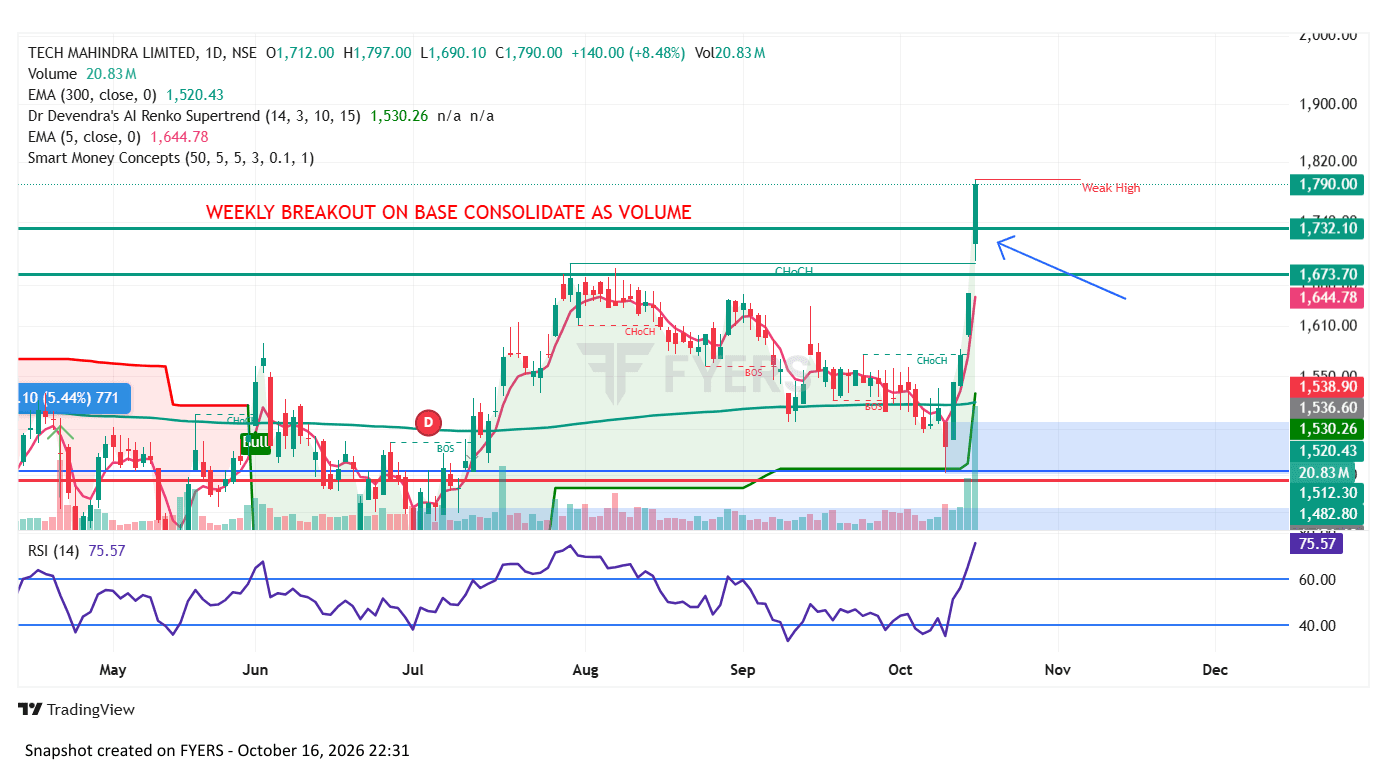
TECHM
Strengths
- Improving profitability: Q2 FY27 EBIT rose 40.5% year-on-year, faster than revenue, indicating improved operating leverage.
- Global customer base: Operations across multiple countries and industries provide access to enterprise technology spending.
- Large deal momentum: New deal wins totalled US$1.023 billion in Q2 FY27, supporting potential future revenue growth.
- Shareholder returns: The board declared an interim dividend of ₹15 per share and approved a 1:1 bonus issue.
Weaknesses
- Communications-sector exposure: Dependence on telecom clients can make performance sensitive to industry-specific spending and pricing cycles.
- Margin recovery still in progress: The company is targeting a 15% operating margin for FY27, so execution is required to achieve the goal.
- Competitive pricing: Large IT contracts can require aggressive pricing, which may limit profitability.
Opportunities
- Artificial intelligence: AI-enabled consulting, software modernisation and automation can create new projects and improve delivery productivity.
- Large-deal execution: Converting recent contract wins into revenue could strengthen growth visibility.
- Bonus issue: The approved 1:1 bonus issue will increase the number of shares held by eligible shareholders, but does not by itself increase the value of their holdings or the company's market capitalisation.
Threats
- Global IT spending slowdown: Economic uncertainty may delay discretionary technology projects.
- AI-led disruption: AI may create new demand but also put pressure on traditional labour-based IT services and billing models.
- Intense competition: TCS, Infosys, HCLTech, Wipro and global consulting firms compete for similar contracts.
- Wage and currency risks: Salary inflation, foreign-exchange movements and changing delivery costs can affect margins.