‹ All Posts
AASHISH RA

17th Sep · SEBI Registration INH000013174

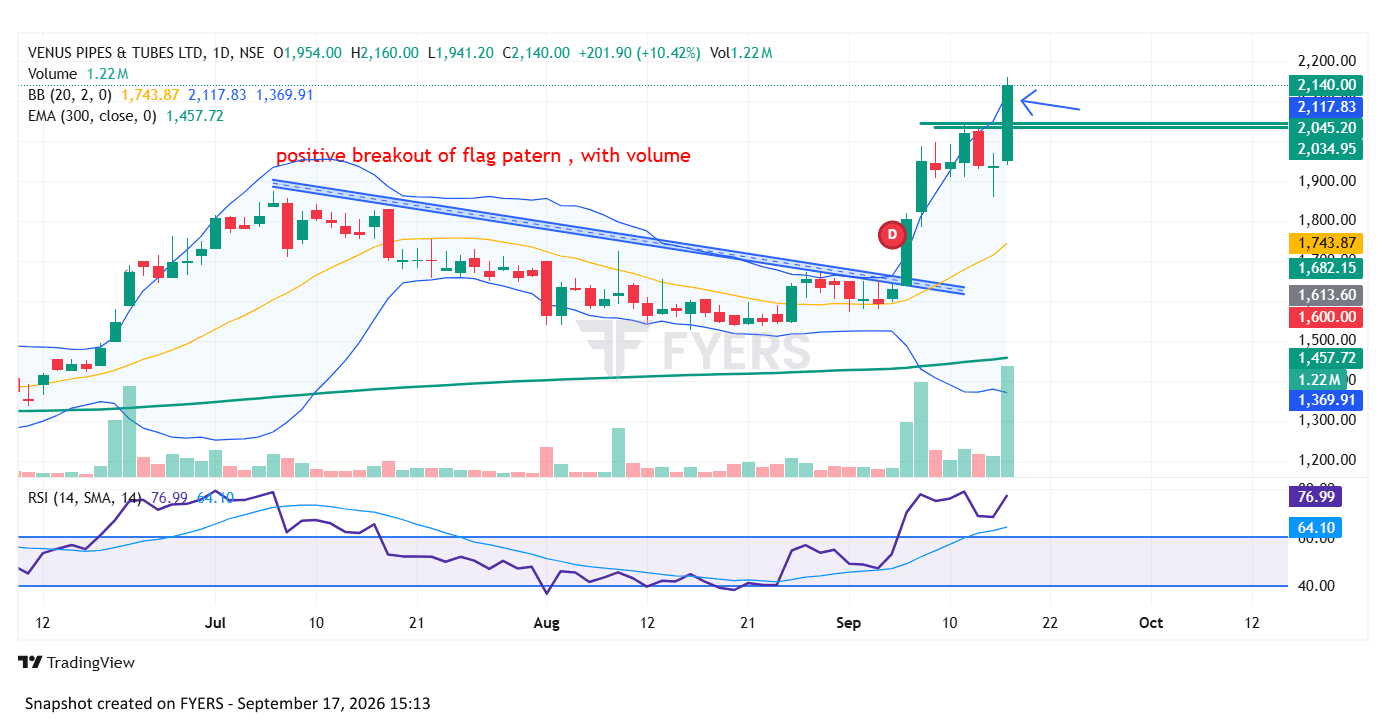
Venus Pipes & Tubes Ltd — SWOT Analysis NSE: VENUSPIPES
VENUSPIPES
Strengths Strong growth in Q1 FY27: revenue from operations ₹320.5 Cr, +16% YoY.  EBITDA was about ₹54.2 Cr, with EBITDA margin around 16.9%.  Domestic business showed strong momentum, while the company has exposure to power, chemicals, oil & gas and other industrial sectors.  Product expansion into fittings and value-added engineering solutions can improve the product mix. Company has a substantial order pipeline; recent research commentary cited an order book of roughly ₹600 Cr.  Weaknesses Q1 FY27 PAT increased only 6.6% YoY to ₹26.4 Cr, considerably slower than revenue growth.  Raw-material costs remain a major component of expenses, making margins sensitive to stainless-steel prices.  Expansion requires significant capital expenditure and increases execution/working-capital requirements. Export performance can be affected by global trade conditions and geopolitical disruptions. Opportunities Data-centre infrastructure: Venus is entering pipe-spooling, with a planned investment of about ₹70 Cr and an LOI worth ₹185 Cr reported for the business.  Expansion in oil & gas, power, chemicals, hydrogen and nuclear applications. Fittings and other value-added products can increase contribution from higher-margin products. Rising domestic infrastructure and industrial capex can support long-term demand. Management has maintained FY27 revenue-growth guidance of around 20%, according to the Q1 FY27 earnings summary.  Threats Stainless-steel/raw-material price volatility can pressure EBITDA margins. Competition from domestic and international pipe manufacturers. Weak global demand or geopolitical issues could affect exports. Large capex projects create execution and utilisation risks. Any slowdown in industrial, oil & gas or infrastructure capex could reduce order inflows.

#EquityResearch#PersonalFinance#HiddenGems#Pre-OpeningCommentary
VENUSPIPES-EQ_2026-09-17_15-13-08.png
932 likes·76 comments