Elecon Engineering Company Ltd. (ELECON) has delivered another strong quarter, driven by robust order inflows and margin expansion in its transmission and material‑handling segments. The company continues to benefit from industrial capex recovery and government infrastructure spending.
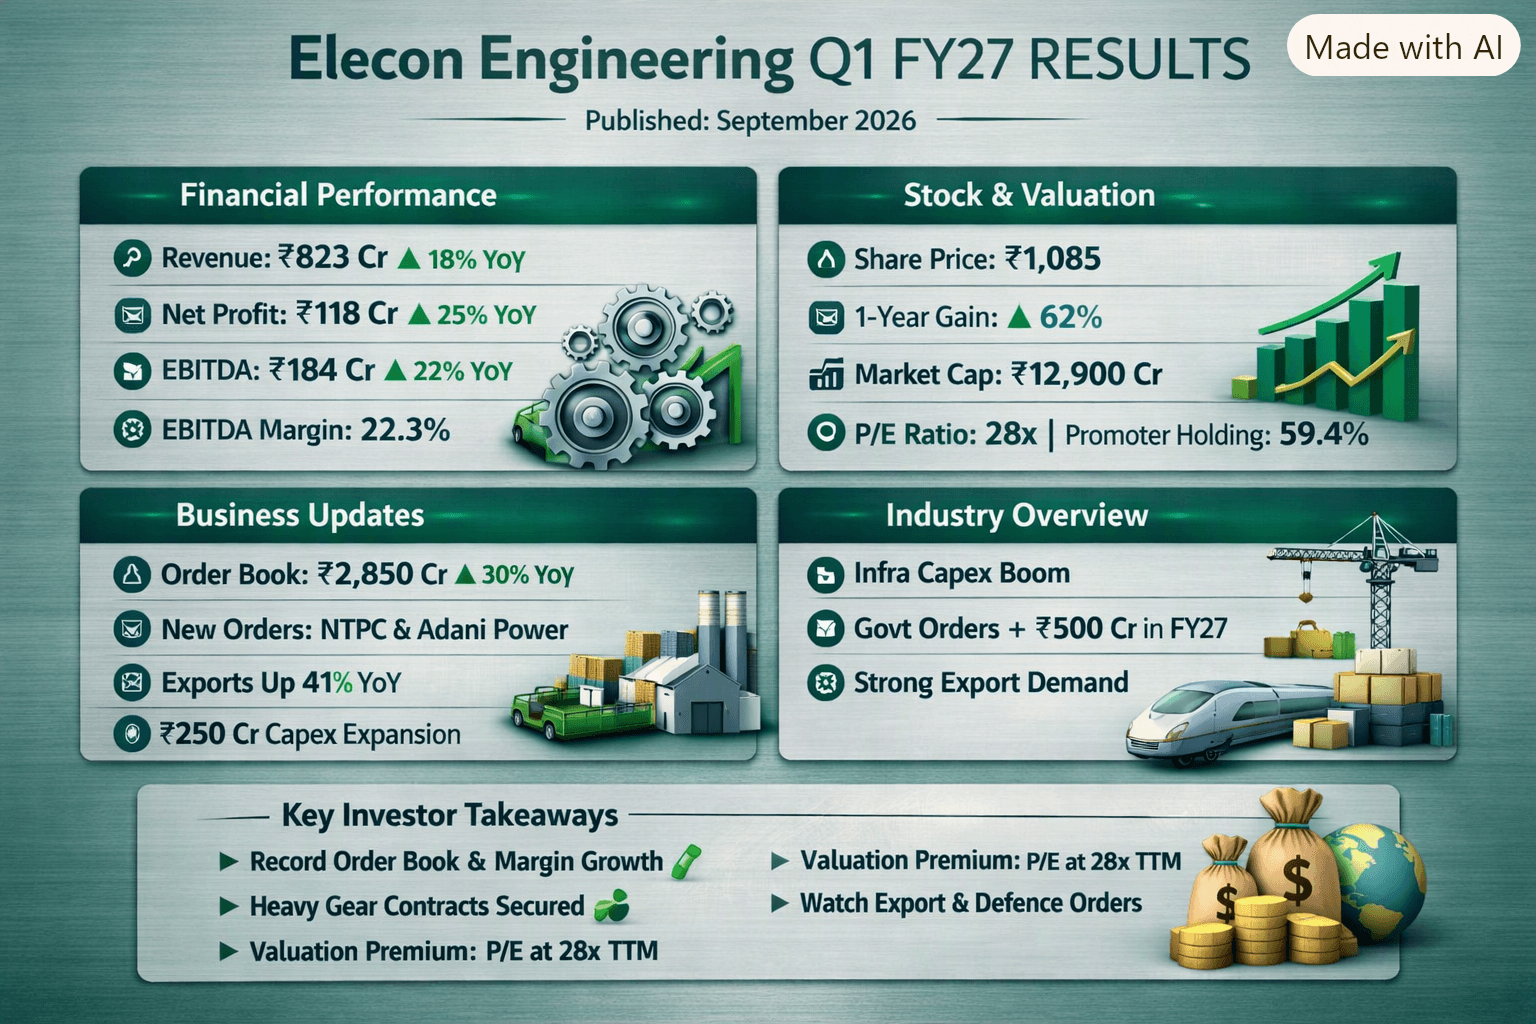
⚙️ Elecon Engineering Q1 FY27 Highlights (September 2026)
💰 Financial Performance
Revenue: ₹ 823 crore (▲ 18% YoY)
EBITDA: ₹ 184 crore (▲ 22% YoY)
EBITDA Margin: 22.3% vs 21.5% last year
Net Profit: ₹ 118 crore (▲ 25% YoY)
EPS: ₹ 10.2 vs ₹ 8.1 YoY
📈 Stock & Valuation
NSE Price (23 Sept 2026): ₹ 1,085
1‑Year Gain: + 62%
Market Cap: ₹ 12,900 crore
P/E Ratio: ≈ 28× TTM
Promoter Holding: 59.4%
🏗️ Business Updates
Order Book: ₹ 2,850 crore (▲ 30% YoY)
New Orders: Heavy gear contracts from NTPC and Adani Power
Exports: Up 41% YoY — strong traction in Europe and Middle East
Capex Plan: ₹ 250 crore for capacity expansion in Vallabh Vidyanagar plant
Subsidiary Performance: Elecon Transmission showed record operating profit
🌍 Industry Context
Industrial Capex Cycle: Revival in steel, cement, and power sectors boosting gear demand
Government Infra Push: Railways and defence orders expected to add ₹ 500 crore in FY27
Peers: Triveni Engineering, Greaves Cotton also reporting double‑digit growth
💡 Investor Takeaways
Strong execution visibility with record order book
Margin expansion trend likely to continue through FY27
Valuation premium justified by steady earnings growth
Watch for: Export momentum and new defence gear contracts