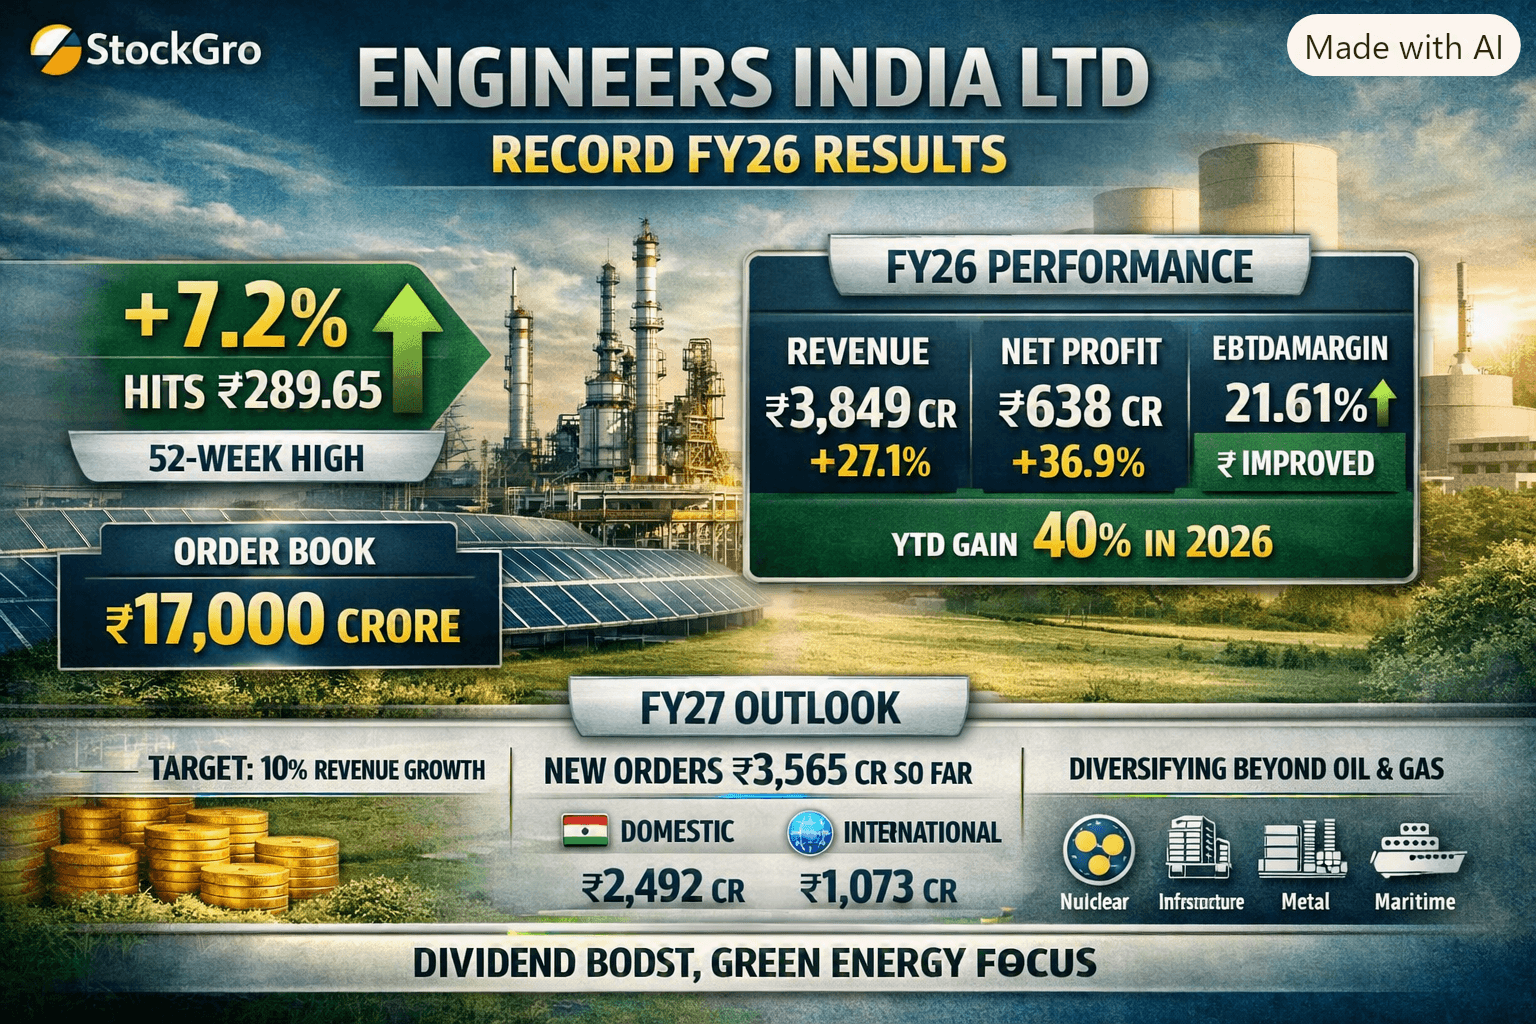
Engineers India Ltd (EIL) shares traded to ₹289.65 on September 21, 2026, hitting a 52‑week high after the company reported record FY26 results and a robust ₹17,000‑crore order book. Net profit jumped 36.9% year‑on‑year to ₹638 crore, and management guided for 10% revenue growth in FY27.
📈 Market Snapshot
Stock Movement: Up 7% to ₹289.65 on BSE.
YTD Gain: Over 40% in 2026.
Market Cap: Around ₹16,000 crore.
52‑Week Range: ₹170 – ₹289.65.
Investor Sentiment: Strong buying after record FY26 performance and optimistic FY27 outlook.
💼 FY26 Performance Highlights
Metric FY25 FY26 Change
Revenue from Operations ₹3,031 crore ₹3,849 crore ↑ 27.1%
Net Profit ₹466 crore ₹638 crore ↑ 36.9%
Operating Margin 14.76% 16.22% Improved
EBITDA Margin 20.60% 21.61% Improved
Order Book (FY26‑end) ₹15,109 crore ₹17,000 crore (current) ↑ 12.5%
🔧 Q1 FY27 Snapshot
Standalone Revenue: ₹800.9 crore (↓ 6.6% YoY)
Consolidated Revenue: ₹819.8 crore (↓ 5.8% YoY)
Consolidated Net Profit: ₹157.9 crore (↑ 141% YoY)
Segment Profit: Consultancy ₹119.7 crore; Turnkey ₹22.7 crore.
Revenue Mix: ~55% Consultancy / 45% EPC (expected to normalize as EPC execution picks up).
🌍 Strategic Outlook
FY27 Target: 10% revenue growth; maintain 14–16% operating margin.
New Orders Secured (FY27 so far): ₹3,565 crore
Domestic ₹2,492 crore
International ₹1,073 crore.
Diversification Focus: Expanding beyond oil & gas into metals, nuclear energy, infrastructure, data centres, fertilisers, and maritime projects.
CMD Atul Gupta: Expects order inflows to accelerate in later quarters as EPC contribution rises.
⚠️ Investor Takeaways
Positive Drivers:
Record FY26 earnings and margin expansion.
Strong ₹17,000‑crore order book ensures visibility.
Diversification reduces sectoral risk.
Risks:
Short‑term revenue softness in Q1 FY27.
Dependence on government and oil‑sector projects.
Global geopolitical tensions may affect overseas orders.