Entero Healthcare Solutions has reported a strong Q2 FY27
ENTERO
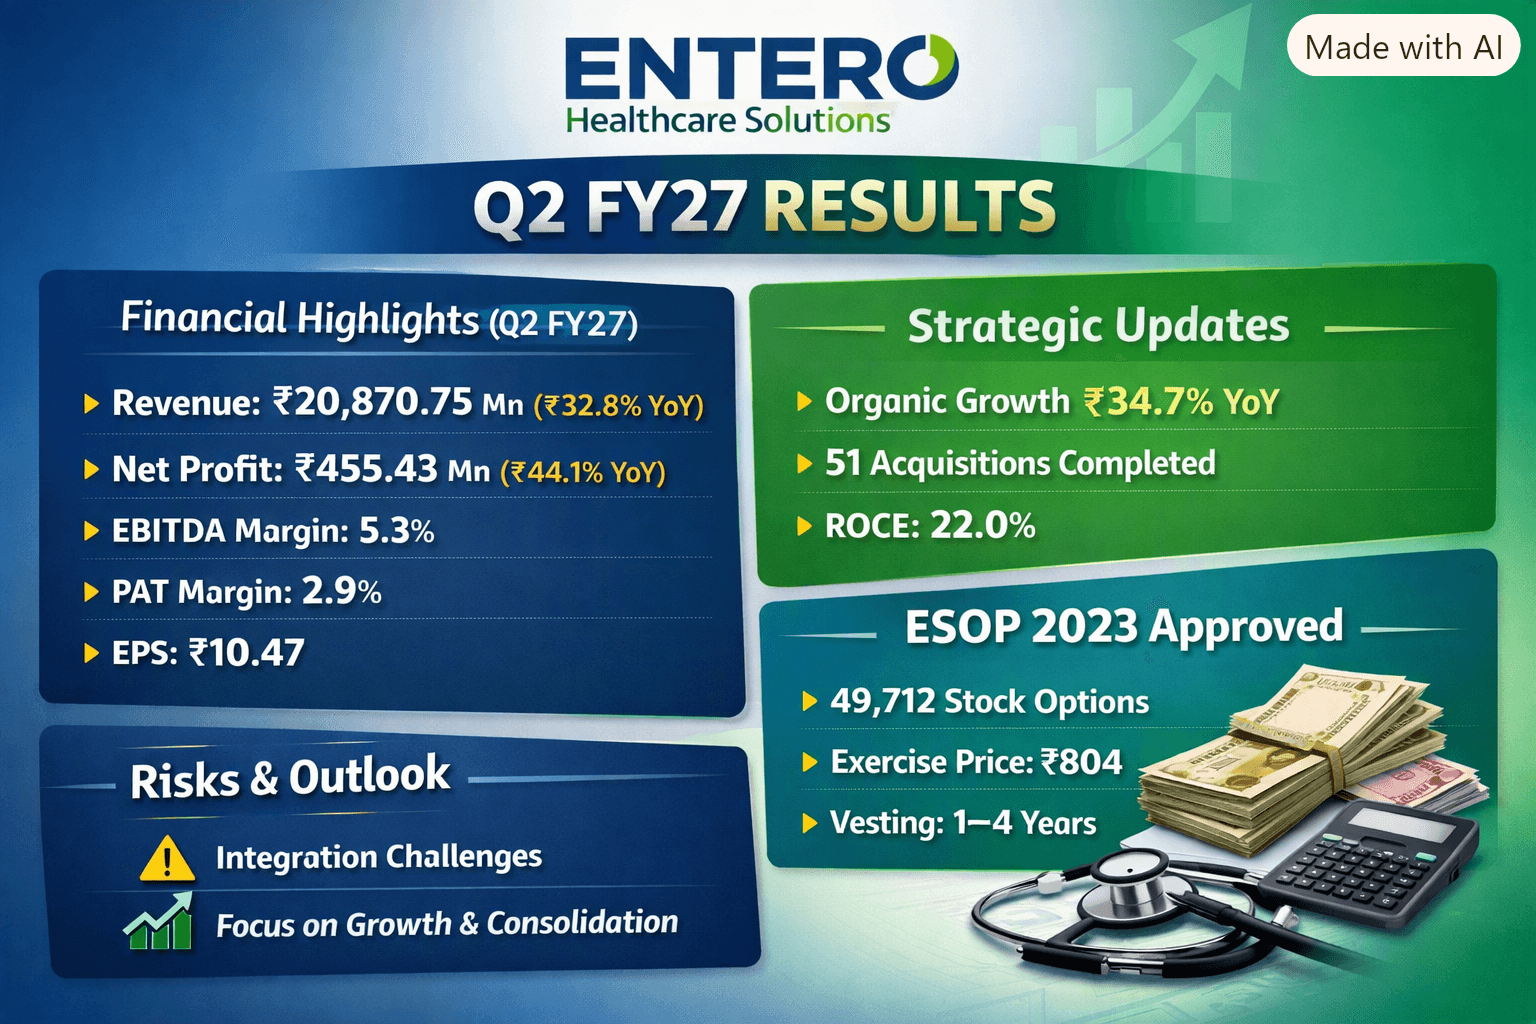
Entero Healthcare Solutions has reported a strong Q2 FY27 performance with revenue up 32.8% YoY to ₹20,870.75 million and net profit jumping 44.1% to ₹455.43 million. The company also approved the grant of 49,712 employee stock options under its ESOP 2023 plan.
📊 Key Financial Highlights (Q2 FY27, ended Sept 30, 2026)
Revenue (Consolidated): ₹20,870.75 million (up 32.8% YoY)
Net Profit: ₹455.43 million (up 44.1% YoY)
Standalone Income: ₹1,366.53 million; Profit Before Tax ₹243.19 million
EBITDA Margin: 5.3% (improved from 5.0% last year)
PAT Margin: 2.9%
EPS: ₹10.47 (up from ₹7.26 last year)
📈 Strategic & Operational Updates
Organic Growth: Revenue grew 34.7% YoY on a like-for-like basis, outpacing industry growth.
Acquisitions: Entero has completed 51 acquisitions since inception, continuing its consolidation strategy in India’s fragmented healthcare distribution market.
Efficiency Gains: Gross margin improved by 136 bps to 11.5%, and ROCE rose to 22.0%.
Net Working Capital Days: Reduced to 64 days, showing better cash flow management.
👥 Employee Stock Option Plan (ESOP 2023)
Grant Approved: 49,712 options
Exercise Price: ₹804 per option
Vesting: 1–4 years, with an 8-year exercise window
Purpose: Long-term retention and compliance with SEBI regulations
📌 Market Context
Stock Performance: Entero Healthcare shares are trading in a bullish trend, with recent prices around ₹1,820 on NSE/BSE.
Investor Focus: Integration of acquisitions and debt management remain key watchpoints.
Trading Window: Opens 48 hours after financial disclosure (Nov 6, 2026).
⚠️ Risks & Outlook
Risks:
Integration challenges from multiple acquisitions
Rising operational costs and debt management during expansion
Outlook:
Sustained demand in pharma and surgical distribution
Continued focus on organic growth and market consolidation
Investors should track management commentary on capital allocation and growth sustainability