‹ All Posts
Amit Malviya

1 hour ago · SEBI Registration INH000020615

HSCL Q2 Profit Surges 31% on Strong Revenue
HSCL
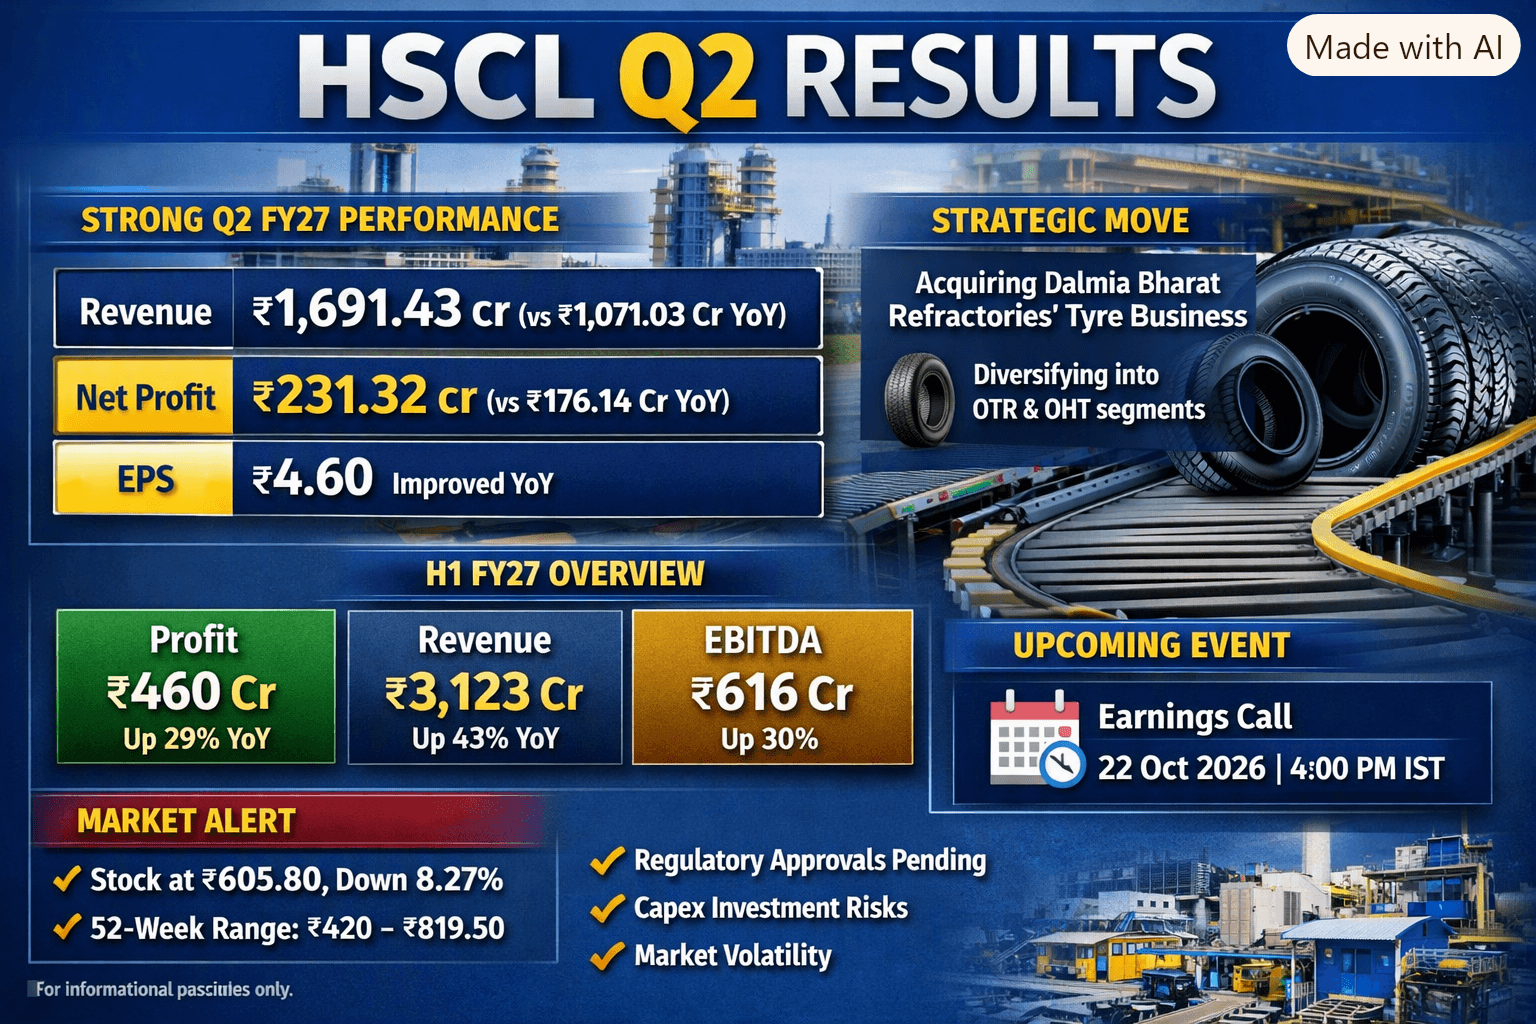
Himadri Speciality Chemical Ltd (HSCL) has reported strong Q2 FY27 results with net profit rising to ₹231.32 crore, up from ₹176.14 crore last year, and revenue jumping to ₹1,691.43 crore. The company also announced a strategic acquisition of Dalmia Bharat Refractories’ tyre business via demerger. 📊 Latest Financial Highlights Q2 FY27 Revenue: ₹1,691.43 crore (vs ₹1,071.03 crore last year) Net Profit: ₹231.32 crore (vs ₹176.14 crore last year) EPS: ₹4.60 (improved YoY) Core Segment Contribution: Carbon materials & chemicals generated ₹1,539.02 crore revenue 🏭 Strategic Developments Acquisition: HSCL Board approved a Scheme of Arrangement to acquire the tyre business of Dalmia Bharat Refractories Ltd (DBRL) via demerger. Objective: Diversify into tyre manufacturing, expand footprint in OTR (off-the-road) and OHT (off-highway tyre) segments. Regulatory Watch: Integration depends on statutory approvals; delays could affect timelines. 📈 Broader Performance (H1 FY27) Half-Year Profit: ₹460 crore, up 29% YoY. Revenue: ₹3,123 crore, up 43% YoY. EBITDA: ₹616 crore, up 30%. Capex Plans: ₹1,300 crore for FY27, plus ₹1,500 crore investment cycle next year. Upcoming Project: India’s first commercial carbon nanotube manufacturing plant. 📉 Market Reaction Stock Price (Oct 19, 2026): ₹605.80 on BSE, down 8.27%. Trend: Moderately bearish in short term, despite strong fundamentals. 52-Week Range: ₹420.00 – ₹819.50. 🔎 Key Risks & Watchpoints Regulatory Approvals: Critical for DBRL tyre business integration. Capex Execution: Large-scale investments in advanced materials and battery ecosystem carry execution risks. Market Volatility: Despite strong earnings, stock price shows bearish sentiment—investors should monitor technical trends. 📅 Upcoming Events Earnings Call: Scheduled for 22 October 2026 at 4:00 PM IST to discuss Q2 & H1 FY27 results.

#WatchOutFor#StockInNews#EquityResearch#TechnicalViews
hscl.png
25 likes·25 comments