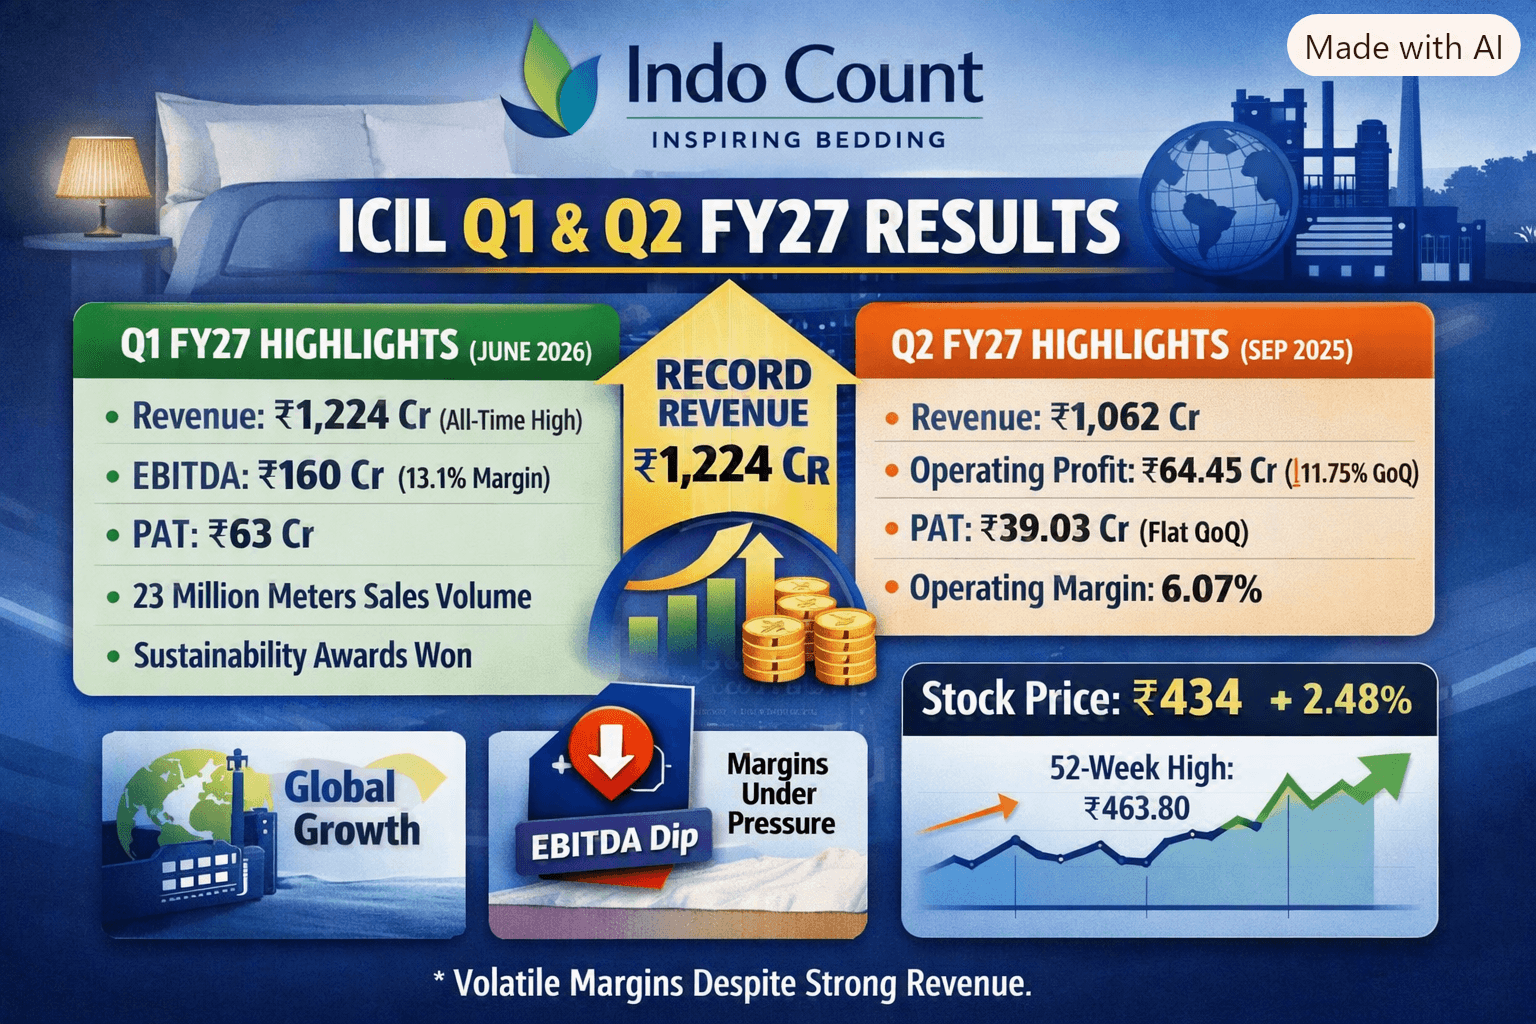
Indo Count Industries Limited (ICIL) reported strong Q1 FY27 results with record revenue of ₹1,224 crore, EBITDA margin recovery to ~13.1%, and PAT of ₹63 crore. However, Q2 FY27 (Sep 2025 quarter) showed margin pressure, with operating profit down 11.75% QoQ to ₹64.45 crore and PAT flat at ₹39.03 crore, despite revenue of ₹1,062 crore. The stock remains bullish, trading around ₹434 as of late August 2026.
📊 Q1 FY27 Highlights (Quarter ended June 2026)
Revenue: ₹1,224 crore (all-time high consolidated quarterly revenue)
EBITDA: ₹160 crore (~13.1% margin, recovery from earlier quarters)
PAT: ₹63 crore
Sales Volume: 23 million meters
New Business Contribution: ~33% of total revenue
Global Operations: U.S. utility bedding facilities reached 60–65% utilization despite new facility ramp-up
Awards: Received 3 CITI Textile Sustainability Awards 2026 for energy efficiency, ESG integration, and responsible cotton sourcing
Guidance: On track for FY27 revenue target of ₹5,500 crore with ~13% EBITDA margin
📉 Q2 FY27 Highlights (Quarter ended Sep 2025)
Total Income: ₹1,062.14 crore (down 10.79% QoQ)
Operating Profit: ₹64.45 crore (down 11.75% QoQ, down 51.29% YoY)
PAT: ₹39.03 crore (flat QoQ, down 52.14% YoY)
Operating Margin: 6.07% (significant margin compression)
EPS: ₹1.97 (down from ₹3.19 in Q1 FY27)
Expenses: Operating expenses rose to ₹997.68 crore, impacting profitability
📈 Market & Stock Performance
BSE Price (Aug 28, 2026): ₹434.25 (+2.48%)
NSE Price: ₹434.95 (+2.73%)
52-Week Range: ₹217.25 – ₹463.80
Trend: Strong bullish momentum in long-term charts; short-term moderately bullish
⚠️ Risks & Watchpoints
Margin Pressure: Despite record revenue, profitability is under stress due to rising operating expenses.
Global Uncertainty: Textile demand depends on trade agreements and U.S./EU tariff scenarios.
Execution Risk: Scaling new businesses while maintaining margins is critical.