Lumax Auto Technologies (LUMAXTECH) has reported a stellar Q1 FY27
LUMAXTECH
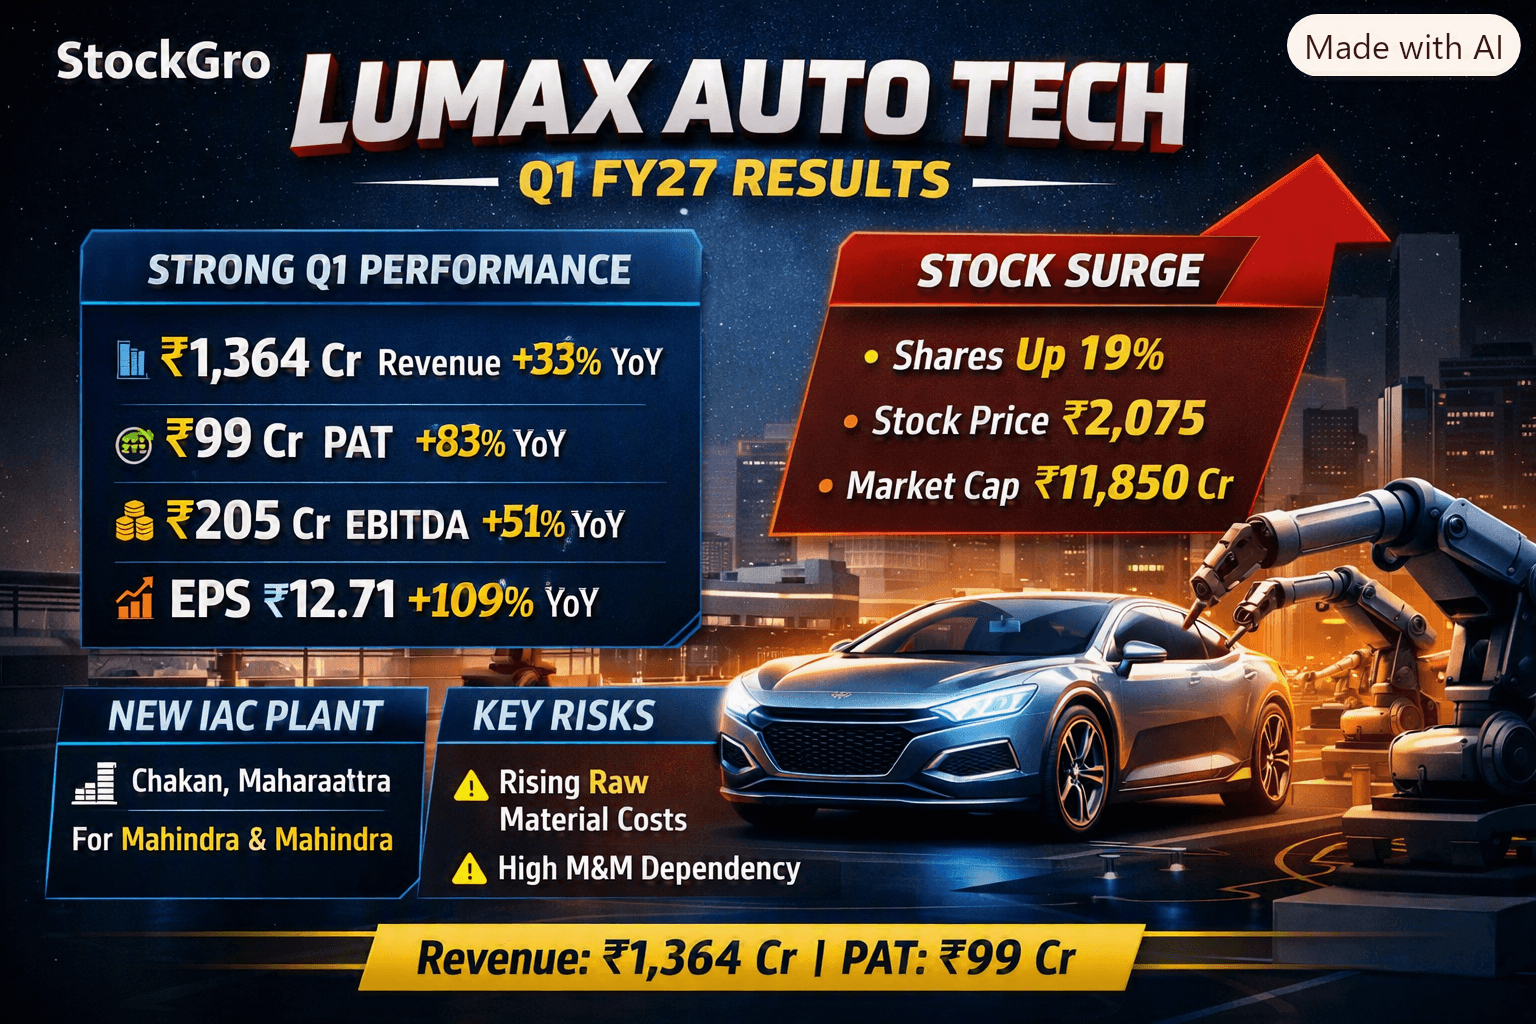
Lumax Auto Technologies (LUMAXTECH) has reported a stellar Q1 FY27 performance with profit after tax (PAT) surging ~83% YoY to ₹99 crore and revenue rising 33% YoY to ₹1,364 crore. Shares rallied nearly 19% to ₹2,075 on BSE following the results.
📊 Key Financial Highlights (Q1 FY27)
Revenue: ₹1,364 crore (+33% YoY)
PAT: ₹99 crore (+83% YoY)
EBITDA: ₹205 crore (+51% YoY)
EBITDA Margin: 15.1% (+190 bps YoY)
EPS: ₹12.71 (+109% YoY)
🏭 Strategic Developments
New Manufacturing Plant:
Location: Chakan, Maharashtra
Division: Intelligent Ambient Comfort (IAC)
Client: Mahindra & Mahindra (M&M)
Timeline: Phase 1 by Q4 FY27, Phase 2 by Q1 FY28
Capex: ₹156 crore approved for the IAC plant.
JV Divestment: Completed to streamline operations and focus on core growth.
📈 Market Reaction
Stock Price: Jumped 19% to ₹2,075 on BSE post-results.
Market Cap: ~₹11,850 crore.
Industry Context: Auto industry production grew 22% YoY, supporting component demand.
⚠️ Risks & Watchpoints
Raw Material Costs: Polymer inflation pushed material costs up 209 bps YoY.
Customer Concentration: M&M contributes ~27% of revenue, posing dependency risk.
Employee Costs: Up 7.7% QoQ due to compliance with new Labour Codes.
📌 Quick Take for Investors
Positives: Strong revenue growth, margin expansion, deleveraging, and new plant for premium products.
Concerns: Rising input costs and high reliance on M&M.
Outlook: Premiumization of vehicles and advanced tech adoption likely to sustain growth momentum