PNB’s strong Q2 results have boosted investor sentiment
PNB
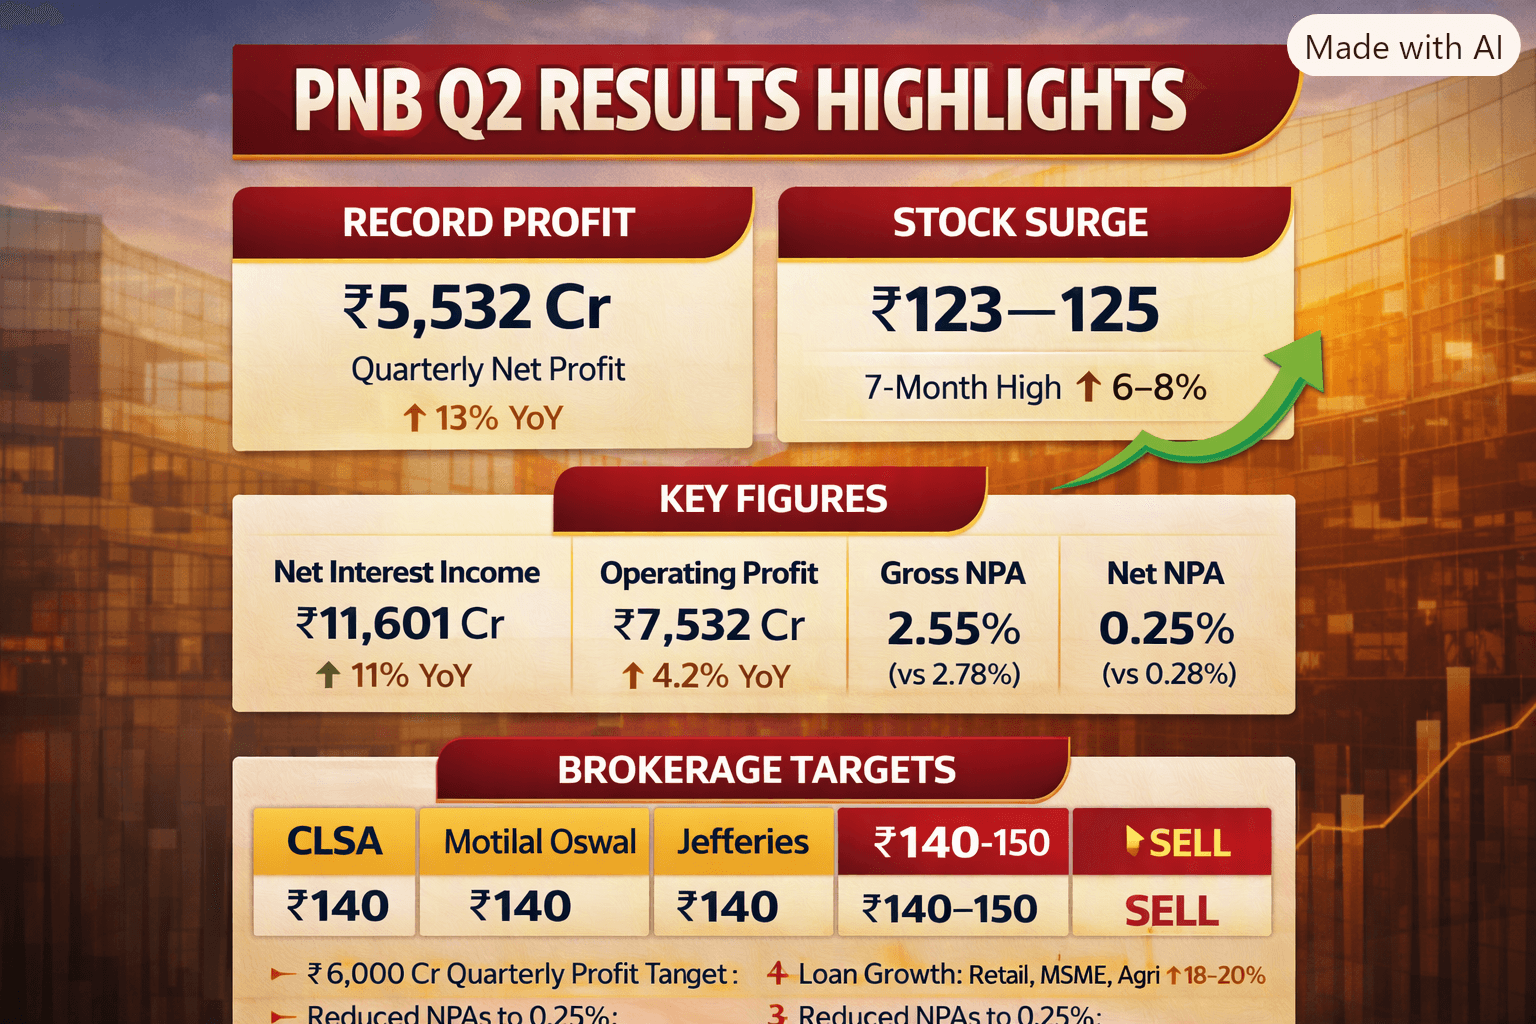
Punjab National Bank (PNB) has reported its highest-ever quarterly net profit of ₹5,532 crore in Q2 FY27, up 13% YoY, driving its stock up over 6–8% to a seven-month high. Brokerages are split: CLSA and Motilal Oswal have raised targets to ₹140, while Citi maintains a sell rating.
📊 Key Financial Highlights (Q2 FY27)
Net Profit: ₹5,532 crore (↑13% YoY)
Net Interest Income (NII): ₹11,601 crore (↑11% YoY)
Operating Profit: ₹7,532 crore (↑4.2% YoY)
Net Interest Margin (NIM): 2.58% (vs. 2.50% last quarter)
Gross NPA Ratio: 2.55% (improved from 2.78%)
Net NPA Ratio: 0.25% (vs. 0.28% last quarter)
📈 Market Reaction
PNB Share Price: Jumped 6–8% to ₹123–₹125 on NSE/BSE, hitting a seven-month high.
Market Cap: ~₹1.41 lakh crore.
PSU Bank Index: Up 2% overall, with PNB leading gains.
🏦 Strategic Outlook
Profit Target: Management aims to reach ₹6,000 crore quarterly profit in coming quarters.
Core Operating Profit: Grew ~29% YoY, showing strength beyond treasury gains.
Loan Growth:
Retail loans ↑16%
MSME advances ↑19–20%
Agriculture lending ↑18%
Treasury Losses: Absorbed ~₹1,000 crore decline in treasury income but still maintained profit growth.
📌 Brokerage Views
Brokerage Rating Target Price Notes
CLSA Accumulate ₹140 Raised from ₹135, citing asset quality improvement.
Motilal Oswal Buy ₹140 Strong quarter, controlled provisions, margin expansion.
Jefferies Buy ₹140–₹150 Profit beat estimates, NIM upside, lower provisions.
Elara Capital Buy ₹140 Positive operating performance, RoA >1% guidance.
Citi Sell ₹110 Raised target but cautious on long-term outlook.
⚠️ Risks & Considerations
Treasury income volatility could impact future quarters.
Asset quality improvements are promising, but slippages in corporate accounts remain a watchpoint.
Brokerage divergence (Buy vs. Sell ratings) signals uncertainty in long-term valuation.