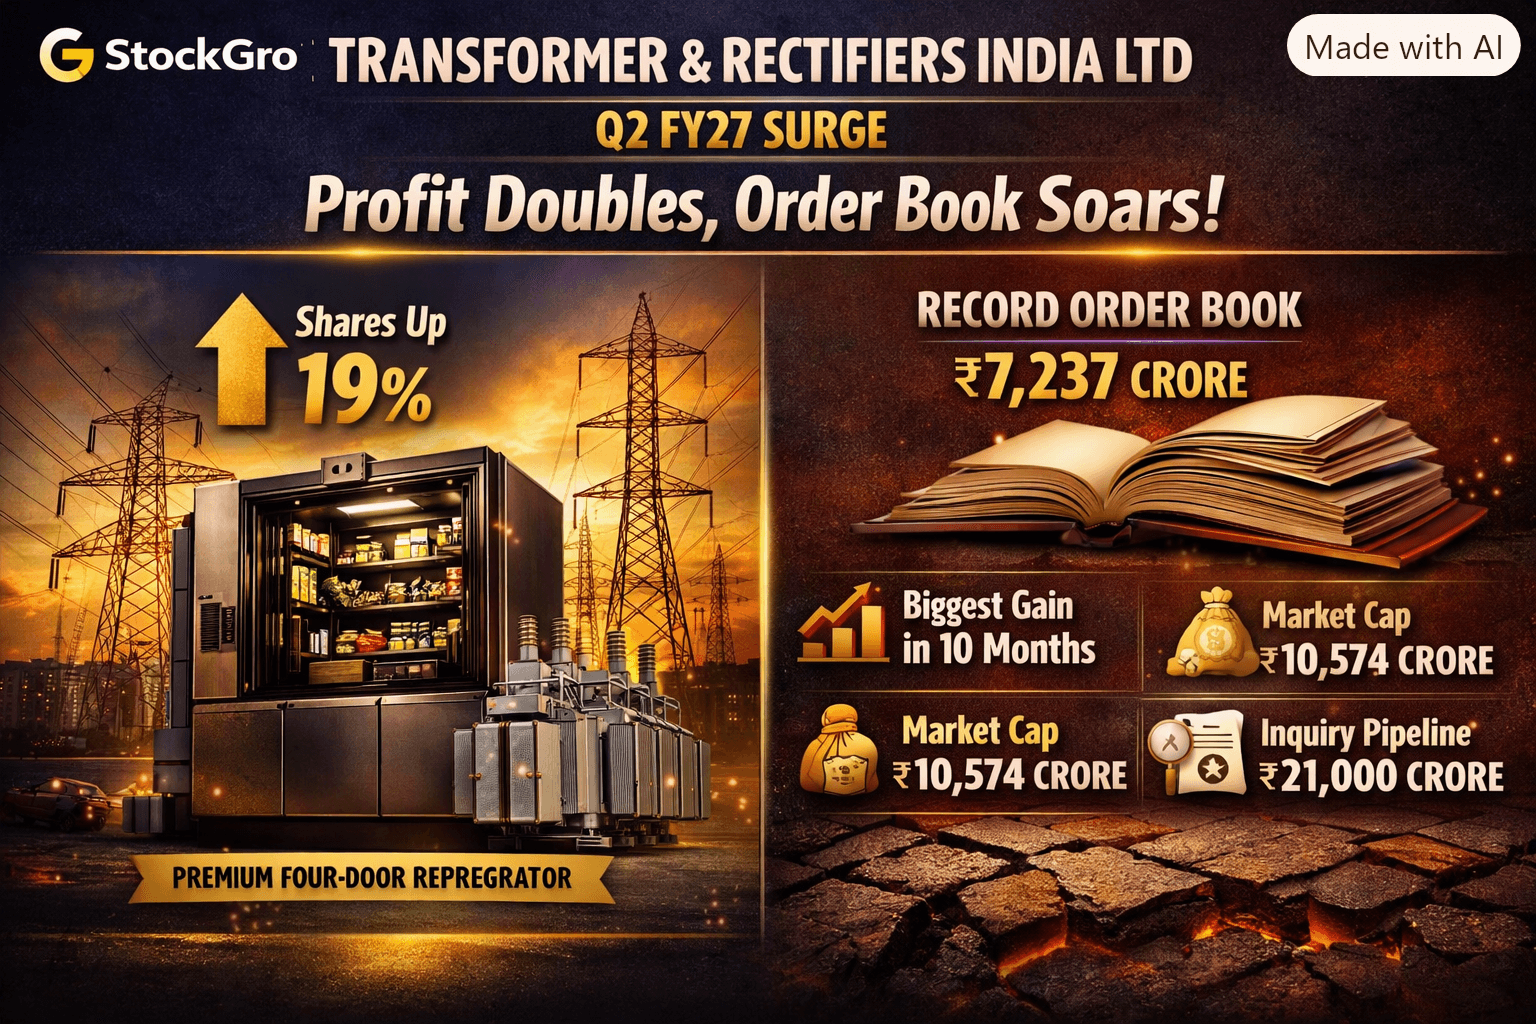
Transformer and Rectifiers (India) Ltd (TARIL) shares surged nearly 19% to ₹360.95 on October 14, 2026, after reporting stellar Q2 FY27 results — net profit up 135%, EBITDA margin expanding to 16.1%, and a record ₹7,237 crore order book. The rally marks TARIL’s biggest single‑day gain in 10 months, driven by strong execution and capacity utilization improvements.
⚡ TARIL Q2 FY27 Highlights
Metric Q2 FY27 YoY Change Key Insight
Revenue ₹739 crore +61% Strong growth from power & distribution transformer orders
EBITDA ₹114 crore +205% Margin expanded to 16.1% from 8.7%
Net Profit (PAT) ₹79.8 crore +135% Boosted by operating leverage and efficiency
Order Book ₹7,237 crore +32% Execution visibility for 18–24 months
Inquiry Pipeline ₹21,000 crore — Under negotiation; win ratio 10–15%
Stock Price ₹360.95 +19% intraday Biggest single‑day gain since Dec 2025
Market Cap ₹10,574 crore — Reflects investor confidence
🏭 Operational Drivers
Improved capacity utilization at Moraiya and Changodar plants in Gujarat.
Commercial expansion nearing completion; new transformer line expected to start production around Diwali 2026.
Product range: 5 kV–1,200 kV transformers (0.5 MVA–500 MVA) serving utilities, EPCs, industrials, and renewables across 40+ countries.
Installed capacity: 75,000 MVA across three plants.
📈 Market & Analyst Outlook
Antique Broking: Maintains BUY rating; revised target ₹449, citing strong tender pipeline and disciplined execution.
InCred Equities: Reduce call; target ₹200, noting valuation stretch despite margin gains.
FY27 Guidance:
Revenue growth 25%
EBITDA margin 16%
PAT margin 9–10%
Utilization target 90% by FY28 on expanded capacity.
🔍 Strategic Context
TARIL’s surge aligns with India’s power‑infrastructure expansion and renewable‑energy integration. The company’s backward‑integration capex (₹1.2 billion) for components like bushings, pressboard, and CRGO steel aims to lift margins further.