‹ All Posts
Apurva Harsh Vira

1 hour ago · SEBI Registration INH000024064

Urban Company Q2 Loss Triples Despite 41% Revenue Growth
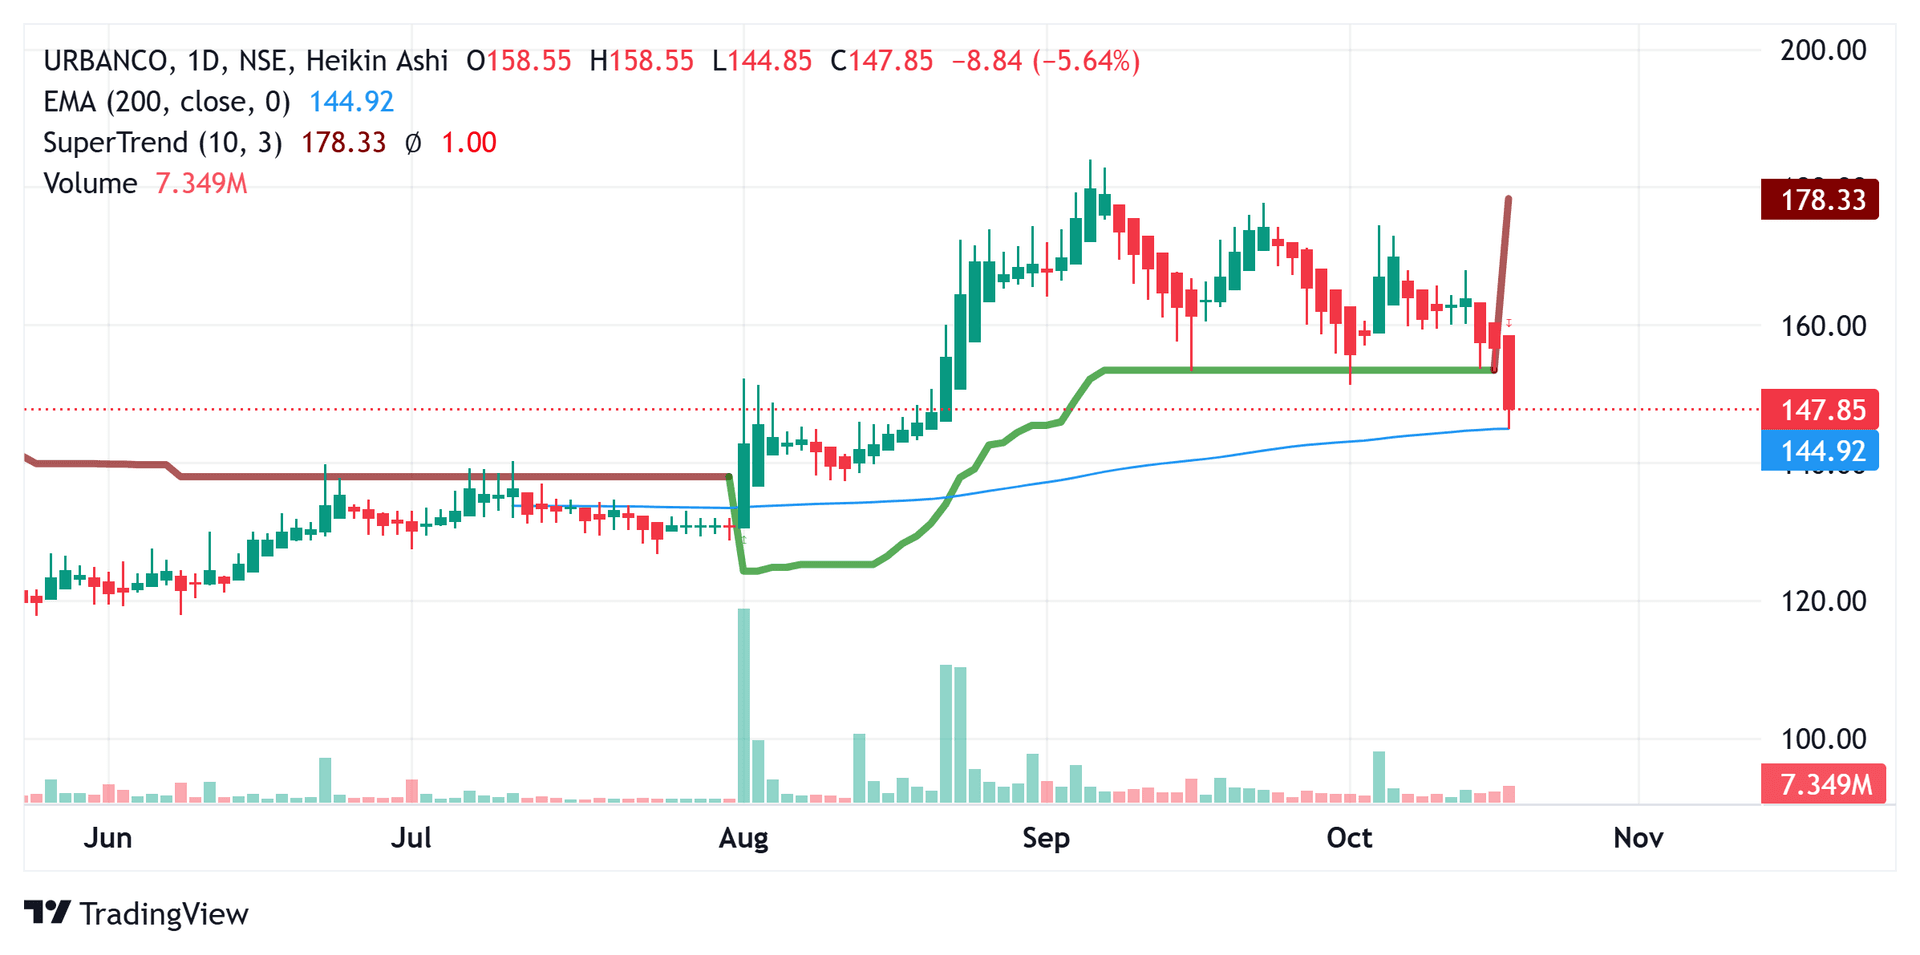
URBANCO
(URBANCO) reported a consolidated net loss of ₹182.5 crore in Q2 FY27, compared with ₹59.3 crore in the same quarter last year, despite revenue growing 41.4% YoY to ₹537.3 crore. The widening losses were primarily driven by aggressive investments in its quick home-services platform, InstaHelp. Total expenses increased 61% YoY to ₹745.7 crore, while EBITDA losses widened to ₹187.6 crore from ₹68.4 crore. InstaHelp recorded 6.2 million orders during the quarter, growing 63% sequentially, with net transaction value reaching ₹71 crore. However, InstaHelp's adjusted EBITDA loss stood at ₹174 crore. The loss per order improved from ₹346 to ₹279, indicating better unit economics, but higher order volumes and expansion spending continued to increase overall losses. From a research perspective, Urban Company's core business remains relatively strong, with India Consumer Services revenue, excluding InstaHelp, growing 28.4% YoY to ₹336.4 crore. However, rising competition from Snabbit and Pronto could keep customer acquisition costs and pricing pressure elevated. The board has also approved a potential fundraise of up to ₹2,500 crore, subject to approvals, to support expansion and future growth opportunities. Investors should monitor InstaHelp's losses per order, cash burn, competitive pricing and progress towards profitability. The key question is whether rapid expansion can eventually translate into sustainable earnings. Learning Takeaway: High revenue growth does not necessarily mean a company is becoming more profitable. Investors should evaluate operating expenses, unit economics and cash burn alongside sales growth. Disclosure: This post is for educational purposes only and does not constitute investment advice. Any holdings or conflicts of interest should be disclosed separately.

#FundamentalViews#EquityResearch#WatchOutFor#StockInNews
URBANCO_2026-10-19_10-08-23.png
24 likes·25 comments